PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125320

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125320
Automotive Airbags - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the automotive airbags market size is expected to grow from USD 27.98 billion in 2025 to USD 31.14 billion in 2026 and is forecast to reach USD 53.13 billion by 2031 at 11.30% CAGR over 2026-2031.
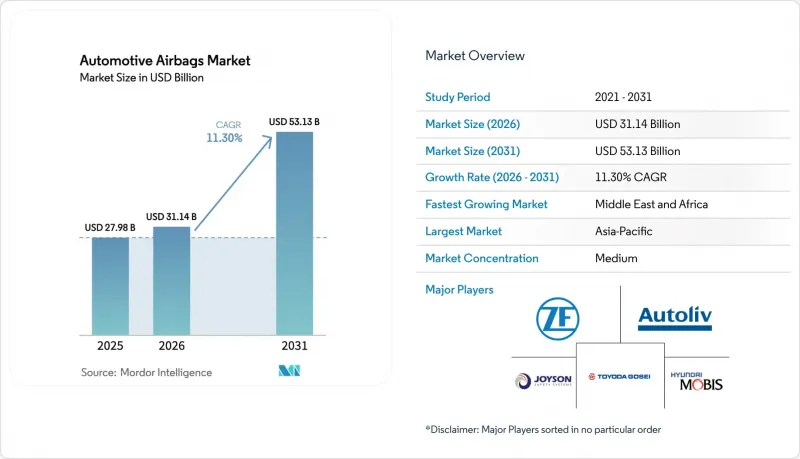
This report is Segmented by Vehicle Type (Passenger Cars and Commercial Vehicles), Propulsion Type (Internal Combustion Engine (ICE) Vehicles and More), Component (Airbag Module, Inflator, and More), Material (Nylon 66 and More), Position/Airbag Type (Front Airbags and More), Sales Channel (OEM and More) and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Automotive Airbags Market Trends and Insights
Stringent Frontal and Side-Impact Safety Mandates in Emerging Economies
Rapid regulatory rollouts have amplified unit volumes for the automotive airbags market. India's rule requiring dual front airbags on all passenger vehicles from January 2025 alone adds nearly 10 million annual units. Brazil's comparable mandate pushed national airbag penetration close to full coverage. These rules dovetail with consumer awareness campaigns and favorable insurance terms, accelerating factory install rates. Suppliers are ramping localized production to meet lead-time targets while maintaining global quality standards, ensuring cost parity for price-sensitive segments.
EV-Platform Packaging Needs Driving Multi-Module Integration
Battery placement and flat-floor cabins in EVs reshape crash dynamics, compelling designers to adopt specialized airbags. Autoliv's Bernoulli Airbag(TM) accommodates wide cabin geometries and reduces inflator heat by 30%. Center airbags like Hyundai Mobis' 2025 unit prevent driver-passenger contact in side impacts. These bespoke modules increase average airbags per EV, widening the automotive airbags market opportunity while pushing R&D toward lighter gas generators that minimize thermal stress around high-voltage packs.
Semiconductor Shortages Disrupting Output
Airbag ECUs rely on 32-bit microcontrollers, and allocation shortfalls cut 2024 global vehicle output by 2.3 million units. Suppliers reported order backlogs stretching 28 weeks, prompting automakers to favor high-margin models. Component costs climbed 12-15% against 2023 benchmarks, squeezing Tier-2 margins. Strategic buffering and foundry-level agreements are stabilizing supply, yet the situation continues to cap near-term expansion for the automotive airbags market.
Other drivers and restraints analyzed in the detailed report include:
- Rising SUV Mix Spurring Demand for Side-Curtain Airbags in North America
- Mandatory Dual-Airbag Rules in India and Similar Developing Markets
- Counterfeit Aftermarket Airbags Erode Consumer Confidence
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger cars accounted for 71.88% of the automotive airbags market in 2025, buoyed by larger build counts and rising airbags per car. Commercial vehicles, however, are pacing faster with an 8.12% CAGR through 2031, as Europe's General Safety Regulation mandates advanced restraint systems for new heavy-duty models starting in 2025. Fleet managers value the documented 42% reduction in injury-related downtime delivered by full airbag suites, a payoff that offsets upfront costs. The automotive airbags market size for commercial vehicles is projected to climb steadily, leveraging telematics-driven insurance discounts that reward safety-equipped trucks.
Surging e-commerce has intensified long-haul freight activity, calling for better driver protection in congested corridors. North American fleets are specifying side-curtain and knee airbags in Class 8 tractors, elevating average airbag content from two units in 2020 to five units in 2025. With regulators eyeing further occupant-safety enhancements, commercial platforms present a robust incremental opportunity for the automotive airbags market.
ICE vehicles still dominate volume with an 86.65% share in 2025, yet BEVs exhibit the fastest growth in the automotive airbags market with a 14.85% CAGR through 2031. Battery packs curb traditional crumple zones, prompting the adoption of external pre-crash airbags and lower-temperature inflators. Autoliv's low-heat gas generator addresses fire-safety constraints near high-voltage systems, widening design flexibility. The automotive airbags market size for BEVs is set to compound as global electric-vehicle sales exceed 17 million units in 2024, each requiring supplementary restraint modules.
Hybrid and plug-in hybrid models are growing at a 8.85% CAGR, driving demand for dual-mode deployment algorithms that accommodate both combustion and electric components. Suppliers integrate machine-learning logic into ECUs, parsing 400 data points per second to adjust inflation force. Such complexity lifts ECU revenue share and consolidates the automotive airbags market around players with software-heavy portfolios.
Complete Report Scope:
- By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- By Propulsion Type
- Internal Combustion Engine Vehicles (ICE)
- Battery Electric Vehicles (BEV)
- Hybrid & Plug-in Hybrid Vehicles (HEV/PHEV)
- Fuel-Cell Electric Vehicles (FCEV)
- By Component
- Airbag Module
- Inflator
- Crash Sensor & ECU
- Airbag Fabric
- By Material
- Nylon 66
- Nylon 6
- Polyester
- By Position/Airbag Type
- Front Airbags
- Side Airbags
- Curtain Airbags
- Knee Airbags
- Inflatable Seat-Belts
- By Sales Channel
- Original Equipment Manufacturer (OEM)
- Aftermarket/Replacement
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Turkey
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific controlled 42.10% of the automotive airbags market in 2025, anchored by China's production of over 220 million airbag units and India's dual-airbag mandate. Average airbag count per vehicle in China rose from 2.3 in 2020 to 4.8 in 2025, underpinned by domestic brands chasing Euro NCAP compliance for export models. Japan and South Korea contribute engineering depth and manufacturing scale, supplying modules to global OEM platforms. Regional suppliers such as Joyson leverage proximity to major assemblers, shortening lead times and deepening integration in next-generation EV programs.
The Middle East is the fastest-growing sub-region, projected to grow at a 14.90% CAGR through 2031. Gulf Cooperation Council countries tighten safety regulations and favor large SUVs, boosting airbags per vehicle beyond global averages. Local assembly ventures in Saudi Arabia and the United Arab Emirates lure Tier-1s to establish inflator and cushion facilities, positioning the region as an export hub into Africa and parts of Europe. The 2025 Nissan Patrol, fitted with seven airbags including knee units, exemplifies rising consumer expectations.
North America and Europe collectively make up nearly half of global revenue. North American growth rides on SUV popularity and stringent FMVSS side-impact updates, while Europe's General Safety Regulation layers new obligations for far-side and pedestrian airbags starting 2026. Both regions spearhead AI-enabled ECUs and greener propellants, innovations that later cascade to emerging markets, reinforcing global homogeneity in safety standards across the automotive airbags market.
- Autoliv Inc.
- ZF Friedrichshafen AG (ZF TRW)
- Joyson Safety Systems
- Toyoda Gosei Co. Ltd
- Hyundai Mobis Co. Ltd
- Continental AG
- Daicel Corporation
- Nihon Plast Co. Ltd
- Ashimori Industry Co. Ltd
- Sumitomo Corporation (Airbag Fabric)
- Robert Bosch GmbH
- Kolon Industries Inc.
- Yanfeng Automotive Trim Systems Co. Ltd
- Jinzhou Jinheng Automotive Safety System Co. Ltd
- Denso Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent frontal & side-impact safety mandates in emerging economies
- 4.2.2 EV-platform packaging needs driving multi-module integration
- 4.2.3 Rising SUV mix spurring demand for side-curtain airbags in North America
- 4.2.4 Mandatory dual-airbag rule in India and similar developing markets
- 4.2.5 Insurance-telematics-linked incentives for fleet safety upgrades
- 4.2.6 Chinese OEM export push demanding Euro-NCAP-compliant airbags
- 4.3 Market Restraints
- 4.3.1 Semiconductor & inflator propellant shortages disrupting output
- 4.3.2 Counterfeit aftermarket airbags eroding consumer confidence
- 4.3.3 Escalating zero-defect R&D costs squeezing Tier-2 margins
- 4.3.4 EV lightweighting driving exploration of alternative restraints
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Supplier Information
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Vehicle Type
- 5.1.1 Passenger Cars
- 5.1.2 Commercial Vehicles
- 5.2 By Propulsion Type
- 5.2.1 Internal Combustion Engine Vehicles (ICE)
- 5.2.2 Battery Electric Vehicles (BEV)
- 5.2.3 Hybrid & Plug-in Hybrid Vehicles (HEV/PHEV)
- 5.2.4 Fuel-Cell Electric Vehicles (FCEV)
- 5.3 By Component
- 5.3.1 Airbag Module
- 5.3.2 Inflator
- 5.3.3 Crash Sensor & ECU
- 5.3.4 Airbag Fabric
- 5.4 By Material
- 5.4.1 Nylon 66
- 5.4.2 Nylon 6
- 5.4.3 Polyester
- 5.5 By Position/Airbag Type
- 5.5.1 Front Airbags
- 5.5.2 Side Airbags
- 5.5.3 Curtain Airbags
- 5.5.4 Knee Airbags
- 5.5.5 Inflatable Seat-Belts
- 5.6 By Sales Channel
- 5.6.1 Original Equipment Manufacturer (OEM)
- 5.6.2 Aftermarket/Replacement
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Rest of North America
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Spain
- 5.7.3.5 Italy
- 5.7.3.6 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 Saudi Arabia
- 5.7.5.2 United Arab Emirates
- 5.7.5.3 Turkey
- 5.7.5.4 South Africa
- 5.7.5.5 Egypt
- 5.7.5.6 Rest of Middle East and Africa
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Autoliv Inc.
- 6.4.2 ZF Friedrichshafen AG (ZF TRW)
- 6.4.3 Joyson Safety Systems
- 6.4.4 Toyoda Gosei Co. Ltd
- 6.4.5 Hyundai Mobis Co. Ltd
- 6.4.6 Continental AG
- 6.4.7 Daicel Corporation
- 6.4.8 Nihon Plast Co. Ltd
- 6.4.9 Ashimori Industry Co. Ltd
- 6.4.10 Sumitomo Corporation (Airbag Fabric)
- 6.4.11 Robert Bosch GmbH
- 6.4.12 Kolon Industries Inc.
- 6.4.13 Yanfeng Automotive Trim Systems Co. Ltd
- 6.4.14 Jinzhou Jinheng Automotive Safety System Co. Ltd
- 6.4.15 Denso Corporation
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

