PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155308

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155308
South America Airbag Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
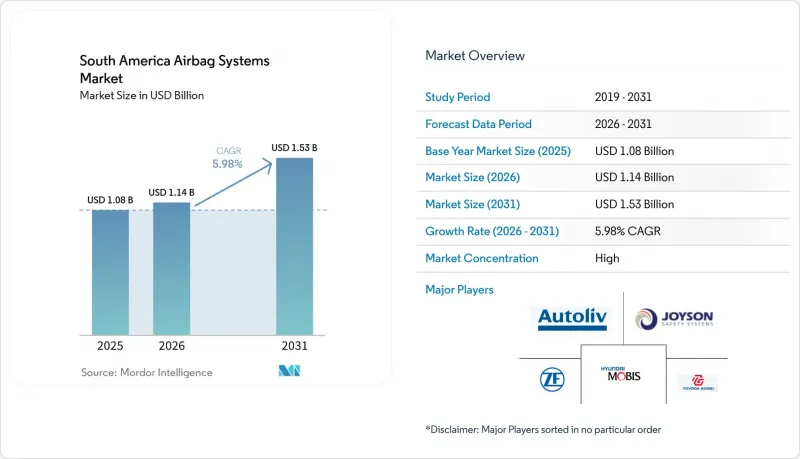
According to Mordor Intelligence, the South American airbag systems market size was valued at USD 1.08 billion in 2025, is estimated at USD 1.14 billion in 2026, and is projected to reach USD 1.53 billion by 2031, growing at a CAGR of 5.98% from 2026 to 2031.
South America Airbag Systems Market Trends and Insights
Stricter Region-Wide Airbag Regulations
Safety rules across South America are moving beyond minimum equipment requirements toward crash-performance expectations. Brazil's CONTRAN Resolution 964/2022 requires frontal airbags in M1 and N1 vehicles, establishing a clear baseline for both locally produced and imported models. Resolution 949/2022 also established lateral occupant-protection testing requirements for sedans, SUVs, and pickups. Latin NCAP's 2026-2029 protocol introduced a 60 km/h side-barrier test and a 32 km/h side-pole test, increasing the value of side and curtain protection in vehicle design. The protocol also considers ISOFIX availability and the ability to deactivate the passenger airbag, thereby connecting child safety features to restraint-system decisions. These requirements encourage automakers to standardize broader airbag packages before a facelift or a new model launch.
OEM Production Expansion in Brazil
Brazil's new vehicle programs create recurring demand for locally supplied airbag systems. General Motors increased its investment commitment in Brazil for hybrid vehicles, manufacturing modernization, and engineering capabilities. Changan and CAOA began local production of the Uni-T SUV in Anapolis in March 2026 as part of a USD 950 million investment cycle for 2026-2028 . The new platforms require dedicated homologation and give suppliers an opportunity to secure contracts for the duration of each production run. Chinese automakers entering Brazil commonly introduce vehicles with comprehensive safety equipment, which can raise the average number of airbags per locally produced vehicle. The South American airbag system market benefits when local assembly programs combine volume growth with higher safety content rather than relying only on unit output.
Price-Sensitive Entry-Level Segment Limits Adoption
Entry-level vehicles remain difficult to equip with additional airbags when rules do not require them. Vehicle makers in this category must balance equipment upgrades with the affordability buyers expect. This constraint is more evident in Brazil and Argentina, where imported components and macroeconomic uncertainty can raise sourcing costs. Manufacturers can more easily add 4 or 6 airbags to higher-priced SUVs and pickups, where the safety package is easier to support within the vehicle's price. The result is a split within the South American airbag system market, with stronger content growth in mid-range and premium vehicles. The entry-level segment continues to slow the adoption of optional restraint systems.
Other drivers and restraints analyzed in the detailed report include:
- Rising SUV and Pickup Penetration Boosting Multi-Airbag Count
- Growing Consumer Focus on NCAP Safety Ratings
- Prevalence of Counterfeit Airbag Imports
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Front modules already penetrate close to 100% of new builds, yet they still generated 46.24% of 2025 revenue owing to sheer volume. Curtain airbags are forecast to grow at a 6.19% CAGR between 2026 and 2031 as Colombia and Chile legislate ejection-mitigation performance, edging their share toward one-quarter of the South America airbag systems market by the end of the decade. Side-thorax units, benefiting from NCAP's pole-impact criteria, account for a significant portion of the market value. Knee airbags serve as a premium feature, distinguishing trims of the Volkswagen Taos and Toyota Corolla Cross. While center and seatbelt airbags hold a minimal share of the market, they're primarily found in high-end crossovers and luxury imports from Germany. Suppliers see the most promise for margin expansion in innovations such as cascading roof rails or door-mounted curtains.
While front modules dominate, offering scale efficiencies, their growth is beginning to plateau. On the other hand, as regulatory timelines come into play in various Andean markets, curtains and thorax units are set to introduce new content layers in vehicles. Future technology trends highlight a shift towards lighter fabrics, sealed seams that reduce fill gas volumes, and AI-driven inflator logic that adapts to occupant posture. Curtailed airbag revenues are expected to drive a significant portion of the growth in South America's airbag systems market.
Passenger cars accounted for 73.16% of the South American airbag system market in 2025, reflecting the high volume of this vehicle category in the region. Passenger cars provide the base demand for frontal airbag modules and related electronic controls. Light commercial vehicles are projected to grow at a 6.23% CAGR through 2031. Pickups make up a major part of this expansion because they are used for both personal and commercial transport. These vehicles typically include 4 to 6 airbags as standard safety equipment. The higher system count makes their contribution to airbag revenue greater than vehicle registrations alone suggest. The ongoing pickup-and-SUV shift, therefore, supports airbag demand beyond the passenger-car base.
Medium and heavy commercial vehicles, along with buses and coaches, hold smaller absolute shares. Their safety requirements have historically developed more slowly than requirements for passenger vehicles in the region. Fleet operators are nevertheless placing more weight on occupant protection and insurance considerations. Volvo Trucks made integrated side-curtain airbags standard on its new VNL and VNR models for North America in February 2026 . The move provides a relevant example as vehicle safety specifications converge across global platforms. South American commercial-vehicle adoption may emerge ahead of formal regulatory schedules when fleet buyers seek broader safety equipment. Established suppliers already serving regional fleets are positioned to address this demand.
Complete Report Scope:
- By Airbag Type
- Front Airbags
- Side Airbags
- Curtain Airbags
- Knee Airbags
- Center Airbags
- Seatbelt Airbags
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles (LCVs)
- Medium & Heavy Commercial Vehicles (MHCVs)
- Buses and Coaches
- By Component
- Airbag Module
- Crash Sensor
- Inflator
- Diagnostic Sensor
- Control Unit
- Others
- By Sales Channel
- Original Equipment Manufacturer
- Aftermarket
- By Country
- Brazil
- Argentina
- Colombia
- Chile
- Rest of South America
List of Companies Covered in this Report:
- Autoliv Inc.
- ZF Friedrichshafen AG (ZF TRW)
- Joyson Safety Systems
- Toyoda Gosei Co., Ltd.
- Hyundai Mobis Co., Ltd.
- Continental AG
- Robert Bosch GmbH
- Denso Corporation
- Faurecia SE
- Yanfeng Safety Systems
- Kolon Industries, Inc.
- Toyobo Co., Ltd.
- TE Connectivity Ltd.
- Key Safety Systems
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stricter Region-Wide Airbag Regulations
- 4.2.2 OEM Production Expansion in Brazil
- 4.2.3 Rising SUV and Pickup Penetration Boosting Multi-Airbag Count
- 4.2.4 Growing Consumer Focus on NCAP Safety Ratings
- 4.2.5 Fleet Insurance Incentives for Side-Curtain Airbags
- 4.2.6 Localization of Inflator Manufacturing Lowering Cost Barriers
- 4.3 Market Restraints
- 4.3.1 Price-Sensitive Entry-Level Segment Limits Adoption
- 4.3.2 Prevalence of Counterfeit Airbag Imports
- 4.3.3 Supply-Chain Disruptions for Specialized Propellant Chemicals
- 4.3.4 Integration Challenges of Center Airbags With Legacy Platforms
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value in USD)
- 5.1 By Airbag Type
- 5.1.1 Front Airbags
- 5.1.2 Side Airbags
- 5.1.3 Curtain Airbags
- 5.1.4 Knee Airbags
- 5.1.5 Center Airbags
- 5.1.6 Seatbelt Airbags
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Light Commercial Vehicles (LCVs)
- 5.2.3 Medium & Heavy Commercial Vehicles (MHCVs)
- 5.2.4 Buses and Coaches
- 5.3 By Component
- 5.3.1 Airbag Module
- 5.3.2 Crash Sensor
- 5.3.3 Inflator
- 5.3.4 Diagnostic Sensor
- 5.3.5 Control Unit
- 5.3.6 Others
- 5.4 By Sales Channel
- 5.4.1 Original Equipment Manufacturer
- 5.4.2 Aftermarket
- 5.5 By Country
- 5.5.1 Brazil
- 5.5.2 Argentina
- 5.5.3 Colombia
- 5.5.4 Chile
- 5.5.5 Rest of South America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.4.1 Autoliv Inc.
- 6.4.2 ZF Friedrichshafen AG (ZF TRW)
- 6.4.3 Joyson Safety Systems
- 6.4.4 Toyoda Gosei Co., Ltd.
- 6.4.5 Hyundai Mobis Co., Ltd.
- 6.4.6 Continental AG
- 6.4.7 Robert Bosch GmbH
- 6.4.8 Denso Corporation
- 6.4.9 Faurecia SE
- 6.4.10 Yanfeng Safety Systems
- 6.4.11 Kolon Industries, Inc.
- 6.4.12 Toyobo Co., Ltd.
- 6.4.13 TE Connectivity Ltd.
- 6.4.14 Key Safety Systems
7 Market Opportunities and Future Outlook

