PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125477

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125477
Endometriosis Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the endometriosis treatment market size was valued at USD 1.78 billion in 2025 and is estimated to grow from USD 1.97 billion in 2026 to reach USD 3.37 billion by 2031, at a CAGR of 11.31% during the forecast period (2026-2031).
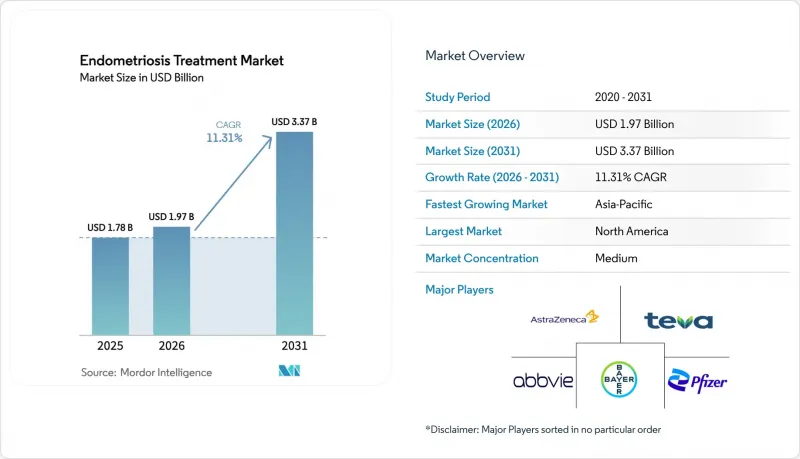
This report is Segmented by Treatment Type (Drug Therapy, Surgical Intervention, Combined/Multimodal Therapy), Drug Class (GnRH Agonists & Antagonists, Progestins, and More), Route of Administration (Oral, and More), Distribution Channel (Hospital, Retail, Online Pharmacies), and Geography (North America, Europe, Asia-Pacific, MEA, South America). Market Forecasts are Provided in Terms of Value (USD).
Global Endometriosis Treatment Market Trends and Insights
Rising Prevalence Among Reproductive-Age Women
Roughly 10% of women aged 15-49 now live with the condition, yet under-ascertainment in low-resource settings means the real figure is higher. The 2024 White House report valued the annual U.S. economic burden at USD 78 billion, compelling several state Medicaid programs to extend coverage for laparoscopic diagnosis in 2025. Later childbearing amplifies risk by extending cumulative estrogen exposure, while China recorded a 12% jump in endometriosis-related infertility consultations between 2024 and 2025. These datapoints collectively expand the addressable endometriosis treatment market and support sustained double-digit growth prospects.
Growing Awareness & Earlier Diagnosis
Hashtags such as #EndoWarrior generated more than 50 million impressions during the 2025 awareness campaign, triggering self-referral surges. NICE guidelines issued in March 2025 reduced the diagnostic interval in England by over 2 years. France's national pelvic-pain clinics lifted laparoscopic procedure volumes 23% year over year. AI-driven symptom-clustering pilots across Europe triaged high-risk patients for imaging, and patients presenting at earlier stages improve postoperative outcomes and reduce recurrence. Together, these shifts enlarge the treated population and accelerate revenue capture for the endometriosis treatment market.
Adverse Effects of Long-Term Hormone Use
Injectable GnRH agonists can lower trabecular bone density by more than 5% within six months, restricting duration without add-back estrogen. Despite mitigation, 12% of relugolix patients in the U.K. surveillance reported breakthrough bleeding requiring adjustments. Irregular bleeding affects up to 40% of continuous progestin users and is linked to reduced adherence. A Swedish cohort also reported a 1.3-fold increase in insulin resistance markers after 2 years of norethindrone. These safety issues provoke therapy cycling, which raises cumulative costs and softens real-world effectiveness across the endometriosis treatment market.
Other drivers and restraints analyzed in the detailed report include:
- Advances in Minimally Invasive Hormonal Therapies
- Emergence of Non-Hormonal Immunomodulators
- High Treatment Cost & Patchy Insurance Coverage
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Combined approaches integrating surgery with postoperative hormonal suppression are expanding at a 12.17% CAGR and eroding monotherapy dominance. Surgery alone has a 5-year recurrence rate above 40%, whereas adjuvant hormones can extend remission by up to 2 years. Drug therapy still represented 65.12% of the endometriosis treatment market share in 2025, but high switching rates betray dissatisfaction. Robotic laparoscopy gained visibility, yet 2025 evidence found no superiority in pain relief over conventional techniques. Upfront combination care lowers lifetime revisions, steering payers toward bundled reimbursement models that enlarge the endometriosis treatment market.
Sequencing trends are emerging; pre-operative hormonal downsizing can cut intraoperative blood loss, though robust trials are scarce. Nerve-sparing excision techniques help preserve organ function, broadening candidate eligibility. Drug-only regimens remain first-line for women desiring fertility preservation, but payer focus on durability is nudging clinicians toward multimodal pathways. The paradigm shift aligns endometriosis management with other chronic inflammatory diseases, reinforcing recurring revenue streams.
GnRH modulators led with a 42.07% share in 2025, yet over-the-counter NSAIDs are on track for a 13.59% CAGR through 2031. Ibuprofen and naproxen cost as little as USD 10-20 monthly, anchoring first-line pain control. Real-world German data show 68% of newly diagnosed patients start on NSAID monotherapy, underscoring cost sensitivity. Oral contraceptives account for roughly 18% but cater to users seeking dual contraception. Innovation inside the class is minimal; growth stems chiefly from volume as diagnosis rates rise, adding fresh entrants to the endometriosis treatment market size baseline.
Combination NSAID products addressing bloat or gastroprotection broaden retail shelf space. Guideline bodies also endorse NSAID continuation post-surgery to temper residual dysmenorrhea. While premium biologics court the severe-pain segment, accessible analgesics continue to expand the overall patient pool, reinforcing their share in the endometriosis treatment market.
Complete Report Scope:
- By Treatment Type
- Drug Therapy
- Surgical Intervention
- Combined / Multimodal Therapy
- By Drug Class
- Gonadotropin-Releasing Hormone (GnRH) Agonists & Antagonists
- Progestins
- Non-Steroidal Anti-Inflammatory Drugs (NSAIDs)
- Oral Contraceptives
- Selective Estrogen Receptor Modulators (SERMs)
- By Route of Administration
- Oral
- Parenteral
- Transdermal / Implant
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies & Drug Stores
- Online Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 39.27% of 2025 revenue, supported by robust insurance coverage for novel hormones and direct-to-consumer marketing. U.S. Medicaid expansions in multiple states covered laparoscopic diagnosis and GnRH antagonists, decreasing out-of-pocket costs. Canada funds generic hormones, but provinces differ on reimbursement for oral antagonists; Ontario added relugolix in April 2025. Mexico's private insurers now subsidize endometriosis procedures, yet public-sector uptake remains limited.
Asia-Pacific is projected to post the fastest CAGR of 13.42%. China's breakthrough designation for HMI-115 and rapid rollout of laparoscopic suites across tier-2 cities shorten diagnosis delays. India holds one of the highest absolute patient counts, but stigma and clinician shortages hamper detection. Japan's universal system reimburses injectable agonists while negotiations continue for orals, creating room for biosimilars and domestic generics. Australia's inclusion of dienogest on the Pharmaceutical Benefits Scheme in 2024 reduced co-pays to AUD 6.60, driving a 35% surge in prescriptions.
NICE endorsements in March and May 2025 unlocked National Health Service funding for relugolix and linzagolix. France's mandated pelvic-pain clinics lifted surgical volumes 23% year on year. Germany's insurers lean toward cost-effective NSAID initiation, reflected in high first-line ibuprofen uptake. South America and the Middle East & Africa remain nascent but are beginning to incorporate dedicated women's health benefits in urban centers. Collectively, geographic diversification underpins the widening landscape of endometriosis treatment markets.
- Abbvie
- Arbor Vita
- AstraZeneca
- Bayer
- Beckton Dickinson
- bioMerieux
- Celmatix Inc.
- Eli Lilly and Company
- Endoceutics Inc.
- Ferring Pharmaceuticals
- Guided Therapeutics
- Illumina
- Johnson & Johnson
- LabCorp
- Merck
- Pfizer
- QIAGEN
- Quest Diagnostics
- Roche
- Sansure Biotech
- Seegene
- Siemens Healthineers
- Sun Pharma Industries Ltd.
- Takeda Pharmaceuticals
- Teva Pharmaceutical Industries
- Thermo Fisher Scientific
- Zytovision GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence Among Reproductive-Age Women
- 4.2.2 Growing Awareness & Earlier Diagnosis
- 4.2.3 Advances in Minimally Invasive Hormonal Therapies
- 4.2.4 Emergence of Non-Hormonal Immunomodulators
- 4.2.5 Venture Capital Inflow into Regenerative Approaches
- 4.2.6 AI-Based Early Detection & Digital Therapeutics
- 4.3 Market Restraints
- 4.3.1 Adverse Effects of Long-Term Hormone Use
- 4.3.2 High Treatment Cost & Patchy Insurance Coverage
- 4.3.3 Clinical-Trial Recruitment Complexity
- 4.3.4 Social Stigma Delaying Care-Seeking
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Treatment Type
- 5.1.1 Drug Therapy
- 5.1.2 Surgical Intervention
- 5.1.3 Combined / Multimodal Therapy
- 5.2 By Drug Class
- 5.2.1 Gonadotropin-Releasing Hormone (GnRH) Agonists & Antagonists
- 5.2.2 Progestins
- 5.2.3 Non-Steroidal Anti-Inflammatory Drugs (NSAIDs)
- 5.2.4 Oral Contraceptives
- 5.2.5 Selective Estrogen Receptor Modulators (SERMs)
- 5.3 By Route of Administration
- 5.3.1 Oral
- 5.3.2 Parenteral
- 5.3.3 Transdermal / Implant
- 5.4 By Distribution Channel
- 5.4.1 Hospital Pharmacies
- 5.4.2 Retail Pharmacies & Drug Stores
- 5.4.3 Online Pharmacies
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 AbbVie Inc.
- 6.3.2 Arbor Vita Corporation
- 6.3.3 AstraZeneca
- 6.3.4 Bayer AG
- 6.3.5 Becton, Dickinson and Company
- 6.3.6 bioMerieux SA
- 6.3.7 Celmatix Inc.
- 6.3.8 Eli Lilly and Company
- 6.3.9 Endoceutics Inc.
- 6.3.10 Ferring Pharmaceuticals
- 6.3.11 Guided Therapeutics
- 6.3.12 Illumina Inc.
- 6.3.13 Johnson & Johnson (Janssen)
- 6.3.14 LabCorp
- 6.3.15 Merck & Co., Inc.
- 6.3.16 Pfizer Inc.
- 6.3.17 Qiagen N.V.
- 6.3.18 Quest Diagnostics
- 6.3.19 Roche Diagnostics
- 6.3.20 Sansure Biotech
- 6.3.21 Seegene Inc.
- 6.3.22 Siemens Healthineers
- 6.3.23 Sun Pharma Industries Ltd.
- 6.3.24 Takeda Pharmaceutical Co. Ltd.
- 6.3.25 Teva Pharmaceutical Industries Ltd.
- 6.3.26 Thermo Fisher Scientific
- 6.3.27 Zytovision GmbH
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

