PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125554

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125554
Light Commercial Vehicles - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the light commercial vehicles market size is expected to grow from USD 495.44 billion in 2025 to USD 525.71 billion in 2026 and is forecast to reach USD 707.17 billion by 2031 at a 6.11% CAGR over 2026-2031.
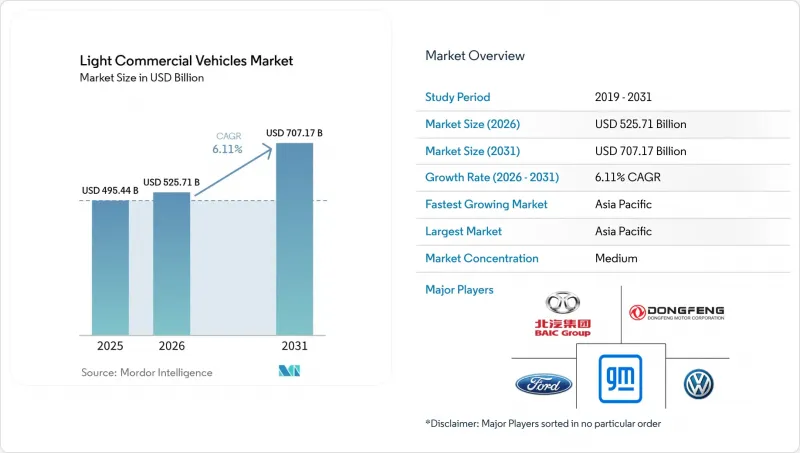
This report is Segmented by Vehicle Type (Pick-Up Trucks and Vans), Propulsion Type (ICE, Hybrid, Battery-Electric, and Fuel-Cell Electric), Application (Commercial Delivery & Logistics and More), Ownership Model (Fleet-Owned and More), Payload (Less Than or Equal To 2. 5t and More), and Geography. Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Light Commercial Vehicles Market Trends and Insights
Stringent Global CO2 & NOx Standards with Fiscal Incentives
Starting mid-2025, Euro 7 mandates a significant reduction in real-world NOx emissions, requiring levels much lower than the previous Euro 6d-TEMP standards. This change is expected to substantially increase diesel after-treatment costs, thereby reducing the price difference between diesel vehicles and battery-electric vans . In China, the dual-credit system encourages manufacturers by offering additional credits for each zero-emission light commercial vehicle sold, driving an increase in new-energy vehicle production. The EPA's Phase 3 greenhouse-gas rule, applicable to future model years, sets ambitious CO2 reduction targets for light trucks, indirectly promoting a notable share of electric vehicles . Similarly, India's Bharat Stage VI Phase 2 enforces stricter particulate emission limits and requires on-board diagnostics, accelerating the phase-out of older fleets that align with Euro 4 standards.The LCV Market is expected to be influenced by these evolving emission regulations and the resulting shift toward cleaner vehicle technologies.
Exploding Last-Mile E-Commerce Demand
In 2024, e-commerce transactions in the U.S. reached a significant milestone, accounting for a substantial portion of total retail sales. Notably, even a small increase in this penetration translates to a considerable demand for additional vans or pickups. Fleet operators are now prioritizing features such as low cargo floors for easier loading, side doors for convenient curbside access, and sufficient real-world range to support their duty cycles. By mid-2024, Amazon had deployed a large number of electric delivery vans from Rivian, realizing notable reductions in operating costs per mile compared to retrofitted diesel counterparts, due to diminished brake and transmission wear. As vehicle utilization in bustling cities continues to rise, replacement cycles have shortened significantly. This accelerated churn in the light commercial vehicle market is leading to growing order backlogs at major OEMs.
High Upfront Cost of ELCVs Despite Falling Battery Prices
Electric vans carry a significant premium over their diesel counterparts, primarily due to development costs being distributed across a smaller volume and elevated warranty reserves. In 2024, Ford's base E-Transit was priced notably higher than its diesel Transit counterpart. This substantial price difference poses challenges for operators with constrained capital budgets. In India, even after accounting for subsidies, Tata's Ace EV was priced at a considerably higher premium compared to the traditional internal-combustion Ace, a disparity further exacerbated by the additional expense of required chargers. In Europe, weak prices for used electric vehicles (EVs) experienced a notable decline in 2024, dampening lease residuals and tightening credit availability.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Battery-Cost Decline Below USD 100/kWh
- Fleet Telematics Lowering TCO & Accelerating Renewal Cycles
- Charging Infrastructure Gaps Outside Depot Environments
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pick-up trucks captured 45.57% of the light commercial vehicle market share in 2025. Vans, however, are forecast to expand at a 6.15% CAGR through 2031 as ultra-low-emission zones encourage compact, aerodynamic bodies that slip into tight curb spaces. The light commercial vehicle market size for vans is projected to grow faster than any other vehicle class, reinforced by battery-electric variants that now meet 150-200-mile duty cycles.
Ford's F-150 Lightning shows pickups are diversifying roles with on-site power export, yet parcel giants favor high-cube vans that maximize cargo per square meter. In Europe, compact models such as Stellantis e-Berlingo thrive inside city walls, while medium vans dominate perishables and parcel segments. Crew-cab vans that seat technicians plus tools blur category lines, underscoring converging use cases in the light commercial vehicle market.
Internal-combustion units still supplied 77.81% of 2025 production, supported by existing service networks and long-range flexibility. Electric alternatives nevertheless post a 6.22% CAGR through 2031 as Section 45W and Euro 7 pressure tip total cost calculations. Rivian's EDV validated battery economics on 120-mile urban loops, while hybrid vans struggle to meet zero-emission mandates and lose ground.
Fuel-cell volumes remain marginal, constrained by 59 hydrogen stations in the United States during 2024, though Japan and South Korea pilot corridors for routes beyond 200 miles. As battery costs decline, the light commercial vehicle market size attached to electric drivetrains widens, capturing incremental share in dense city zones despite payload trade-offs.
Complete Report Scope:
- By Vehicle Type
- Pick-up Trucks
- Vans (Compact, Medium, Heavy)
- By Propulsion Type
- ICE
- Hybrid
- Battery-Electric
- Fuel-Cell Electric
- By Application
- Commercial Delivery & Logistics
- Industrial / Construction Support
- Municipal & Public Services
- By Ownership Model
- Fleet-Owned
- Leased
- Subscription / VaaS
- By Payload (GVW Class)
- Less than or equal to 2.5 t
- 2.6 - 3.5 t
- More than 3.5 t
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Spain
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Australia & New Zealand
- Rest of Asia Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia Pacific held 38.62% of the light commercial vehicle market in 2025 and is expected to register a 6.18% CAGR to 2031. In 2024, China's dual-credit rewards and local subsidies significantly boosted sales of commercial new-energy vehicles to substantial levels. Meanwhile, India's production-linked incentives attracted considerable investment commitments. Notably, Tata's Ace EV achieved notable sales, even commanding a significant price premium. Japan is addressing its aging driver demographic by testing autonomous kei trucks. In a strategic move, Thailand introduced an extended tax holiday, successfully attracting a major investment in local assembly .
Europe accounted for a significant share of the 2025 market volumes, supported by numerous zero-emission zones that restrict older vehicle models. With stringent mandates for CO2 emission reductions by 2030, the continent is driving a substantial shift toward electric vehicles, accelerating the phase-out of diesel. North America captured a comparable market share but adopted a different approach, focusing on subsidies rather than outright bans. For instance, tax credits subsidize a significant portion of the electric premium, and a rebate program in Canada substantially increased light commercial EV registrations in 2024. Furthermore, fleet commitments from major companies like Amazon, FedEx, and Walmart are sustaining order backlogs for several years.
South America, alongside the Middle East & Africa, collectively represents a smaller portion of the global market value. While Brazil's Rota 2030 initiative promotes ethanol-friendly flex-fuel engines, Argentina faces economic challenges that hinder EV investments, despite the nation's abundant lithium resources. South Africa is making progress with grid stabilization and a private charging rollout, signaling a potential shift in the future. However, the country's current EV penetration remains minimal compared to Europe and China.
- Ford Motor Company
- Toyota Motor Corporation
- Stellantis N.V.
- Daimler AG (Mercedes-Benz Vans)
- Renault Group
- General Motors Company
- Volkswagen AG
- Nissan Motor Co. Ltd.
- Hyundai Motor Company
- Tata Motors Limited
- Mahindra & Mahindra Limited
- Isuzu Motors Limited
- BYD Auto Co. Ltd.
- Dongfeng Motor Corporation
- Ashok Leyland Limited
- Volvo Group
- Rivian Automotive Inc.
- BAIC Motor Corporation Ltd.
- Gaz Group
- Iveco Group N.V.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Key Industry Trend
- 4.1 Urbanization, Population & Vehicle/Transit Demand
- 4.2 LCV Ownership & Motorization Rate
- 4.3 EV Penetration in LCV Market
- 4.4 Fuel vs Electricity Price Spread (Per km, ICE vs EV)
- 4.5 EV vs ICE Total Cost of Ownership (TCO) Gap
- 4.6 Financing & Ownership Models (Loans, Leasing, Subscription)
- 4.7 Battery Chemistry Mix & Pack Energy Density (LFP vs NMC etc.)
- 4.8 Home, Workplace & Public Charger Access / Density
- 4.9 Fast-Charging Network Coverage & Power Bands
- 4.10 Alternative Fuels Infrastructure (Hydrogen for FCEVs)
- 4.11 Subsidy & Consumer Incentive Value (Purchase, Tax, Toll/Parking Benefits)
- 4.12 OEM EV Line-up & Model Pipeline
- 4.13 Value-Chain & Distribution-Channel Analysis
- 4.14 Regulatory, Fiscal & Industrial Policy Framework
5 Market Landscape
- 5.1 Market Overview
- 5.2 Market Drivers
- 5.2.1 Stringent Global Co2 & NOX Standards With Fiscal Incentives
- 5.2.2 Exploding Last-Mile E-Commerce Demand
- 5.2.3 Rapid Battery-Cost Decline Below USD 100 /Kwh
- 5.2.4 Fleet Telematics Lowering TCO & Accelerating Renewal Cycles
- 5.2.5 Modular Upfitting Ecosystems Shortening Delivery Lead-Time
- 5.2.6 Subscription-Based VAAS Models Unlocking SME Adoption
- 5.3 Market Restraints
- 5.3.1 High Upfront Cost Of ELCVs Despite Falling Battery Prices
- 5.3.2 Charging Infrastructure Gaps Outside Depot Environments
- 5.3.3 Payload Penalties from Heavy Battery Packs
- 5.3.4 Tax-Policy Uncertainty on Double-Cab Pickups
- 5.4 Value / Supply-Chain Analysis
- 5.5 Regulatory Landscape
- 5.6 Technological Outlook
- 5.7 Porter's Five Forces
- 5.7.1 Threat of New Entrants
- 5.7.2 Bargaining Power of Suppliers
- 5.7.3 Bargaining Power of Buyers
- 5.7.4 Threat of Substitutes
- 5.7.5 Competitive Rivalry
6 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 6.1 By Vehicle Type
- 6.1.1 Pick-up Trucks
- 6.1.2 Vans (Compact, Medium, Heavy)
- 6.2 By Propulsion Type
- 6.2.1 ICE
- 6.2.2 Hybrid
- 6.2.3 Battery-Electric
- 6.2.4 Fuel-Cell Electric
- 6.3 By Application
- 6.3.1 Commercial Delivery & Logistics
- 6.3.2 Industrial / Construction Support
- 6.3.3 Municipal & Public Services
- 6.4 By Ownership Model
- 6.4.1 Fleet-Owned
- 6.4.2 Leased
- 6.4.3 Subscription / VaaS
- 6.5 By Payload (GVW Class)
- 6.5.1 Less than or equal to 2.5 t
- 6.5.2 2.6 - 3.5 t
- 6.5.3 More than 3.5 t
- 6.6 By Geography
- 6.6.1 North America
- 6.6.1.1 United States
- 6.6.1.2 Canada
- 6.6.1.3 Rest of North America
- 6.6.2 South America
- 6.6.2.1 Brazil
- 6.6.2.2 Argentina
- 6.6.2.3 Rest of South America
- 6.6.3 Europe
- 6.6.3.1 Germany
- 6.6.3.2 France
- 6.6.3.3 United Kingdom
- 6.6.3.4 Spain
- 6.6.3.5 Italy
- 6.6.3.6 Russia
- 6.6.3.7 Rest of Europe
- 6.6.4 Asia Pacific
- 6.6.4.1 China
- 6.6.4.2 India
- 6.6.4.3 Japan
- 6.6.4.4 South Korea
- 6.6.4.5 Australia & New Zealand
- 6.6.4.6 Rest of Asia Pacific
- 6.6.5 Middle East and Africa
- 6.6.5.1 Saudi Arabia
- 6.6.5.2 United Arab Emirates
- 6.6.5.3 South Africa
- 6.6.5.4 Rest of Middle East and Africa
- 6.6.1 North America
7 Competitive Landscape
- 7.1 Market Concentration
- 7.2 Strategic Moves
- 7.3 Market Share Analysis
- 7.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 7.4.1 Ford Motor Company
- 7.4.2 Toyota Motor Corporation
- 7.4.3 Stellantis N.V.
- 7.4.4 Daimler AG (Mercedes-Benz Vans)
- 7.4.5 Renault Group
- 7.4.6 General Motors Company
- 7.4.7 Volkswagen AG
- 7.4.8 Nissan Motor Co. Ltd.
- 7.4.9 Hyundai Motor Company
- 7.4.10 Tata Motors Limited
- 7.4.11 Mahindra & Mahindra Limited
- 7.4.12 Isuzu Motors Limited
- 7.4.13 BYD Auto Co. Ltd.
- 7.4.14 Dongfeng Motor Corporation
- 7.4.15 Ashok Leyland Limited
- 7.4.16 Volvo Group
- 7.4.17 Rivian Automotive Inc.
- 7.4.18 BAIC Motor Corporation Ltd.
- 7.4.19 Gaz Group
- 7.4.20 Iveco Group N.V.
8 Market Opportunities & Future Outlook
- 8.1 White-space & Unmet-Need Assessment
9 Key Strategic Questions for CEOs

