PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125667

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125667
Industrial Furnace - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the industrial furnace market size is expected to grow from USD 12.93 billion in 2025 to USD 13.54 billion in 2026 and is forecast to reach USD 17.01 billion by 2031 at 4.68% CAGR over 2026-2031.
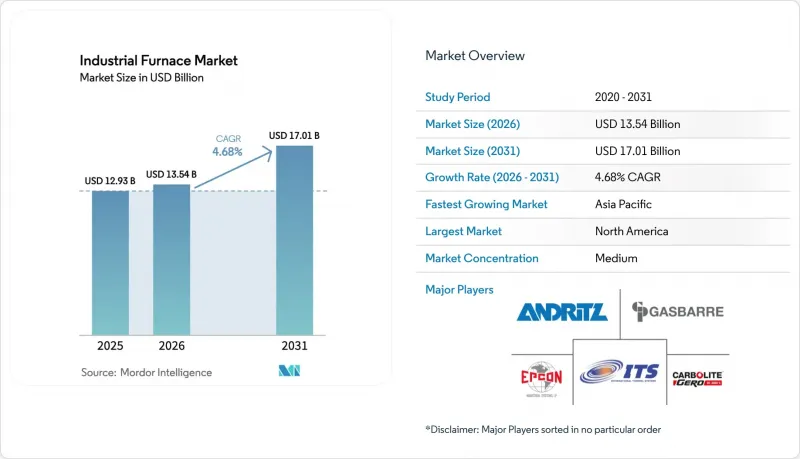
This report is Segmented by Furnace Type (Gas/Fuel Roller Hearth, Electric Roller Hearth, and More), Arrangement/Format (Box/Chamber/Muffle, Tube/Clamshell, and More), Heating Method (Combustion-Fired, Resistance Electric, and More), Temperature Range (Below 1000°C, and More), End-User Industry (Chemicals, Metal and Mining, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Furnace Market Trends and Insights
Surging Demand for Heat-Treatment in Automotive Manufacturing
The pivot to electric vehicle production is reshaping thermal-processing requirements across global assembly plants. Battery housings, traction-motor cores, and lightweight body structures need heat-treatment profiles that minimize distortion and support tighter tolerances. Automakers therefore specify furnaces with rapid quench rates, inert atmospheres, and closed-loop controls that document every cycle for ISO 26262 compliance. Suppliers integrating predictive-maintenance analytics achieve higher uptime, reducing total cost of ownership and strengthening competitive bids for long-term sourcing contracts.
Rising Investments in Metal and Mining Capacity Expansion
Steel and non-ferrous producers in China, India, and the Gulf Cooperation Council are building or revamping assets to meet infrastructure and energy-transition spending. Policies encouraging electric-arc furnaces (EAFs) over legacy blast furnaces drive replacement demand, while lower-grade ore processing boosts the need for furnaces with advanced refractory linings and oxygen-rich atmospheres that preserve throughput yet cut energy use. Modular plants allow operators to stagger capital outlays and match future commodity cycles.
High Capital and Running Costs for> 1,500 °C Installations
Extreme-temperature furnaces cost upward of USD 10 million to install and consume 15-20% of plant operating budgets. Advanced refractories, custom alloys, and enhanced safety systems inflate upfront investment, while a global shortage of technicians specialized in ultra-high-temperature operations raises labor costs. Insurance premiums and stringent permitting add further overhead, extending payback periods and deterring adoption in smaller firms.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated Adoption of Electric Furnaces for Decarbonization Mandates
- Stringent Energy-Efficiency Norms Driving Furnace Retrofits
- Volatility in Natural Gas and Electricity Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hydrogen-ready designs form the fastest-moving segment with a 6.59% CAGR to 2031 as policy frameworks in Europe and Japan stipulate carbon-neutral process heat. Gas/fuel roller hearth equipment nonetheless retained 44.10% of the industrial furnace market share in 2025, favored for reliability and existing infrastructure. Hybrid burners allowing incremental hydrogen substitution widen user options, ensuring legacy assets remain productive throughout the transition.
Wider adoption of electric roller hearth furnaces in renewable-rich regions encourages OEMs to co-develop high-power transformers and sophisticated magnetic-field controls that reduce energy loss. Induction units remain the tool of choice for niche metallurgical applications requiring rapid heating and fine temperature gradients, whereas solar furnaces occupy a nascent but promising niche in high-irradiance zones willing to leverage concentrated solar power for specialty ceramics.
Box/chamber/muffle configurations delivered 37.45% of the industrial furnace market size in 2025 by serving batch processes across metals, machinery, and ceramics. Tube/clamshell systems are recording a 6.51% CAGR as producers switch to continuous-flow layouts that minimize dwell time and energy consumption. Car-bottom and bottom-loading designs retain importance in heavy-equipment production where oversized castings demand robust material-handling solutions.
Vacuum and controlled-atmosphere units capture rising share in aerospace and semiconductor back-end processing, reflecting chain-of-custody requirements for contamination-free surfaces. The industrial furnace industry now emphasizes plug-and-play skids that scale production without lengthy site work, aligning with lean manufacturing philosophies and reduced capital-risk appetites among mid-tier suppliers.
Complete Report Scope:
- By Furnace Type
- Gas/Fuel Roller Hearth Furnace
- Electric Roller Hearth Furnace
- Induction Furnace
- Hydrogen-ready Furnace
- Solar Furnace
- By Arrangement / Format
- Box/Chamber/Muffle Furnace
- Tube/Clamshell Furnace
- Bottom Loading/Car Bottom Loading Furnace
- Top Loading Furnace
- Vacuum/Atmosphere/Heat-Treatment Furnace
- By Heating Method
- Combustion-Fired
- Resistance Electric
- Induction Electric
- Hybrid (Gas plus Electric)
- By Temperature Range
- Below 1 000 °C
- 1 000 - 1 500 °C
- Above 1 500 °C
- By End-user Industry
- Chemicals
- Metal and Mining
- Automotive Manufacturing
- Construction Machinery
- Aerospace
- Electronics and Semiconductors
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Singapore
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America contributed 35.10% of the industrial furnace market size in 2025, driven by strong heat-treatment orders from U.S. automotive and aerospace hubs and compliance with updated Department of Energy standards. Expansion projects such as Nucor's USD 3.0 billion EAF program and Canadian mining investments elevate baseline demand for high-capacity units. Skilled technical labor supports after-sales service revenue, though price volatility in natural gas and electricity remains a management priority.
Asia-Pacific records the quickest 6.24% CAGR, thanks to China's steel sector modernization that replaces outdated blast furnaces with EAFs and India's Production-Linked Incentive scheme that pulls forward capital spending on machinery and electronics capacity. Japan pioneers hydrogen-ready metallurgy, allocating JPY 329.4 billion to furnace upgrades that align with 2035 climate goals. South Korea, Singapore, and Australia round out regional growth by boosting semiconductor back-end and mineral-processing lines.
Europe sustains mid-single-digit growth anchored in climate policy compliance. Germany funnels public research grants toward hydrogen burners, while Italy modernizes heat-treatment fleets for specialty steel and automotive supply chains. The Carbon Border Adjustment Mechanism incentivizes furnace retrofits that cut Scope-1 emissions, and the Industrial Emissions Directive mandates best-available-technology upgrades in refractory, control systems, and waste-heat recovery. Eastern European markets, particularly Poland and Czechia, attract green-field investments in battery-component plants equipped with low-carbon furnaces.
- Andritz AG
- Carbolite Gero Limited
- Epcon Industrial Systems LP
- Gasbarre Products Inc.
- International Thermal Systems LLC
- Ipsen International GmbH
- Nutec Industries S.A. de C.V. (Nutec Bickley)
- Seco/Warwick S.A.
- Thermcraft Inc.
- Nabertherm GmbH
- Elino Industrie-Ofenbau GmbH
- CAN-ENG Furnaces International Ltd.
- Inductotherm Corp.
- Despatch Industries LLC
- Surface Combustion Inc.
- Lenton Furnaces and Ovens Ltd.
- Keith Company Inc.
- Dowa Thermotech Co., Ltd.
- CM Furnaces Inc.
- SOLO Swiss Group SA
- Tenova S.p.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for heat-treatment in automotive manufacturing
- 4.2.2 Rising investments in metal and mining capacity expansion
- 4.2.3 Accelerated adoption of electric furnaces for decarbonisation mandates
- 4.2.4 Stringent energy-efficiency norms driving furnace retrofits
- 4.2.5 Shift towards hydrogen-ready furnace designs in Europe and Japan
- 4.2.6 Micro-scale modular furnaces enabling distributed manufacturing
- 4.3 Market Restraints
- 4.3.1 High capital and running costs for >1500 °C installations
- 4.3.2 Volatility in natural gas and electricity prices
- 4.3.3 Skilled-operator shortage for complex heat-treat processes
- 4.3.4 Regulatory uncertainty on future carbon-pricing schemes
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Furnace Type
- 5.1.1 Gas/Fuel Roller Hearth Furnace
- 5.1.2 Electric Roller Hearth Furnace
- 5.1.3 Induction Furnace
- 5.1.4 Hydrogen-ready Furnace
- 5.1.5 Solar Furnace
- 5.2 By Arrangement / Format
- 5.2.1 Box/Chamber/Muffle Furnace
- 5.2.2 Tube/Clamshell Furnace
- 5.2.3 Bottom Loading/Car Bottom Loading Furnace
- 5.2.4 Top Loading Furnace
- 5.2.5 Vacuum/Atmosphere/Heat-Treatment Furnace
- 5.3 By Heating Method
- 5.3.1 Combustion-Fired
- 5.3.2 Resistance Electric
- 5.3.3 Induction Electric
- 5.3.4 Hybrid (Gas plus Electric)
- 5.4 By Temperature Range
- 5.4.1 Below 1 000 °C
- 5.4.2 1 000 - 1 500 °C
- 5.4.3 Above 1 500 °C
- 5.5 By End-user Industry
- 5.5.1 Chemicals
- 5.5.2 Metal and Mining
- 5.5.3 Automotive Manufacturing
- 5.5.4 Construction Machinery
- 5.5.5 Aerospace
- 5.5.6 Electronics and Semiconductors
- 5.5.7 Other End-user Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Singapore
- 5.6.4.6 Australia
- 5.6.4.7 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Egypt
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Andritz AG
- 6.4.2 Carbolite Gero Limited
- 6.4.3 Epcon Industrial Systems LP
- 6.4.4 Gasbarre Products Inc.
- 6.4.5 International Thermal Systems LLC
- 6.4.6 Ipsen International GmbH
- 6.4.7 Nutec Industries S.A. de C.V. (Nutec Bickley)
- 6.4.8 Seco/Warwick S.A.
- 6.4.9 Thermcraft Inc.
- 6.4.10 Nabertherm GmbH
- 6.4.11 Elino Industrie-Ofenbau GmbH
- 6.4.12 CAN-ENG Furnaces International Ltd.
- 6.4.13 Inductotherm Corp.
- 6.4.14 Despatch Industries LLC
- 6.4.15 Surface Combustion Inc.
- 6.4.16 Lenton Furnaces and Ovens Ltd.
- 6.4.17 Keith Company Inc.
- 6.4.18 Dowa Thermotech Co., Ltd.
- 6.4.19 CM Furnaces Inc.
- 6.4.20 SOLO Swiss Group SA
- 6.4.21 Tenova S.p.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

