PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125716

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125716
India IT Hardware - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, India IT hardware market size in 2026 is estimated at USD 22.61 billion, growing from 2025 value of USD 21.17 billion with 2031 projections showing USD 31.39 billion, growing at 6.78% CAGR over 2026-2031.
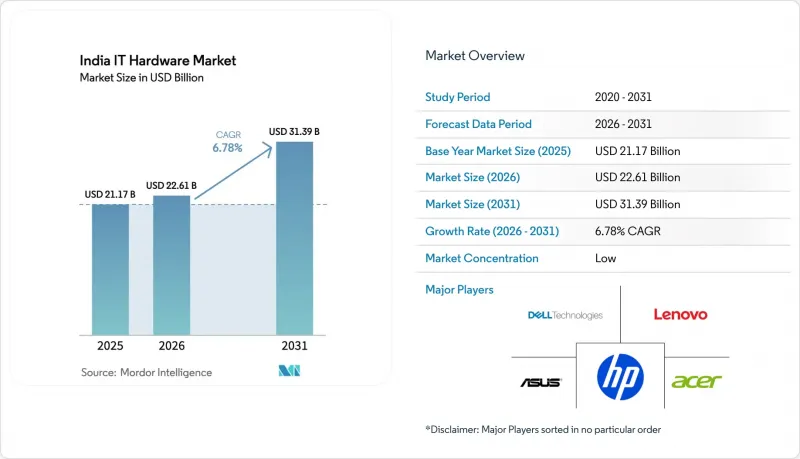
This report is Segmented by Product Type (PCs and Workstations, Enterprise Networking Hardware, Enterprise Storage Devices, and More), End-User Industry (Consumer, and Enterprise), Industry (BFSI, Retail, IT and Telecom, and Other End-User Industries), and Geography (North India, East India, West and Central India, and South India). The Market Forecasts are Provided in Terms of Value (USD).
India IT Hardware Market Trends and Insights
Elevated Need for High-Performance Computing in AI Workloads
Enterprise AI projects require 3-5 times more compute capacity than traditional applications, pushing firms to specify accelerators, advanced memory, and liquid cooling even for mid-range racks. Dell Technologies projects USD 15 billion in AI server revenue in fiscal 2025, up from USD 10 billion a year earlier. Ola's partnership with Lenovo to build Krutrim 3, a 700-billion-parameter model, necessitates India's largest supercomputer and an initial INR 2,000 crore (USD 240 million) hardware outlay. Such flagship deployments set procurement baselines that ripple into Tier-2 enterprises, increasing the India IT Hardware market's average selling price and shifting vendor roadmaps toward purpose-built AI nodes.
Make-in-India Incentives for Local PC/Server Manufacturing (PLI 2.0)
The PLI framework offers 4-6% incremental incentive on net incremental sales of locally manufactured PCs and servers, encouraging global OEMs to relocate higher-value assembly lines. Dixon Technologies invested USD 115 million in Tamil Nadu to manufacture HP notebooks, with output slated at 2 million laptops annually. Lenovo targets 100% local PC production and plans to assemble AI servers domestically, cutting a USD 10.1 billion laptop import bill that previously constrained foreign-exchange reserves. Early localization also seeds ancillary component ecosystems. Foxconn has committed USD 1 billion for display module assembly in Tamil Nadu, reducing dependence on East Asian imports.
Semiconductor Supply-Chain Volatility
India still imports 65-70% of its semiconductors, exposing manufacturers to volatile DRAM and NAND pricing that rose 15-20% over 2024-25. Local fabrication will not ship commercial wafers until Tata-PSMC's Gujarat fab comes online in late 2025, prompting OEMs to hold larger safety stocks and hedge currency in component sourcing. High-performance GPUs remain the tightest node, stretching lead times to 52-60 weeks and stalling AI server rollouts. The bottleneck inflates working capital needs and dampens margin profiles, carving 90 basis points off the projected India IT Hardware market CAGR.
Other drivers and restraints analyzed in the detailed report include:
- Public-Sector Digitization Push via Digital India and NIC Projects
- Rising Demand for Edge Data-Center Servers in Tier-2 Cities
- Escalating E-Waste Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Enterprise storage accounted for the fastest 8.08% CAGR through 2031 as enterprises deployed AI-optimized arrays and NVMe-over-Fabrics architectures. NetApp's hybrid-cloud revenue reached USD 5.66 billion in fiscal 2024, and its AIPod reference design became a blueprint for domestic data-center upgrades. Servers followed at 7.18% CAGR, fueled by edge deployments and public-sector demand. PCs and workstations maintained a 6.94% CAGR, buttressed by hybrid-work refreshes. The India IT Hardware market size for enterprise storage represented a significant share, while PCs retained 42.08% of the India IT Hardware market share. Printers and copiers trailed, reflecting digital document workflows and cloud forms adoption. Vendors integrated AI-inference accelerators inside notebooks to protect ASPs, signaling the convergence of client and server design philosophies.
The evolution also reshaped value chains. Component suppliers focusing on PCIe 5.0 controllers and CXL-ready DIMMs secured longer-term orders as hyperscalers demanded deterministic latency. Networking hardware pivoted toward software-defined overlays, cannibalizing traditional chassis switch revenues but opening opportunities in secure SD-WAN appliances tuned for branch edge. The shift enlarged the India IT Hardware market as consumption moved from capex purchases to hybrid device-plus-subscription bundles.
Complete Report Scope:
- By Product Type
- PCs and Workstations
- Enterprise Networking Hardware
- Enterprise Storage Devices
- Servers
- Other Hardware (Printers and Copiers)
- By Application
- Consumer
- Enterprise
- SMEs
- Large Enterprises
- By End-user Industry
- BFSI
- Retail
- IT and Telecom
- Other End-user Industries
- By Region
- North India
- East India
- West and Central India
- South India
List of Companies Covered in this Report:
- Dell Inc.
- Lenovo Group Ltd
- ASUS Tek Computer Inc.
- HP Inc.
- Acer Inc.
- IBM Corporation
- Apple Inc.
- Samsung Electronics Co. Ltd.
- NetApp Inc.
- Hitachi Ltd.
- Cisco Systems Inc.
- Juniper Networks Inc.
- Arista Networks Inc.
- Hewlett Packard Enterprise (HPE) Inc.
- Wistron India Inc.
- Foxconn India Inc.
- Super Micro Computer Inc.
- Dell EMC Indian Ops
- Supertron Electronics Inc.
- RP Tech India
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid growth in laptop demand under hybrid-work policies
- 4.2.2 Elevated need for high-performance computing in AI workloads
- 4.2.3 Public-sector digitization push via Digital India and NIC projects
- 4.2.4 Make-in-India incentives for local PC/server manufacturing (PLI 2.0)
- 4.2.5 Rising demand for edge data-centre servers in Tier-2 cities (under-reported)
- 4.2.6 Corporate ESG mandates favour energy-efficient hardware (under-reported)
- 4.3 Market Restraints
- 4.3.1 Escalating e-waste compliance costs
- 4.3.2 Semiconductor supply-chain volatility
- 4.3.3 Persistent grey-market imports in peripherals (under-reported)
- 4.3.4 Slow enterprise refresh cycles in public-sector tenders (under-reported)
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macro-economic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 PCs and Workstations
- 5.1.2 Enterprise Networking Hardware
- 5.1.3 Enterprise Storage Devices
- 5.1.4 Servers
- 5.1.5 Other Hardware (Printers and Copiers)
- 5.2 By Application
- 5.2.1 Consumer
- 5.2.2 Enterprise
- 5.2.2.1 SMEs
- 5.2.2.2 Large Enterprises
- 5.3 By End-user Industry
- 5.3.1 BFSI
- 5.3.2 Retail
- 5.3.3 IT and Telecom
- 5.3.4 Other End-user Industries
- 5.4 By Region
- 5.4.1 North India
- 5.4.2 East India
- 5.4.3 West and Central India
- 5.4.4 South India
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Dell Inc.
- 6.4.2 Lenovo Group Ltd
- 6.4.3 ASUS Tek Computer Inc.
- 6.4.4 HP Inc.
- 6.4.5 Acer Inc.
- 6.4.6 IBM Corporation
- 6.4.7 Apple Inc.
- 6.4.8 Samsung Electronics Co. Ltd.
- 6.4.9 NetApp Inc.
- 6.4.10 Hitachi Ltd.
- 6.4.11 Cisco Systems Inc.
- 6.4.12 Juniper Networks Inc.
- 6.4.13 Arista Networks Inc.
- 6.4.14 Hewlett Packard Enterprise (HPE) Inc.
- 6.4.15 Wistron India Inc.
- 6.4.16 Foxconn India Inc.
- 6.4.17 Super Micro Computer Inc.
- 6.4.18 Dell EMC Indian Ops
- 6.4.19 Supertron Electronics Inc.
- 6.4.20 RP Tech India
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

