PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154208

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154208
Polyphenylene Sulfide (PPS) Composite - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the polyphenylene sulfide (PPS) composite market size was valued at USD 2.93 billion in 2025 and is estimated to grow from USD 3.17 billion in 2026 to reach USD 4.67 billion by 2031, at a CAGR of 8.06% during the forecast period (2026-2031).
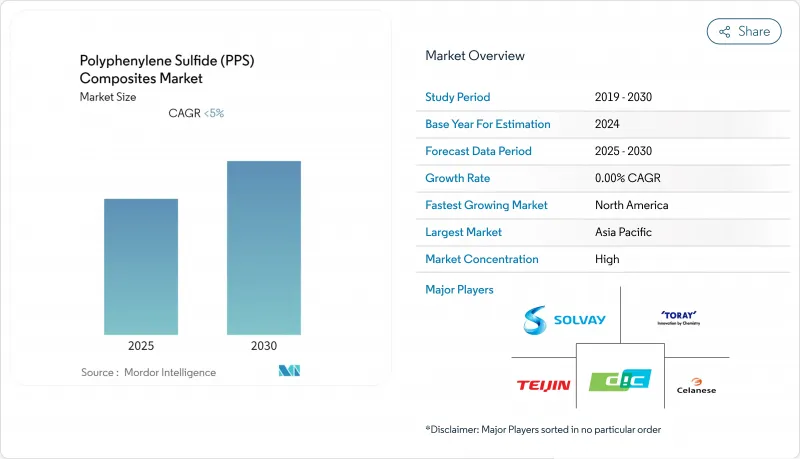
Global Polyphenylene Sulfide (PPS) Composite Market Trends and Insights
EV Battery Thermal Management Integration
Thermal management has become a major performance requirement in lithium-ion battery system design. PPS composites are used in coolant pump housings, thermostat bodies, and connector overmolds that operate at 180 °C to 260 °C while contacting water-glycol mixtures in tightly packaged battery systems. Envalior reported in May 2025 that its glass-fiber-reinforced Xytron G4080HR PPS grade showed minimal delamination after 3,000 hours in water-glycol coolant at 135 °C. Each battery pack requires multiple thermally stable polymer parts, including structural brackets, thermal barriers, electrical isolators, and cooling-system components, so that qualification decisions may affect several component families at once. This requirement increases PPS composite content per electric vehicle and supports automotive-grade glass fiber-reinforced composites in the polyphenylene sulfide (PPS) composite market.
Miniaturized High-Frequency Electronics
Fifth-generation (5G) millimeter-wave networks and artificial intelligence inference infrastructure require substrates and connectors with low dielectric loss, reliable signal transmission, and stable properties at high frequencies. PPS derivatives can deliver dielectric constants below 3.0 and dissipation factors below 0.003 at frequencies of 10 gigahertz and above. A 2025 Communications Materials study reported a dissipation factor of 0.00087 at 10 gigahertz and a dielectric constant of 2.80 for poly(2,6-dimethyl-1,4-phenylene sulfide). DIC CORPORATION and Unitika Ltd. announced a PPS film in October 2024 that was engineered to reduce transmission loss at millimeter-wave frequencies from 30 to 300 gigahertz. The material was being prepared for commercial production for next-generation communication devices and automotive radar, where the choice of substrate affects the usable performance window of the finished hardware.
High Material and Processing Cost
PPS composite processing requires melt temperatures above 300 °C and specialized compounding equipment. Stainless-steel or bimetallic barrel-and-screw assemblies are required because PPS can release sulfur compounds that corrode standard steel hardware. Chinese PPS compound prices ranged from USD 3.00 to USD 3.80 per kilogram, compared with USD 1.80 to USD 2.20 per kilogram for polyamide 66 with 30% glass fiber. Retrofitting a standard compounding line with corrosion-resistant tooling can require capital expenditure of millions of USD per line, which increases the cost of serving new or lower-volume programs. Cost-sensitive original equipment manufacturer programs continue to assess other materials where the required performance does not justify PPS processing costs.
Other drivers and restraints analyzed in the detailed report include:
- Metal Replacement and Part Consolidation
- High-Temperature Filtration Upgrades
- Competition from High-Temperature Polyamides
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Glass fiber-reinforced composites held 58.45% of the polyphenylene sulfide (PPS) composite market share in 2025, supported by established processing practices in automotive, electrical, and industrial filtration applications. Glass fiber loading of 30% to 40% enables heat-deflection temperatures close to 260 °C and helps components retain dimensional stability during coolant or chemical exposure. These grades remain a practical choice for high-volume injection-molded parts because established tooling and material specifications reduce the time needed to introduce a qualified component. They are used in cooling systems, electrical connectors, pump bodies, and other components that require heat resistance with manageable material cost. The broad application base supports continued demand for this type across established end uses and gives suppliers a durable base for grade development.
Carbon fiber-reinforced composites are projected to advance at an 8.75% CAGR through 2031, supported by aerospace qualification activity and demand for lightweight electric vehicle battery enclosures. Continuous carbon fiber PPS composites can be welded, thermoformed, and recycled, unlike thermoset carbon-epoxy materials. This processing flexibility supports manufacturers that are seeking to reduce part counts and production waste without giving up the stiffness required for structural or semi-structural components. It also enables applications that require high stiffness with lower component weight, which broadens the role of continuous-fiber formats in the polyphenylene sulfide (PPS) composite market.
Complete Report Scope:
- By Type
- Glass Fiber-reinforced Composites
- Carbon Fiber-reinforced Composites
- Other Types
- By Form
- Molding Compounds
- Films
- Sheets and Plates
- Other Forms
- By End-user Industry
- Automotive
- Aerospace and Defense
- Industrial (Oil and Gas)
- Electrical and Electronics
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 62.87% of the polyphenylene sulfide (PPS) composite market share in 2025 and is projected to advance at a 9.21% CAGR through 2031. China has the largest electric vehicle production base and uses PPS composite thermal barriers, structural brackets, and coolant-system connectors in battery packs. The region combines resin production, compounding capacity, and end-use manufacturing, which shortens supply paths between material qualification and component production. Japan and South Korea remain important sources of high-grade PPS resin through multi-plant systems operated by TORAY INDUSTRIES, INC., DIC CORPORATION, KUREHA CORPORATION, and SK chemicals. This regional production base reinforces Asia-Pacific's role in the polyphenylene sulfide (PPS) composite market.
China's expanding capacity is increasing import substitution in mid-grade automotive and industrial composites. NHU PM is targeting a total PPS production of 30,000 metric tons per year through its Phase IV project. Dongtai Qixin began construction of an 80,000-metric-tons-per-year PPS resin project in Huangshan, Anhui Province, in August 2025. The project had a Phase I investment of CNY 1.6 billion (approximately USD 220 million). This capacity expansion is raising competitive pressure on Japanese and Korean producers in downstream applications.
North America's demand is supported by aerospace and defense procurement, automotive thermal management, and industrial filtration. Syensqo expanded its Ryton PPS compounding capability in Augusta, Georgia, in May 2025 at an International Automotive Task Force 16949-certified site. Europe benefits from automotive electrification in Germany and France, and aerospace composites in the United Kingdom and France. South America and the Middle East and Africa are projected to remain modest contributors through 2031, although Saudi Arabia's energy investment supports demand for refinery and desalination components.
- Avient Corporation
- Celanese Corporation
- DIC CORPORATION
- Ensinger
- IDEMITSU FINE COMPOSITES CO., LTD.
- KUREHA CORPORATION
- LG Chem
- NHU PM
- RTP Company
- SABIC
- SK chemicals
- Solvay
- TEIJIN LIMITED
- TORAY INDUSTRIES, INC.
- Tosoh Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EV Battery Thermal Management Integration
- 4.2.2 Miniaturized High-Frequency Electronics
- 4.2.3 Metal Replacement and Part Consolidation
- 4.2.4 High-Temperature Filtration Upgrades
- 4.2.5 Hydrogen Fuel-Cell Balance-of-Plant Adoption
- 4.3 Market Restraints
- 4.3.1 High Material and Processing Cost
- 4.3.2 Competition from High-Temperature Polyamides
- 4.3.3 Corrosion-Sensitive Processing Equipment
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Glass Fiber-reinforced Composites
- 5.1.2 Carbon Fiber-reinforced Composites
- 5.1.3 Other Types
- 5.2 By Form
- 5.2.1 Molding Compounds
- 5.2.2 Films
- 5.2.3 Sheets and Plates
- 5.2.4 Other Forms
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Aerospace and Defense
- 5.3.3 Industrial (Oil and Gas)
- 5.3.4 Electrical and Electronics
- 5.3.5 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Avient Corporation
- 6.4.2 Celanese Corporation
- 6.4.3 DIC CORPORATION
- 6.4.4 Ensinger
- 6.4.5 IDEMITSU FINE COMPOSITES CO., LTD.
- 6.4.6 KUREHA CORPORATION
- 6.4.7 LG Chem
- 6.4.8 NHU PM
- 6.4.9 RTP Company
- 6.4.10 SABIC
- 6.4.11 SK chemicals
- 6.4.12 Solvay
- 6.4.13 TEIJIN LIMITED
- 6.4.14 TORAY INDUSTRIES, INC.
- 6.4.15 Tosoh Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

