PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154247

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154247
Feed Flavors, Sweeteners, and Natural Enhancers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
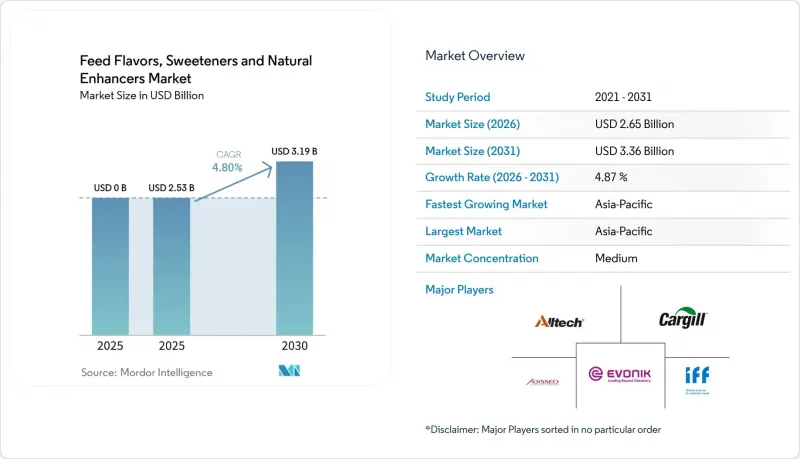
According to Mordor Intelligence, the feed flavors, sweeteners, and natural enhancers market size was valued at USD 2.53 billion in 2025 and is projected to reach USD 2.65 billion in 2026 and USD 3.36 billion by 2031, growing at a CAGR of 4.87% from 2026 to 2031.
Global Feed Flavors, Sweeteners, and Natural Enhancers Market Trends and Insights
Rising Demand for Animal Protein
Demand for animal protein remains a durable source of demand for the feed flavors, sweeteners, and natural enhancers market, supported by population growth, rising household incomes, urbanization, and dietary shifts toward higher-protein foods. These trends are particularly pronounced in developing Asian economies, where improving purchasing power is increasing the consumption of meat, poultry, and other animal-based foods. Global meat production is projected to increase by 13%, or 46 million metric tons, to 406 million metric tons by 2034, with Asia accounting for 55% of this growth, further supporting demand for commercial animal feed and associated feed flavor, sweetener, and natural enhancer products. Higher output requires greater use of standardized compound feed rather than farm-mixed rations. These feeds often contain tighter amino acid balances, added minerals, and premixes that can reduce voluntary intake when their sensory profile is not controlled. The feed flavors, sweeteners, and natural enhancers market benefits because feed producers need additives that limit unpleasant notes without disrupting nutritional specifications. Suppliers are also offering flavor and sweetener combinations that support intake and complement gut health formulations.
Higher Feed Intake and Performance Requirements
Commercial livestock operators are focusing more closely on feed conversion ratio (FCR), as energy and protein costs remain significant operating expenses. A 2025 review reported that sweeteners increased feed intake by 18% to 26% in weaning-phase swine, supporting early growth and reducing the post-weaning intake decline. Poultry producers seeking an FCR below 1.7 also value more uniform feed intake, as it can reduce downgrading at slaughter. Flavor supplementation is being used by large dairy operations in India and the Middle East, where heat stress reduces dry matter intake during lactation. These conditions move palatability from a discretionary formulation choice toward a more regular part of feed design. This supports demand in the feed flavors, sweeteners, and natural enhancers market for ingredients that work across different species and production settings.
High Cost of Natural and Encapsulated Additives
Natural botanical extracts and microencapsulated products carry a 40% to 60% price premium over standard synthetic grades. This premium limits adoption in markets where compound feed margins are under pressure from commodity price volatility. Liquid encapsulated products can require cold-chain and moisture-control systems, adding 8% to 12% to landed costs in some cases. The economic case can be particularly difficult in tropical markets where farm-level budgets remain tight. Suppliers are developing partly synthetic and natural blends to provide a more accessible option. These products can improve price competitiveness, although they may not meet all requirements for premium antibiotic-free certification.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Antibiotic-Free and Natural Production Systems
- Intensification of Aquaculture and Young-Animal Feeding
- Limited Awareness and Technical Service in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Flavors were the largest product type, accounting for 37.4% of the feed flavors, sweeteners, and natural enhancers market share in 2025. Their leading position is supported by their broad application across major animal species and feed stages, including dairy cattle transition diets, broiler starter diets, swine feed, and aquafeed. Flavors address multiple sensory challenges by improving aroma, masking undesirable off-notes, and supporting feed acceptance when animals experience dietary changes, stress, or exposure to less-palatable ingredients. This broad functionality allows flavors to be incorporated across a wider range of commercial feed formulations than products used for more specific sensory requirements, supporting their larger overall demand base. Natural enhancers, including botanical extracts, yeast-derived compounds, and fermentation-based palatants, are increasingly used for additional functional benefits related to oxidative stress, immune response, and microbial balance. Suppliers are also combining flavor and natural-enhancer functionalities into integrated sensory solutions, further expanding the role of flavors within premium feed-additive formulations.
Sweeteners are forecast to be the fastest-growing product type, growing at a CAGR of 5.6% from 2026 to 2031. Their strongest uses are in swine nursery diets and aquafeed starter rations, where early feed intake can affect later feed conversion ratio (FCR) performance. Saccharin, neohesperidin dihydrochalcone, and plant-derived steviol glycosides are being evaluated across species. Stevia-based options have appeal in antibiotic-free systems that value naturally positioned ingredients. Large swine operators in China, Germany, and Brazil use intake support as a direct production lever during the weaning period. Across product types, compound feed manufacturers are seeking multi-component solutions that reduce formulation complexity and simplify supplier management. This preference is reshaping purchasing priorities in the feed flavors, sweeteners, and natural enhancers market.
Complete Report Scope:
- By Product Type
- Flavors
- Sweeteners
- Natural Enhancers
- By Source
- Natural
- Synthetic
- By Animal Type
- Ruminants
- Beef Cattle
- Dairy Cattle
- Other Ruminants
- Swine
- Poultry
- Aquaculture
- Pets
- Ruminants
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific was the largest regional segment, with a 33.6% share of the feed flavors, sweeteners, and natural enhancers market in 2025. It was also the fastest-growing region and is forecast to grow at a CAGR of 8.4% from 2026 to 2031. China is the main regional market, supported by large swine and poultry production systems, and it is forecast to produce 17.3 million metric tons of chicken meat in 2026, 5% more than in 2025. India, Vietnam, Thailand, and Indonesia add demand as meat consumption rises, smallholder operations become more commercial, and aquaculture producers increase fishmeal substitution. Japan and Australia remain mature markets for premium natural enhancers and encapsulated systems within the feed flavors, sweeteners, and natural enhancers market.
North America is a technology-intensive area for the feed flavors, sweeteners, and natural enhancers market, supported by pet food, specialty aquaculture, and antibiotic-free pork and poultry production. The United States has a mature compound-feed infrastructure and a developed pet food sector that uses tightly specified flavors and palatants. Canada emphasizes feed safety, livestock productivity, and quality-assured production, while Mexico uses integrated poultry and swine networks that link closely to suppliers in the United States. Europe is shaped by Regulation (EC) No. 1831/2003, sustainability requirements, and advanced antibiotic-free production practices, which support demand for traceable botanical extracts.
South America is supported by Brazil's large compound-feed sector and cattle herd, which exceeded 54,500 thousand head in 2024. Ruminant and swine diets provide the region's principal volume demand, including applications in total mixed ration (TMR) and grow-finish feeding. The Middle East is expanding domestic livestock and aquaculture systems as part of food security planning. Saudi Arabia and the United Arab Emirates are important examples of technically managed production environments that need specialty additives. Africa remains less developed in commercial feed adoption, though South Africa and Egypt indicate how demand may evolve as urbanization, income growth, and commercial feed use continue.
- Evonik Industries AG
- Cargill, Incorporated
- Alltech, Inc.
- Adisseo France SAS
- Kerry Group plc
- Archer Daniels Midland Company
- DSM-Firmenich AG
- Kemin Industries, Inc.
- Symrise AG
- Nutreco N.V. (SHV Holdings N.V.)
- Associated British Foods plc
- BASF SE
- BioMar Group A/S (Aktieselskabet Schouw and Co.)
- Novus International, Inc. (Mitsui and Company, Ltd. and Nippon Soda Co., Ltd.)
- International Flavors and Fragrances Inc. (IFF)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for animal protein
- 4.2.2 Higher feed intake and performance requirements
- 4.2.3 Growth of antibiotic-free and natural production systems
- 4.2.4 Intensification of aquaculture and young-animal feeding
- 4.2.5 Heat-stable encapsulation and precision sensory formulation
- 4.2.6 Formulation complexity from alternative protein and circular feed ingredients
- 4.3 Market Restraints
- 4.3.1 High cost of natural and encapsulated additives
- 4.3.2 Limited awareness and technical service in emerging markets
- 4.3.3 Inconsistent raw-material sensory profiles
- 4.3.4 Species-specific regulatory and labeling constraints
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.5.1 Encapsulation and Controlled Release
- 4.5.2 Natural Extract and Botanical Standardization
- 4.5.3 Digital Feed Formulation and Intake Monitoring
- 4.5.4 Sensory Testing and Species-Specific Screening
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE and VOLUME)
- 5.1 By Product Type
- 5.1.1 Flavors
- 5.1.2 Sweeteners
- 5.1.3 Natural Enhancers
- 5.2 By Source
- 5.2.1 Natural
- 5.2.2 Synthetic
- 5.3 By Animal Type
- 5.3.1 Ruminants
- 5.3.1.1 Beef Cattle
- 5.3.1.2 Dairy Cattle
- 5.3.1.3 Other Ruminants
- 5.3.2 Swine
- 5.3.3 Poultry
- 5.3.4 Aquaculture
- 5.3.5 Pets
- 5.3.1 Ruminants
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.1.4 Rest of North America
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 Australia
- 5.4.4.5 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Turkey
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Business Segments, Financials, Key Information, Market Rank, Market Share, Products and Services, and Analysis of Recent Developments).
- 6.4.1 Evonik Industries AG
- 6.4.2 Cargill, Incorporated
- 6.4.3 Alltech, Inc.
- 6.4.4 Adisseo France SAS
- 6.4.5 Kerry Group plc
- 6.4.6 Archer Daniels Midland Company
- 6.4.7 DSM-Firmenich AG
- 6.4.8 Kemin Industries, Inc.
- 6.4.9 Symrise AG
- 6.4.10 Nutreco N.V. (SHV Holdings N.V.)
- 6.4.11 Associated British Foods plc
- 6.4.12 BASF SE
- 6.4.13 BioMar Group A/S (Aktieselskabet Schouw and Co.)
- 6.4.14 Novus International, Inc. (Mitsui and Company, Ltd. and Nippon Soda Co., Ltd.)
- 6.4.15 International Flavors and Fragrances Inc. (IFF)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

