PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154252

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154252
Biometric Vehicle Access System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
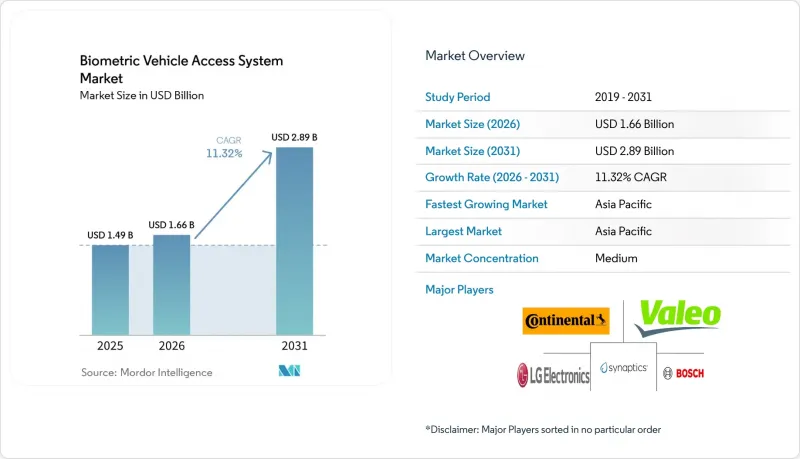
According to Mordor Intelligence, the biometric vehicle access system market size was valued at USD 1.49 billion in 2025 and is estimated to grow from USD 1.66 billion in 2026 to reach USD 2.89 billion by 2031, at a CAGR of 11.32% during the forecast period (2026-2031).
Global Biometric Vehicle Access System Market Trends and Insights
Ubiquity of Smartphone-Class Fingerprint Sensors in Mid-Price Cars
The democratization of capacitive fingerprint sensors from premium smartphones to mid-market vehicles accelerates biometric adoption across price segments previously dominated by traditional key systems. Infineon's October 2024 launch of automotive-qualified fingerprint sensor ICs (CYFP10020A00 and CYFP10020S00) operating over -40°C to +105°C demonstrates the technical maturation required for mass-market deployment . These sensors integrate with existing microcontroller architectures while providing trackpad functionality, reducing implementation complexity for OEMs targeting cost-sensitive segments. Mid-price passenger cars are integrating capacitive fingerprint sensors originally developed for smartphones, lowering per-unit costs to below USD 5 and enabling OEMs to offer biometric access in vehicles priced under USD 30,000.
OEM Push for Password-Free In-Car Payments
Automakers are embedding biometric authentication to enable frictionless in-car payments for fuel, tolls, parking, and digital services, eliminating the need for users to enter passwords or retrieve payment cards while driving. Mercedes-Benz launched the Mercedes me Fuel & Pay system in partnership with Visa, allowing drivers to authorize fuel purchases via fingerprint authentication integrated into the vehicle's infotainment system. FORVIA's biometric authentication solution, developed with Smart Eye and demonstrated in April 2025, enables secure payments and app access across a catalog of more than 200 applications integrated into 32 car brands from 13 OEMs, positioning biometric access as the gateway to recurring software revenue.
Cold-Weather Reliability Issues for Low-Cost Fingerprint Readers
Capacitive fingerprint sensors deployed in vehicle door handles and start buttons experience degraded performance in cold climates, where skin conductance drops 30% to 50% and sensor drift increases due to thermal contraction of materials and battery voltage sag. A Carleton University study found a weak correlation between ambient temperature and fingerprint recognition accuracy in controlled laboratory conditions. Yet, real-world user complaints on Mercedes EQE owner forums documented repeated authentication failures when temperatures fell below -10°C, forcing drivers to revert to backup key fobs.
Other drivers and restraints analyzed in the detailed report include:
- ISO/SAE 21434 Cybersecurity Mandates (2025)
- Tier-1 Suppliers' "Biometrics-as-a-Service" Revenue Models
- Data-Privacy Litigation Risk Under GDPR and CCPA
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, fingerprint recognition holds a 45.23% market share, reflecting the industry's progression toward enhanced security measures for premium applications. Iris recognition is the fastest-growing authentication segment, with a 27.58% CAGR projected through 2031. This growth disparity highlights a market division: mainstream vehicles adopt cost-efficient fingerprint solutions, while luxury and commercial applications prefer advanced multimodal systems, justified by higher security implementation costs. Face and voice recognition segments, though smaller, remain strategically significant, particularly in hands-free operations and integration with infotainment systems. The premium segment increasingly features multimodal and multi-factor authentication (MFA) systems, combining biometric modalities to ensure security for high-value transactions and to meet regulatory compliance requirements.
Continental's CES 2025 presentation of invisible biometric sensing displays demonstrates the industry's movement toward integrated multimodal systems. By combining facial recognition with vital sign monitoring, these systems provide comprehensive authentication and safety solutions. Such integrations address the limitations of single-modality systems while offering additional functionalities that support premium pricing. This segmentation aligns with the automotive industry's transition to software-defined vehicles, where biometric capabilities can be updated through over-the-air updates, enabling OEMs to introduce new authentication methods without hardware modifications.
In 2025, passenger cars accounted for 63.14% of the market, highlighting fleet operators' focus on security, regulatory compliance, and operational efficiency over cost concerns. Commercial vehicles represented the fastest-growing segment, with a 21.43% CAGR. The FMCSA's planned implementation of biometric identity verification for trucking registrations in 2025 is expected to drive mandatory adoption, accelerating biometric deployment in commercial vehicles ahead of consumer applications. Fleet applications benefit from centralized procurement and higher vehicle utilization, resulting in better returns on biometric system investments compared to personal vehicles. Commercial vehicle biometric systems are often integrated with fleet management platforms, providing operators with access control, driver monitoring, and compliance reporting capabilities beyond basic vehicle access.
The growth of the commercial vehicle segment suggests potential technology transfer to passenger vehicles as biometric systems mature and production volumes reduce costs. Bosch's Fleet Management Xtended Access system illustrates how commercial applications foster innovation in areas such as remote access management and multi-vehicle authentication, which subsequently influence consumer vehicle development. This transfer pattern indicates that commercial vehicles serve as testing grounds for biometric advancements that eventually reach passenger car applications.
Complete Report Scope:
- By Authentication Type
- Fingerprint Recognition
- Face Recognition
- Iris Recognition
- Voice Recognition
- Multimodal/MFA
- By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- By Component
- Hardware
- Software/AI Stack
- By Sales Channel
- OEM Factory-Fit
- Aftermarket/Retrofit
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific leads both market share at 30.47% in 2025 and growth rate at 18.61% CAGR through 2031, driven by Chinese automakers' aggressive biometric integration and supportive government policies for intelligent vehicle development. Government roadmaps for intelligent connected vehicles emphasize multimodal driver identification as a foundational component. Supplier orders increase when local authorities include this feature in Level 3 autonomy scoring. Taiwan's Lextar has commenced volume production of VCSELs in accordance with AEC Q102 standards, ensuring a stable supply for domestic and export markets. This reduces costs and promotes higher adoption rates.
North America ranks second in revenue, supported by regulations that require biometric validation for commercial motor carrier license renewals. This has spurred fleet retrofit programs. Detroit OEMs are pursuing subscription-based revenue models centered on digital wallets, while US consumers increasingly adopt pay-at-pump facial recognition, driven by familiarity with smartphone experiences. Cold-weather reliability challenges limit adoption in regions like the Midwest and Canada until sensors can operate reliably at -30 °C.
Europe is advancing steadily, driven by ISO/SAE 21434 compliance and competition among premium German automakers. GDPR mandates local data storage with encryption, pushing architectures toward edge AI chips in driver-monitoring cameras. Tier-1 suppliers such as Bosch and Valeo emphasize privacy-by-design, transforming compliance costs into brand advantages. While volumes in Europe lag behind those in Asia, the region's average unit selling prices are the highest globally, as consumers demand seamless multi-factor authentication linked to digital key sharing.
- Continental AG
- Robert Bosch GmbH
- Denso Corporation
- Safran SA
- Valeo SA
- Fingerprint Cards AB
- Synaptics Inc.
- Fujitsu Ltd
- Hitachi Ltd
- Methode Electronics
- Nuance Communications
- Cerence Inc.
- Thales Group
- Gentex Corporation
- LG Electronics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Ubiquity of Smartphone-Class Fingerprint Sensors in Mid-Price Cars
- 4.2.2 OEM Push for Password-Free In-Car Payments
- 4.2.3 ISO/SAE 21434 Cybersecurity Mandates (2025)
- 4.2.4 Tier-1 Suppliers' "Biometrics-as-a-Service" Revenue Models
- 4.2.5 Multi-Factor, Multi-Modal Access Pilots in Robotaxis
- 4.2.6 Insurance Discounts for MFA Systems
- 4.3 Market Restraints
- 4.3.1 Cold-Weather Reliability Issues for Low-Cost Fingerprint Readers
- 4.3.2 Data-Privacy Litigation Risk Under GDPR and CCPA
- 4.3.3 Lack of Global Spoof-Testing Standards
- 4.3.4 Supply-Chain Exposure to VCSEL Shortages
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Customers
- 4.7.3 Threat of New Entrants
- 4.7.4 Rivalry among Existing Players
- 4.7.5 Threat of Substitutes
- 4.8 Comparative Analysis (Product, Financials, Patents, Pricing)
- 4.9 Startup Ecosystem Analysis
- 4.10 Market Entry Scenario (Ease-of-Doing-Business, Case Studies)
- 4.11 Market Entropy (New Product Launches, MandA, JV)
5 Market Size and Growth Forecasts (Value (USD))
- 5.1 By Authentication Type
- 5.1.1 Fingerprint Recognition
- 5.1.2 Face Recognition
- 5.1.3 Iris Recognition
- 5.1.4 Voice Recognition
- 5.1.5 Multimodal/MFA
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Commercial Vehicles
- 5.3 By Component
- 5.3.1 Hardware
- 5.3.2 Software/AI Stack
- 5.4 By Sales Channel
- 5.4.1 OEM Factory-Fit
- 5.4.2 Aftermarket/Retrofit
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Netherlands
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Continental AG
- 6.4.2 Robert Bosch GmbH
- 6.4.3 Denso Corporation
- 6.4.4 Safran SA
- 6.4.5 Valeo SA
- 6.4.6 Fingerprint Cards AB
- 6.4.7 Synaptics Inc.
- 6.4.8 Fujitsu Ltd
- 6.4.9 Hitachi Ltd
- 6.4.10 Methode Electronics
- 6.4.11 Nuance Communications
- 6.4.12 Cerence Inc.
- 6.4.13 Thales Group
- 6.4.14 Gentex Corporation
- 6.4.15 LG Electronics
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

