PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154390

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154390
Commercial Fans - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the commercial fans market size is expected to grow from USD 9.79 billion in 2025 to USD 10.29 billion in 2026 and is forecast to reach USD 13.41 billion by 2031 at 5.44% CAGR over 2026-2031.
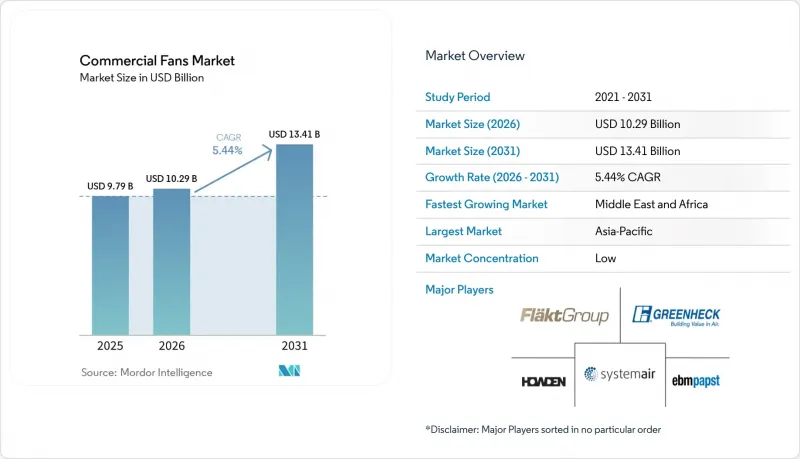
Global Commercial Fans Market Trends and Insights
Data Center and AI Cooling Infrastructure
Nearly 100 GW of data center capacity is expected to be added globally between 2026 and 2030, which supports a 14% CAGR for the sector. This construction pipeline raises demand for precision EC fans in computer room air-handling units and server-room exhaust systems, particularly in facilities that need dependable thermal control around dense computing equipment. Air cooling remains widely used below 30 kW per rack, which keeps fan demand relevant as liquid cooling expands and allows suppliers to serve both established and upgrading facilities. AI clusters operating above 40 kW per rack also need air-assist equipment before full liquid-cooling retrofits are completed, extending the role of fan systems during an intermediate stage of infrastructure change. Ziehl-Abegg announced an additional EUR 90 million investment, equivalent to USD 103.5 million, in European, U.S., and Asian capacity in June 2026 and identified AI data centers as a key driver. Tight construction capacity in data center projects can favor suppliers that can provide certified products, dependable lead times, and equipment suited to different cooling configurations.
Commercial Building Ventilation and HVAC Retrofit Demand
The commercial fans market benefits from retrofit demand because installed ventilation equipment has a different replacement cycle from new construction and cannot always be deferred when performance or compliance falls short. HVAC systems accounted for 35% to 50% of commercial building energy use, while hospitals and hotels can reach 70%. Standard 62.1-2025 added humidity control, demand-controlled ventilation, and updated exhaust-airflow requirements, which can prompt upgrades where those provisions are adopted, and local codes refer to the standard. Existing buildings also need better ventilation to remain attractive to tenants and comply with current operating expectations, even when broader office demand is weak. Efficient fans can lower operating costs where owners directly pay electricity bills and can document the benefits of lower electricity use. Split incentives can slow upgrades where tenants pay energy costs under legacy leases, especially in multi-tenant properties with limited capital budgets.
High Upfront Cost of Advanced Energy-Efficient Fan Systems
EC-motor fans can cost 30% to 60% more than induction-motor alternatives at purchase, creating an immediate barrier even when the operating cost is favorable. This price gap limits adoption by smaller owners and buyers focused on initial budgets, particularly in markets where capital approvals are separated from energy management. Utility rebates can offset 20% to 30% of qualifying upgrade costs, but access varies by location, and program administration can be difficult for operators without dedicated energy teams. Legacy lease structures weaken the owner's incentive when tenants bear electricity costs, leaving the buyer without a direct share of the potential savings. Differences in electricity tariffs also make a common procurement case harder to prepare across countries and building portfolios. Low structural clearances can further limit high-volume, low-speed fan retrofits in older urban buildings, even where operating economics support an upgrade.
Other drivers and restraints analyzed in the detailed report include:
- Energy Efficiency and Indoor Air Quality Regulations
- Warehouses, Modular Fan Walls, and Digital Verification
- Availability of Integrated HVAC and Alternative Air-Movement Technologies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Axial fans held 42.4% of the commercial fans market in 2025. Their cost and performance suit low-to-medium static-pressure work in HVAC distribution, rooftop exhaust, and warehouse circulation, where broad deployment supports repeat replacement demand. Centrifugal fans remain important in ducted systems that need higher pressure and a stable operating profile. Their larger footprint and energy use face greater scrutiny as building rules tighten and operators compare full operating costs. Exhaust fans retain a stable role because kitchens, hospitals, and similar settings must meet ventilation requirements, even when other commercial applications are more exposed to construction cycles.
Mixed-flow fans are projected to grow at a 5.7% CAGR through 2031. Their design combines high axial airflow with centrifugal pressure capability, offering a useful option between conventional axial and centrifugal designs. This makes them suitable for compact data center cooling racks, low-height duct runs, and rooftop systems with limited installation space. Greenheck introduced its RSQ direct-drive rooftop fan with mixed-flow technology in December 2025, with performance up to 27,100 cfm and AMCA licenses for FEI, air, and sound performance. Further work on clearance-flow-control shrouds points to continued efforts to improve pressure rise and reduce sound, narrowing the gap with centrifugal products in applications where space and acoustic performance are important.
Complete Report Scope:
- By Fan Type
- Axial Fans
- Centrifugal Fans
- Mixed-Flow Fans
- Exhaust Fans
- Other Commercial Fan Types
- By Application
- General Ventilation
- HVAC and Air Conditioning
- Cooling and Air Circulation
- Exhaust and Fume Extraction
- Other Applications
- By End User
- Office Buildings
- Retail and Shopping Centers
- Hotels and Hospitality
- Restaurants and Commercial Kitchens
- Hospitals and Healthcare Facilities
- Educational Institutions
- Warehouses and Distribution Centers
- Data Centers
- Transportation Infrastructure
- Other Commercial Facilities
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- Spain
- United Kingdom
- Poland
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Vietnam
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Morocco
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 42.1% of the commercial fans market in 2025. China combines manufacturing, warehousing, commercial real estate, and a growing hyperscale data center pipeline, creating demand across several major fan applications. Air-based cooling accounted for 60% of regional data center cooling revenue in 2025, which sustains demand for computer room air-handling and precision-cooling equipment. India, Vietnam, Indonesia, and Thailand add demand through urban development and early-stage data center construction, expanding the regional need for commercial ventilation equipment. Japan and South Korea support high-specification replacement demand under energy-efficiency requirements, where variable-speed EC systems are relevant.
North America and Europe form the technology leadership base for the commercial fans market. North American data center construction and aging commercial buildings support both new installations and retrofits, while specification work places a high value on tested product performance. Europe entered a compliance-led replacement cycle when Regulation 2024/1834 became enforceable in July 2026. Germany, France, the United Kingdom, and Poland are important European markets by volume, with Poland also gaining relevance as a data center and logistics location. Brazil and Chile provide growth from commercial construction in large cities and food-processing ventilation, although infrastructure and currency conditions limit the pace.
Middle East and Africa are projected to grow at a 5.9% CAGR through 2031. Saudi Arabia and the United Arab Emirates are adding data centers, airport capacity, hospitality properties, and mixed-use projects, which support higher-capacity ventilation demand. Extreme heat creates demand for equipment with reliable continuous operation and stronger thermal performance. South Africa and Egypt are secondary demand centers for healthcare and retail HVAC investment. Gulf specifications often require IP-rated housings, high-temperature motor windings, and corrosion-resistant coatings, which can support higher unit values and distinguish regional product requirements.
- Air Systems Components, Inc.
- Carrier Global Corporation
- Cincinnati Fan
- Daikin Industries, Ltd.
- ebm-papst Group
- FlaktGroup Holding GmbH
- Greenheck Fan Corporation
- Howden Group Ltd
- Johnson Controls International plc
- Loren Cook Company
- Munters Group AB
- New York Blower Company
- Rosenberg Ventilatoren GmbH
- Soler & Palau Ventilation Group
- Systemair AB
- Trane Technologies plc
- Twin City Fan Companies, Ltd.
- Vent-Axia
- Zhejiang Shangfeng Industrial Group Co., Ltd.
- Zhejiang Yilida Ventilator Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Data Center and AI Cooling Infrastructure
- 4.2.2 Commercial Building Ventilation and HVAC Retrofit Demand
- 4.2.3 Energy-Efficiency and Indoor-Air-Quality Regulations
- 4.2.4 Industrialization and Expansion of Warehouses and Distribution Centers
- 4.2.5 Modular Fan-Wall Adoption in Brownfield Air-Handling Units
- 4.2.6 Fan-Energy-Index-Based Procurement and Digital Performance Verification
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost of Advanced Energy-Efficient Fan Systems
- 4.3.2 Availability of Integrated HVAC and Alternative Air-Movement Technologies
- 4.3.3 Structural and Clearance Constraints for High-Volume Low-Speed Fan Retrofits
- 4.3.4 Rare-Earth Magnet and Specialty-Alloy Supply Exposure
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Fan Type
- 5.1.1 Axial Fans
- 5.1.2 Centrifugal Fans
- 5.1.3 Mixed-Flow Fans
- 5.1.4 Exhaust Fans
- 5.1.5 Other Commercial Fan Types
- 5.2 By Application
- 5.2.1 General Ventilation
- 5.2.2 HVAC and Air Conditioning
- 5.2.3 Cooling and Air Circulation
- 5.2.4 Exhaust and Fume Extraction
- 5.2.5 Other Applications
- 5.3 By End User
- 5.3.1 Office Buildings
- 5.3.2 Retail and Shopping Centers
- 5.3.3 Hotels and Hospitality
- 5.3.4 Restaurants and Commercial Kitchens
- 5.3.5 Hospitals and Healthcare Facilities
- 5.3.6 Educational Institutions
- 5.3.7 Warehouses and Distribution Centers
- 5.3.8 Data Centers
- 5.3.9 Transportation Infrastructure
- 5.3.10 Other Commercial Facilities
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 France
- 5.4.2.3 Italy
- 5.4.2.4 Spain
- 5.4.2.5 United Kingdom
- 5.4.2.6 Poland
- 5.4.2.7 Russia
- 5.4.2.8 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Indonesia
- 5.4.3.7 Vietnam
- 5.4.3.8 Thailand
- 5.4.3.9 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Chile
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Egypt
- 5.4.5.4 South Africa
- 5.4.5.5 Morocco
- 5.4.5.6 Rest of Middle East and Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Air Systems Components, Inc.
- 6.4.2 Carrier Global Corporation
- 6.4.3 Cincinnati Fan
- 6.4.4 Daikin Industries, Ltd.
- 6.4.5 ebm-papst Group
- 6.4.6 FlaktGroup Holding GmbH
- 6.4.7 Greenheck Fan Corporation
- 6.4.8 Howden Group Ltd
- 6.4.9 Johnson Controls International plc
- 6.4.10 Loren Cook Company
- 6.4.11 Munters Group AB
- 6.4.12 New York Blower Company
- 6.4.13 Rosenberg Ventilatoren GmbH
- 6.4.14 Soler & Palau Ventilation Group
- 6.4.15 Systemair AB
- 6.4.16 Trane Technologies plc
- 6.4.17 Twin City Fan Companies, Ltd.
- 6.4.18 Vent-Axia
- 6.4.19 Zhejiang Shangfeng Industrial Group Co., Ltd.
- 6.4.20 Zhejiang Yilida Ventilator Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

