PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154397

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154397
Telecom Infrastructure Valuation Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
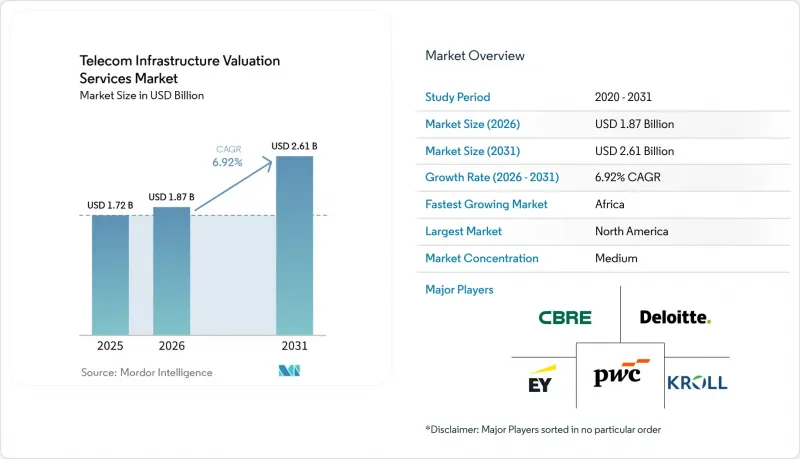
According to Mordor Intelligence, the telecom infrastructure valuation services market size was valued at USD 1.72 billion in 2025 and estimated to expand from USD 1.87 billion in 2026 to reach USD 2.61 billion by 2031, at a CAGR of 6.92% during the forecast period 2026-2031.
Global Telecom Infrastructure Valuation Services Market Trends and Insights
5G and 5G-Advanced Infrastructure Densification
Network densification creates a recurring need to update asset registers, support financing, and prepare fair-value opinions. The United States had an extensive deployment of macrocell sites and indoor small-cell nodes in operation at the end of 2025. GSA reported that hundreds of operators had launched 5G networks globally as of April 2026, representing growth since March 2025. Each site addition can bring new radio equipment, backhaul links, lease records, and technical specifications that need to be reflected in an asset record. Shared sites now accommodate more frequencies and technologies, so defensible valuation work requires stronger radio-frequency engineering inputs. This shift increases the value of advisers who can connect site-level technical evidence with financial assumptions across the telecom infrastructure valuation services market.
Mobile Infrastructure M&A and Asset-Monetization Activity
Tower sales, carve-outs, and sale-leaseback transactions create work across technical diligence, fairness opinions, and purchase price allocation. KKR announced a significant preferred equity investment in Vertical Bridge in April 2026, and the release valued the operator in the multibillion-dollar range. Macquarie Asset Management agreed in April 2026 to acquire IHS Towers' South American operations, including a substantial portfolio of sites in Brazil and Colombia. These transactions require a view of physical assets, tenancy, contracts, local operating conditions, reported asset records, site access, maintenance requirements, network dependencies, and the assumptions used to translate operating evidence into expected cash flows before investors and lenders commit capital. Post-acquisition reporting requirements can create further work when buyers allocate transaction value across acquired towers, small cells, fiber, spectrum rights, and related contractual assets. The telecom infrastructure valuation services market, therefore, benefits from the full transaction cycle rather than only the point at which a deal is announced.
Limited Disclosure of Private Tower and Fiber Transactions
Many tower assets are held by infrastructure funds, and the details of private transactions do not enter public registries. This reduces the availability of comparable sales data, especially where few similar assets have changed hands publicly or where portfolios have different tenancy, lease, and site-condition profiles. Advisers then rely more heavily on proprietary transaction databases, income evidence, and records collected from prior engagements. That reliance can favor established firms with longer records of transactions and sector-specific asset information. When regulators require auditable values for merger clearance or financial reporting, practitioners may use income-based methods with a wider range of assumptions around revenue, discount rates, lease terms, and residual value. The telecom infrastructure valuation services market faces a continuing need for transparent data because limited comparables raise review time and professional exposure for contested opinions.
Other drivers and restraints analyzed in the detailed report include:
- Rising Complexity of Multi-Asset Network Portfolios
- Public Funding and Rural Coverage Programs
- Interest-Rate and Discount-Rate Sensitivity of Long-Lived Assets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Asset Appraisal and Fair-Value Opinion Services held 25.44% of the telecom infrastructure valuation services market share in 2025. Recurring financial reporting under IFRS and U.S. GAAP supports demand for periodic independent opinions when infrastructure assets are carried at revalued amounts, creating repeat work within the telecom infrastructure valuation services market. Transaction and M&A Valuation Advisory also benefits from continued portfolio sales and acquisitions. Technical, Commercial, and Financial Due Diligence has become more important where asset records can affect purchase price discussions.
Spectrum and License Valuation Services is projected to expand at a CAGR of 7.13% through 2031. GSMA stated that close to 1,000 individual spectrum license renewals were expected across 110 countries between 2025 and 2030. Renewals require specialized economic work because reserve prices and annual license fees depend on local market conditions, the available spectrum bands, regulatory choices, and the treatment of existing network obligations. Transaction teams also need a clear view of spectrum rights when those rights affect the commercial value of a network portfolio. Lease optimization advisory and regulatory economics consulting remain smaller service areas, but they extend the scope of work available to advisers. The telecom infrastructure valuation services industry is thus supported by both recurring reporting assignments and event-led specialist mandates.
Macro Towers accounted for 33.36% of the telecom infrastructure valuation services market size in 2025. They are the main assets considered in many TowerCo transactions and are common collateral in tower-backed debt structures within the telecom infrastructure valuation services market. Their established lease patterns and physical characteristics provide a familiar basis for valuation, although tenant concentration and renewal assumptions remain important. Rooftop sites also have strategic value in dense urban locations where zoning limits greenfield construction.
Small Cells and Distributed Antenna Systems is projected to expand at a CAGR of 7.22% through 2031. Small Cell Forum projected strong growth in global small-cell deployments, with annual shipments expected to reach several million units. These assets operate in varied settings, including stadiums, campuses, street poles, indoor locations, and enterprise sites, so they require methods that account for different deployment, access, operating, and revenue conditions. Their physical scale can be smaller than a macro tower, but the review often involves more varied documentation across a portfolio. Fiber backhaul and transport networks are also increasingly reviewed as separate assets because their commercial role differs from that of a tower. The telecom infrastructure valuation services market is adapting to these asset types through broader technical review and more detailed asset-level evidence.
Complete Report Scope:
- By Service Type
- Asset Appraisal and Fair-Value Opinion Services
- Transaction and M&A Valuation Advisory
- Technical, Commercial, and Financial Due Diligence
- Spectrum and License Valuation Services
- Other Service Types
- By Asset Type
- Macro Towers
- Rooftop Sites
- Small Cells and Distributed Antenna Systems
- Fiber Backhaul and Transport Networks
- By Client Type
- Mobile Network Operators
- TowerCos and Neutral-Host Providers
- Infrastructure Funds and Private Equity Investors
- By Engagement Purpose
- Acquisitions, Divestitures, and Carve-Outs
- Financing, Refinancing, and Recapitalization
- Financial Reporting and Tax Compliance
- Other Engagement Purposes
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America held 32.47% share in 2025. The United States recorded substantial wireless infrastructure investment and maintained a large macrocell site base. Vertical Bridge's acquisition of Verizon towers was followed by a KKR investment, supporting continued asset review needs across the telecom infrastructure valuation services market. ATN International also announced the sale of southwestern U.S. towers to Everest Infrastructure Partners for a substantial value. Canada added activity through the formation of Terrion and the proposed sale of SBA Communications' Canadian tower business.
Europe has a stable base of mobile network operator carve-outs and regulatory spectrum work. The Baltic Tower Company transaction created a cross-border portfolio that needed consistent asset review across three national markets. Stonepeak agreed in December 2025 to acquire TeleTower from Bite Group in Lithuania and Latvia. BEREC's 2025 WACC work showed that regulatory valuation assumptions remain important across the European Union.
Asia-Pacific has a large asset base, supported by China Tower's significant capital expenditure and plans to develop AI-ready digital infrastructure. Africa is projected to expand at a CAGR of 7.47% through 2031. GSMA reported significant planned network investment by African operators through 2030, supporting a future pipeline as assets are built and financed. Network investment in these regions requires assets to be documented as they are funded, constructed, operated, and transferred. These regional conditions keep the telecom infrastructure valuation services market tied to network buildouts, portfolio transactions, and asset data verification.
- Altman Solon
- Analysys Mason Limited
- American Appraisal Associates, LLC
- CBRE Group, Inc.
- CostQuest Associates, Inc.
- Deloitte Touche Tohmatsu Limited
- EY-Parthenon
- GP Valuation and Advisory Services
- KPMG International Limited
- Kroll, LLC
- Lender Consulting Services, Inc.
- Mercer Capital Management, Inc.
- Meksist Information Technologies
- Parcus Group
- PricewaterhouseCoopers International Limited
- Signal Strength Advisors
- SteelTree Partners
- Summit Ridge Group, LLC
- Tower Capital Advisors, LLC
- Valtech Valuation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 5G and 5G-Advanced Infrastructure Densification
- 4.3.2 Mobile Infrastructure M&A and Asset-Monetization Activity
- 4.3.3 Rising Complexity of Multi-Asset Network Portfolios
- 4.3.4 Public Funding and Rural Coverage Programs
- 4.3.5 Digital-Twin and Geospatial Data Adoption in Asset Underwriting
- 4.3.6 Revaluation Demand from Energy, Lease, and Co-Location Volatility
- 4.4 Market Restraints
- 4.4.1 Limited Disclosure of Private Tower and Fiber Transactions
- 4.4.2 Interest-Rate and Discount-Rate Sensitivity of Long-Lived Assets
- 4.4.3 Inconsistent Asset Data Across MNO and TowerCo Portfolios
- 4.4.4 Permitting, Zoning, and Site-Access Uncertainty
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Asset Appraisal and Fair-Value Opinion Services
- 5.1.2 Transaction and M&A Valuation Advisory
- 5.1.3 Technical, Commercial, and Financial Due Diligence
- 5.1.4 Spectrum and License Valuation Services
- 5.1.5 Other Service Types
- 5.2 By Asset Type
- 5.2.1 Macro Towers
- 5.2.2 Rooftop Sites
- 5.2.3 Small Cells and Distributed Antenna Systems
- 5.2.4 Fiber Backhaul and Transport Networks
- 5.3 By Client Type
- 5.3.1 Mobile Network Operators
- 5.3.2 TowerCos and Neutral-Host Providers
- 5.3.3 Infrastructure Funds and Private Equity Investors
- 5.4 By Engagement Purpose
- 5.4.1 Acquisitions, Divestitures, and Carve-Outs
- 5.4.2 Financing, Refinancing, and Recapitalization
- 5.4.3 Financial Reporting and Tax Compliance
- 5.4.4 Other Engagement Purposes
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Egypt
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Altman Solon
- 6.4.2 Analysys Mason Limited
- 6.4.3 American Appraisal Associates, LLC
- 6.4.4 CBRE Group, Inc.
- 6.4.5 CostQuest Associates, Inc.
- 6.4.6 Deloitte Touche Tohmatsu Limited
- 6.4.7 EY-Parthenon
- 6.4.8 GP Valuation and Advisory Services
- 6.4.9 KPMG International Limited
- 6.4.10 Kroll, LLC
- 6.4.11 Lender Consulting Services, Inc.
- 6.4.12 Mercer Capital Management, Inc.
- 6.4.13 Meksist Information Technologies
- 6.4.14 Parcus Group
- 6.4.15 PricewaterhouseCoopers International Limited
- 6.4.16 Signal Strength Advisors
- 6.4.17 SteelTree Partners
- 6.4.18 Summit Ridge Group, LLC
- 6.4.19 Tower Capital Advisors, LLC
- 6.4.20 Valtech Valuation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

