PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154422

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154422
South America E-Cigarettes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
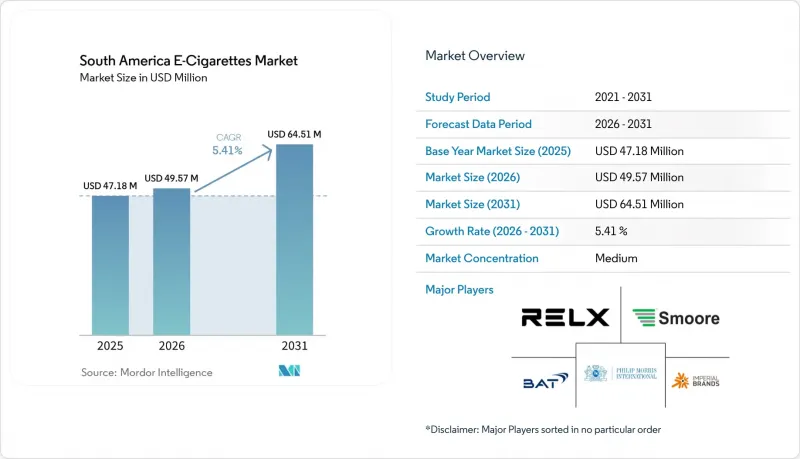
According to Mordor Intelligence, the South America e-cigarette market size was valued at USD 47.18 million in 2025 and estimated to grow from USD 49.57 million in 2026 to reach USD 64.51 million by 2031, at a CAGR of 5.41% during the forecast period (2026-2031).
South America E-Cigarettes Market Trends and Insights
Digital Discovery and Social-Commerce Reach Among Adult Consumers
Digital product discovery reaches adult consumers before they make formal purchase decisions in the South America e-cigarette market. Social media platforms, online marketplaces, and delivery applications have normalized product searches and repeat purchases in Colombia, Peru, and Argentina. Colombia's Superintendence of Industry and Commerce issued Resolution No. 30838 in May 2025 to regulate consumer access to information on vaping products. While the resolution addresses information access, authorities face greater challenges in monitoring digital promotion and peer-to-peer visibility at scale. Therefore, compliant local-language content and verified online purchasing systems can serve as valuable commercial capabilities. Online sellers that demonstrate effective age-verification processes and maintain product documentation will be better positioned as enforcement becomes more stringent.
Regulatory Normalization in Colombia, Chile, Peru, and Paraguay
Regulatory changes are shifting informal sales into licensed and taxable channels across several South American countries. Colombia's Law 2354 of 2024 extended tobacco control regulations to e-cigarettes, establishing requirements that support a formal retail environment. Chile's Decree No. 41 took effect in May 2025 and introduced health-warning requirements for electronic nicotine delivery systems and vaping liquids. Peru implemented advertising restrictions and age-verification requirements under Law No. 32159; however, the supplied material did not include complete implementation details regarding flavors. Paraguay's Law No. 7508 of 2025 requires product registration, limits imports to closed-device formats, and caps nicotine concentrations at 20 mg/mL. These clearer regulations enable compliant suppliers to plan investments in product registration, retail access, and legal distribution across the South American e-cigarette market.
Country-Level Bans and Uneven Regulatory Recognition
Brazil continues to prohibit the manufacturing, importation, and sale of e-cigarettes under ANVISA Resolution RDC No. 855/2024. This ban excludes the continent's largest consumer base from legal sales, although informal demand persists. According to the supplied material, 4 million people in Brazil used e-cigarettes through informal channels during the ban. Venezuela also restricts the development of a formal local market by prohibiting manufacturing and imports. Informal suppliers can undercut the prices of licensed products by avoiding registration, taxation, and labeling costs. This price advantage can sustain informal distribution channels and limit the development of regulated e-cigarette markets. Regional enforcement cooperation remains important; however, the PAHO tobacco-control strategy does not establish a binding enforcement mechanism.
Other drivers and restraints analyzed in the detailed report include:
- Product Innovation in Closed-Pod and High-Capacity Disposable Devices
- Adult-Smoker Switching and Refillable-System Adoption
- Illicit and Counterfeit Product Competition
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
E-cigarette devices accounted for 82.72% of the South American e-cigarette market share in 2025. This substantial share reflects the requirement for each new user to purchase hardware before generating recurring spending on consumables. Disposable devices are gaining traction in Colombia and Peru because they require minimal setup at the point of purchase. Rechargeable devices support longer usage periods and can drive repeat purchases over time. Retailers benefit from offering hardware for hands-on evaluation through specialty stores, convenience outlets, and other formal retail channels. The device category remains closely linked to the expansion of the installed user base. As adoption increases, demand for entry-level and advanced device formats is likely to broaden across the region.
E-liquids are forecast to register the fastest product-type CAGR of 7.45% during 2026-2031. This faster growth highlights the increasing importance of repeat consumable purchases as users continue vaping after their initial device purchase. The expansion of formal retail channels in Colombia can facilitate replenishment by increasing the number of purchase locations. This expansion can shift e-liquid purchases from planned shopping trips to more frequent, convenience-driven purchases. In 2025, PAHO warned about flavored tobacco and nicotine products and reported an e-cigarette prevalence of 5.4% among adolescents in the Americas. Brands must therefore prepare for stricter flavor regulations while maintaining compliant product documentation and locally appropriate product portfolios. Regulatory developments may also influence product availability and the range of e-liquid formulations offered through formal retail channels.
Closed vaping systems accounted for 74.37% of the South America e-cigarette market in 2025. Pre-filled pods eliminate the need to handle e-liquids or adjust device settings, making these systems more accessible to adult consumers seeking a straightforward initial product experience. Closed systems also enable brands to maintain product traceability through controlled cartridge and device supply. Their distribution model supports consistent retailer margins and clearer compliance procedures. These characteristics underpin their broad adoption across regulated and newly formalizing national markets. This format is particularly suited to markets where standardized products and controlled distribution channels support regulatory oversight.
Open vaping systems are projected to record the fastest category CAGR of 7.98% during 2026-2031. Refillable tanks appeal to cost-conscious and technically engaged adult consumers seeking a broader range of e-liquid options. The supplied material indicates that open systems can reduce per-use costs by 40% to 60% compared with proprietary pods. The supplied draft also indicates that a substantial share of consumers in Colombia prefer open systems. However, Paraguay's Law No. 7508/2025 restricts legal imports and manufacturing to closed-device formats. These varying country-level requirements favor brands that can meet regulatory compliance obligations while addressing distinct consumer preferences. As regulations evolve across the region, manufacturers will need to adapt their product portfolios to country-specific legal frameworks.
Complete Report Scope:
- By Product Type
- E-Cigarette Device
- Disposable
- Non-Disposable
- E-Liquid
- E-Cigarette Device
- By Category
- Open Vaping Systems
- Closed Vaping Systems
- By End User
- Men
- Women
- By Distribution Channel
- Offline Retail
- Online Retail
- By Geography
- Colombia
- Peru
- Rest of South America
List of Companies Covered in this Report:
- British American Tobacco PLC
- Philip Morris International Inc.
- Imperial Brands PLC
- Japan Tobacco International
- RELX Technology
- Smoore International Holdings Limited
- Shenzhen IVPS Technology Co., Ltd.
- Innokin Technology Co., Ltd.
- KangerTech
- GeekVape
- Vaporesso
- JUUL Labs, Inc.
- NJOY LLC
- Altria Group, Inc.
- OXVA
- Aspire Global
- Joyetech
- Suorin
- ELFBAR
- BIDI Vapor
- Moti Global
- Shenzhen FirstUnion Technology Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Digital discovery and social-commerce reach among adult consumers
- 4.2.2 Regulatory normalization in Colombia, Chile, Peru and Paraguay
- 4.2.3 Product innovation in closed-pod and high-capacity disposable devices
- 4.2.4 Adult-smoker switching and refillable-system adoption
- 4.2.5 Cross-border access to products unavailable through domestic retail
- 4.2.6 Localized flavors and nicotine-strength preferences
- 4.3 Market Restraints
- 4.3.1 Country-level bans and uneven regulatory recognition
- 4.3.2 Illicit and counterfeit product competition
- 4.3.3 Battery, shipping and product-compliance constraints
- 4.3.4 Currency volatility and import-cost Inflation
- 4.4 Value Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE )
- 5.1 By Product Type
- 5.1.1 E-Cigarette Device
- 5.1.1.1 Disposable
- 5.1.1.2 Non-Disposable
- 5.1.2 E-Liquid
- 5.1.1 E-Cigarette Device
- 5.2 By Category
- 5.2.1 Open Vaping Systems
- 5.2.2 Closed Vaping Systems
- 5.3 By End User
- 5.3.1 Men
- 5.3.2 Women
- 5.4 By Distribution Channel
- 5.4.1 Offline Retail
- 5.4.2 Online Retail
- 5.5 By Geography
- 5.5.1 Colombia
- 5.5.2 Peru
- 5.5.3 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 British American Tobacco PLC
- 6.4.2 Philip Morris International Inc.
- 6.4.3 Imperial Brands PLC
- 6.4.4 Japan Tobacco International
- 6.4.5 RELX Technology
- 6.4.6 Smoore International Holdings Limited
- 6.4.7 Shenzhen IVPS Technology Co., Ltd.
- 6.4.8 Innokin Technology Co., Ltd.
- 6.4.9 KangerTech
- 6.4.10 GeekVape
- 6.4.11 Vaporesso
- 6.4.12 JUUL Labs, Inc.
- 6.4.13 NJOY LLC
- 6.4.14 Altria Group, Inc.
- 6.4.15 OXVA
- 6.4.16 Aspire Global
- 6.4.17 Joyetech
- 6.4.18 Suorin
- 6.4.19 ELFBAR
- 6.4.20 BIDI Vapor
- 6.4.21 Moti Global
- 6.4.22 Shenzhen FirstUnion Technology Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

