PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154721

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154721
South America Blood Glucose Monitoring - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
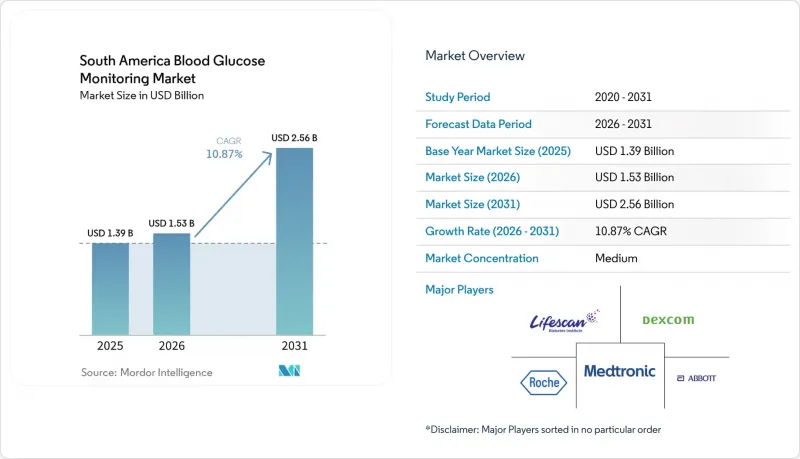
According to Mordor Intelligence, the South America blood glucose monitoring market size was valued at USD 1.39 billion in 2025 and is estimated to grow from USD 1.53 billion in 2026 to reach USD 2.56 billion by 2031, at a CAGR of 10.87% during the forecast period (2026-2031).
South America Blood Glucose Monitoring Market Trends and Insights
Rising Diabetes Burden and Undiagnosed Population
The South American blood glucose monitoring market is supported by the region's growing diabetes burden. South and Central America recorded 35.4 million people with diabetes in 2024, and this figure is projected to increase by 46% to 52 million by 2050. The 2025 IDF analysis reported that 42.8% of adults with diabetes worldwide were undiagnosed in 2024, representing 251.7 million people. PAHO reported in 2025 that 43 million people in the Americas lacked access to diabetes treatment, highlighting the gap between clinical need and access.
Expansion of Public Health Procurement and Essential Technology Access
Public procurement is expanding the South American blood glucose monitoring market beyond private retail demand. Brazil's national reimbursement position did not prevent state and municipal programs from expanding local access to monitoring technologies. This structure creates multiple purchasing channels and supports a more resilient demand base. Suppliers must meet location-specific product specifications, purchasing volumes, contract periods, registration, and accuracy requirements.
High Out of Pocket Cost and Uneven Insurance Coverage
High device costs continue to limit access to diabetes monitoring products, particularly where public coverage remains unavailable. This creates disparities between users covered by private insurance or local programs and those relying on public healthcare systems. The pace of coverage expansion across income groups and geographies influences the South American blood glucose monitoring market. Brazil's consultation on real-time CGM in SUS remains significant, as a national decision could expand access for a large population of patients with Type 1 diabetes. Until coverage becomes more consistent, lower-cost self-monitoring devices and public dispensing programs will remain important.
Other drivers and restraints analyzed in the detailed report include:
- Increasing CGM Reimbursement and Health Benefit Inclusion
- Pharmacy Led and Direct to Consumer Sensor Adoption
- Import Dependence, Currency Volatility, and Tender Price Pressure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Self-monitoring blood glucose devices held 53.01% of regional demand in 2025. The segment remains essential because glucometers, test strips, and lancets are affordable and widely used across public healthcare and home-care settings. Test strips and lancets generate recurring revenue through regular patient replenishment, while conventional glucometers remain a common entry point for newly diagnosed patients. Hospitals, clinics, and public programs maintain substantial installed bases, and a 2025 real-world study in Brazil found better glycemic control among flash glucose monitoring users than traditional monitoring users. SMBG will remain relevant where affordability and access are key decision factors.
Continuous glucose monitoring devices are forecast to grow at a 12.67% CAGR from 2026 to 2031. The category includes sensors and receiver or transmitter units that provide more frequent glucose information, supported by reimbursement activity, product availability, and clinical adoption. The 2025 Latin American consensus set out 12 recommendations for evaluating CGM systems, including accuracy and post-market surveillance considerations. Product accuracy, safety, patient support, local training, and customer service are becoming key supplier selection criteria. These clinical and policy developments are expected to support CGM market growth while creating higher entry barriers for lower-specification products.
Type 2 diabetes accounted for 85.30% of regional demand in 2025 and is projected to grow at a 14.34% CAGR through 2031. This patient group represents the largest user base and is increasingly adopting continuous monitoring as insulin therapy becomes more intensive. Routine glucose assessment and consumable replenishment support the South American blood glucose monitoring market size for Type 2 diabetes. A 2025 study from Pontificia Universidad Javeriana reported that a digital ecosystem for ambulatory Type 2 diabetes care reduced median HbA1c from 9.1% to 7.0% over three months. Such outcomes support payer assessments of structured monitoring and may expand reimbursement eligibility for this patient group.
Type 1 diabetes patients represent a smaller population but have a strong clinical need for continuous glucose monitoring. Coverage decisions in Chile and the ongoing Brazilian review have placed Type 1 diabetes at the center of public CGM discussions. Chile's GES framework has formalized access for eligible people under 18 and pregnant women with Type 1 diabetes. Gestational diabetes and other patient categories require intensive monitoring, specialist oversight, and products suited to pediatric and pregnancy care. Reliable education and follow-up remain critical for safe device use across these clinical pathways.
Complete Report Scope:
- By Device Type
- Self-Monitoring Blood Glucose Devices
- Glucometer Devices
- Test Strips
- Lancets and Lancing Devices
- Continuous Glucose Monitoring Devices
- Sensors
- Receivers and Transmitters
- Self-Monitoring Blood Glucose Devices
- By Patient Type
- Type 1 Diabetes
- Type 2 Diabetes
- Gestational Diabetes and others
- By End User
- Home Care
- Hospitals and Clinics
- Diagnostic Laboratories
- Others
- By Distribution Channel
- Institutional Procurement
- Retail Pharmacies
- E-Commerce and Direct-to-Consumer
- By Geography
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
List of Companies Covered in this Report:
- Abbott Laboratories
- Acon Laboratories
- AgaMatrix, Inc.
- Arkray
- Ascensia Diabetes Care Holdings AG
- Bionime
- Dexcom
- Roche
- Insulet
- I-Sens
- Lifescan
- MEDISANA GmbH
- Medtronic
- Nipro
- Nova Biomedical
- Rossmax
- Senseonics, Inc.
- Tandem Diabetes Care
- Trividia Health, Inc.
- Ypsomed
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Diabetes Burden and Undiagnosed Population
- 4.2.2 Expansion of Public-Health Procurement and Essential-Technology Access
- 4.2.3 Increasing CGM Reimbursement and Health-Benefit Inclusion
- 4.2.4 Pharmacy-Led and Direct-to-Consumer Sensor Adoption
- 4.2.5 Remote Diabetes Management and Connected Care
- 4.2.6 Local Distributor and Specialist-Clinic Networks
- 4.3 Market Restraints
- 4.3.1 High Out-of-Pocket Cost and Uneven Insurance Coverage
- 4.3.2 Import Dependence, Currency Volatility, and Tender Price Pressure
- 4.3.3 Fragmented Regulatory and Reimbursement Pathways
- 4.3.4 Limited Interoperability, Training, and Data-Connectivity Infrastructure
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Device Type
- 5.1.1 Self-Monitoring Blood Glucose Devices
- 5.1.1.1 Glucometer Devices
- 5.1.1.2 Test Strips
- 5.1.1.3 Lancets and Lancing Devices
- 5.1.2 Continuous Glucose Monitoring Devices
- 5.1.2.1 Sensors
- 5.1.2.2 Receivers and Transmitters
- 5.1.1 Self-Monitoring Blood Glucose Devices
- 5.2 By Patient Type
- 5.2.1 Type 1 Diabetes
- 5.2.2 Type 2 Diabetes
- 5.2.3 Gestational Diabetes and others
- 5.3 By End User
- 5.3.1 Home Care
- 5.3.2 Hospitals and Clinics
- 5.3.3 Diagnostic Laboratories
- 5.3.4 Others
- 5.4 By Distribution Channel
- 5.4.1 Institutional Procurement
- 5.4.2 Retail Pharmacies
- 5.4.3 E-Commerce and Direct-to-Consumer
- 5.5 By Geography
- 5.5.1 Brazil
- 5.5.2 Argentina
- 5.5.3 Colombia
- 5.5.4 Chile
- 5.5.5 Peru
- 5.5.6 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 ACON Laboratories, Inc.
- 6.3.3 AgaMatrix, Inc.
- 6.3.4 ARKRAY, Inc.
- 6.3.5 Ascensia Diabetes Care Holdings AG
- 6.3.6 Bionime Corporation
- 6.3.7 DexCom, Inc.
- 6.3.8 F. Hoffmann-La Roche Ltd
- 6.3.9 Insulet Corporation
- 6.3.10 i-SENS, Inc.
- 6.3.11 LifeScan, Inc.
- 6.3.12 MEDISANA GmbH
- 6.3.13 Medtronic plc
- 6.3.14 Nipro Corporation
- 6.3.15 Nova Biomedical Corporation
- 6.3.16 Rossmax International Ltd.
- 6.3.17 Senseonics, Inc.
- 6.3.18 Tandem Diabetes Care, Inc.
- 6.3.19 Trividia Health, Inc.
- 6.3.20 Ypsomed Holding AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

