PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154803

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154803
Precision Grinding Wheels - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
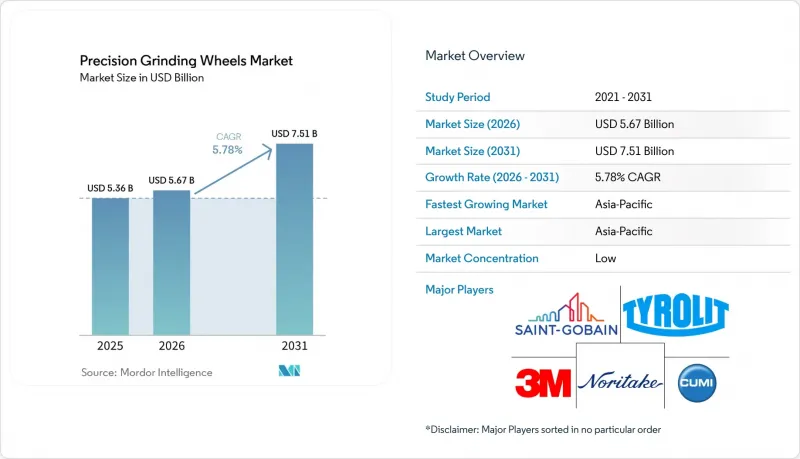
According to Mordor Intelligence, the precision grinding wheels market size was valued at USD 5.36 billion in 2025 and is estimated to grow from USD 5.67 billion in 2026 to reach USD 7.51 billion by 2031, at a CAGR of 5.78% during the forecast period (2026-2031).
Global Precision Grinding Wheels Market Trends and Insights
Rising Demand for Tight-Tolerance Components
Precision manufacturers need tighter dimensional control in aerospace, semiconductor, optical, and composite-material applications. A 2026 review identified efficiency, surface integrity, and form accuracy as central challenges in ultra-precision grinding of hard-brittle materials. The review identified semiconductor wafers, large-aperture optics, and aerospace composites as major application areas for these processes. It also identified machine-learning-enabled wheel monitoring and electrolytic in-process dressing as useful technologies for improving process control. Damage-free wafer grinding requires fine diamond grains, controlled porosity, and in-process measurement, which raises the technical threshold for wheel suppliers. These needs support demand in the precision grinding wheels market for application-specific wheels rather than general-purpose products.
Adoption of CBN and Diamond Superabrasives
The precision grinding wheels market is shifting toward CBN and diamond products in applications where tolerance, cycle time, and wheel life are critical. JTEKT Corporation documented that its nanoVi vitrified-bond diamond wheel for silicon carbide power-semiconductor wafer thinning delivered a service life 2.3 times that of conventional wheels. The result came from optimization of abrasive grains, bonding agents, and pore ratios. China implemented export licensing controls on synthetic diamond micropowder, single crystals, wire saws, and precision grinding wheels effective November 8, 2025. These controls added a supply-chain consideration to wheel selection for manufacturers dependent on Chinese diamond inputs. The precision grinding wheels market, therefore, faces stronger incentives to qualify alternative materials and sources while retaining process performance.
High Cost of Superabrasive Wheels and Specialized Dressing
CBN and diamond wheels cost more than conventional aluminum oxide wheels, which can limit their adoption by smaller manufacturers. The initial investment also includes dressing equipment that can retain wheel profiles at micron-level accuracy. China's 2025 export licensing controls on synthetic diamond inputs have added uncertainty around delivery schedules and material costs. This is especially difficult in price-sensitive applications where customers focus on the purchase price instead of lifecycle performance. The precision grinding wheels market must therefore address the gap between a wheel's initial cost and its expected production benefit. Suppliers are more likely to win adoption when they can show a stable process and an acceptable qualification path.
Other drivers and restraints analyzed in the detailed report include:
- Automation and CNC Grinding Adoption
- Expansion of Aerospace, Medical and Semiconductor Manufacturing
- Skilled Operator and Process-Engineering Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cylindrical external grinding wheels held 33.67% of the precision grinding wheels market share in 2025. The segment serves crankshaft, camshaft, bearing-race, shaft, and hydraulic-component production. Its position reflects the broad use of cylindrical parts across automotive and industrial machinery manufacturing. External grinding remains important where producers need repeatable dimensions at high production volumes. It also provides a stable base for established bonded abrasive products. The precision grinding wheels market size for this type benefits from continued demand for precision-engineered rotating components.
Internal grinding wheels are projected to advance at a 6.45% CAGR through 2031. Electric vehicle designs need hollow precision shafts, bore-intensive motor housings, and compact bearing assemblies that require internal grinding geometries. This supports a shift in tooling investment toward applications that cannot be served by external wheels. Surface grinding wheels and centerless grinding wheels continue to serve broad metalworking and bearing applications. Their demand is more closely tied to industrial utilization and high-volume component production. Certification and traceability requirements remain relevant across all wheel types because automotive and aerospace customers require controlled production processes.
Complete Report Scope:
- By Type
- Cylindrical External Grinding Wheels
- Internal Grinding Wheels
- Surface Grinding Wheels
- Centerless Grinding Wheels
- By Material
- Aluminum Oxide
- Silicon Carbide
- Cubic Boron Nitride
- Diamond
- Other Materials
- By End-User Industry
- Automotive
- Aerospace and Defense
- Metalworking and Fabrication
- Bearing and Machinery Manufacturing
- Semiconductor and Electronics
- Other End-User Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 38.93% of revenue in 2025 and is projected to advance at a 6.93% CAGR through 2031. The region combines automotive production, semiconductor fabrication, and precision equipment manufacturing. China supplies major automotive and semiconductor manufacturing demand. Japan contributes demand from precision bearings, semiconductor equipment, and machinery. India is becoming both a consumption location and a production base for grinding wheel suppliers. The precision grinding wheels market size in the region also reflects electronics demand in South Korea and the Association of Southeast Asian Nations (ASEAN) countries, including Vietnam.
Tyrolit AG broke ground on a Pune facility to provide local retipping and finishing for CBN and diamond wheels. The site also functions as a technical and training center for India's precision manufacturing base. CUMI commenced commercial production at its Hosur facility in March 2026, doubling annual cutting and grinding wheel capacity from 45 million to more than 90 million wheels. The facility uses supervisory control and data acquisition (SCADA)-based process controls, automated press lines, and unmanned oven handling. These developments strengthen local capacity and technical service in the Asia-Pacific.
North America and Europe remain technically demanding regions where aerospace, automotive engineering, and precision manufacturing support premium wheel demand. Saint-Gobain completed a 47,000 square foot administration building at its Worcester, Massachusetts, abrasives campus in January 2026. European demand is also supported by brake-disc requirements associated with Euro 7. South America and Middle East and Africa remain smaller contributors with demand from automotive production, metalworking, steel processing, mining equipment maintenance, petrochemical fabrication, and construction. Limited training infrastructure and competition from lower-cost imports can slow the adoption of superabrasive products in these areas.
- 3M
- Asahi Diamond Industrial Co., Ltd.
- August Ruggeberg GmbH & Co. KG
- CUMI
- Hindustan Abrasives
- Klingspor AG
- KREBS & RIEDEL Schleifscheibenfabrik GmbH & Co. KG
- KURE GRINDING WHEE
- LACH DIAMANT
- NORITAKE CO., LIMITED
- Saint-Gobain
- SAK ABRASIVES LIMITED
- Sterling Abrasives Limited
- Tyrolit AG
- Wendt (India) Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Tight-Tolerance Components
- 4.2.2 Adoption of CBN and Diamond Superabrasives
- 4.2.3 Automation and CNC Grinding Adoption
- 4.2.4 Expansion of Aerospace, Medical and Semiconductor Manufacturing
- 4.2.5 Co-Optimization of Wheels, Machines and Process Parameters
- 4.3 Market Restraints
- 4.3.1 High Cost of Superabrasive Wheels and Specialized Dressing
- 4.3.2 Skilled Operator and Process-Engineering Shortages
- 4.3.3 Wheel-to-Wheel Variability in Semiconductor Consumable Qualification
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Cylindrical External Grinding Wheels
- 5.1.2 Internal Grinding Wheels
- 5.1.3 Surface Grinding Wheels
- 5.1.4 Centerless Grinding Wheels
- 5.2 By Material
- 5.2.1 Aluminum Oxide
- 5.2.2 Silicon Carbide
- 5.2.3 Cubic Boron Nitride
- 5.2.4 Diamond
- 5.2.5 Other Materials
- 5.3 By End-User Industry
- 5.3.1 Automotive
- 5.3.2 Aerospace and Defense
- 5.3.3 Metalworking and Fabrication
- 5.3.4 Bearing and Machinery Manufacturing
- 5.3.5 Semiconductor and Electronics
- 5.3.6 Other End-User Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 Asahi Diamond Industrial Co., Ltd.
- 6.4.3 August Ruggeberg GmbH & Co. KG
- 6.4.4 CUMI
- 6.4.5 Hindustan Abrasives
- 6.4.6 Klingspor AG
- 6.4.7 KREBS & RIEDEL Schleifscheibenfabrik GmbH & Co. KG
- 6.4.8 KURE GRINDING WHEE
- 6.4.9 LACH DIAMANT
- 6.4.10 NORITAKE CO., LIMITED
- 6.4.11 Saint-Gobain
- 6.4.12 SAK ABRASIVES LIMITED
- 6.4.13 Sterling Abrasives Limited
- 6.4.14 Tyrolit AG
- 6.4.15 Wendt (India) Limited
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

