PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154926

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154926
Water Adventure Tourism - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the global water adventure tourism market size stood at USD 72.17 billion in 2026, up from USD 69.02 billion in 2025, and is projected to reach USD 91.70 billion by 2031 at a 4.91% CAGR.
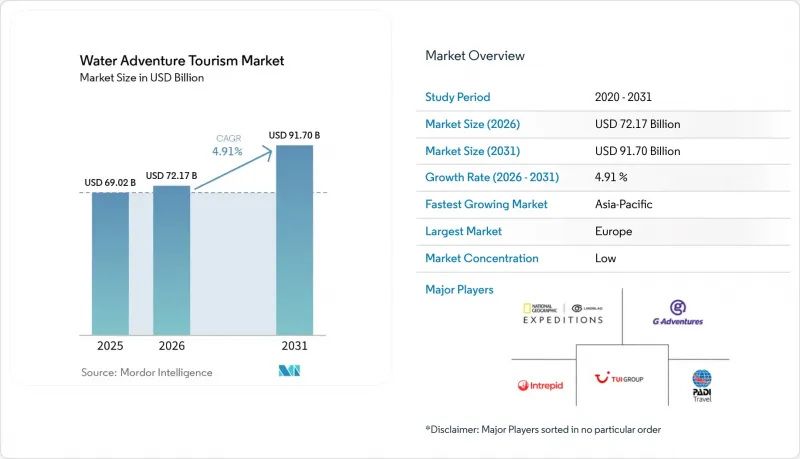
Global Water Adventure Tourism Market Trends and Insights
Experiential Travel Shift Toward Active Coastal Trips
Active travel has moved into the mainstream, helping the water adventure tourism market capture a larger share of leisure budgets. Hilton's 2025 Trends Report found that 70% of global travelers enjoy active travel, while 20% specifically planned outdoor adventure trips in 2025. That preference matters because coastal trips are no longer built around one landmark or one beach, but around a sequence of bookable experiences that can stretch spending across several days. Travelers increasingly seeking experiential vacations are driving stronger demand for adventure-led coastal itineraries and curated marine experiences. In the water adventure tourism market, this favors operators who can bundle paddling, snorkeling, sailing, and beginner-level underwater activities into a single itinerary. It also reduces the relative appeal of single-activity providers that cannot extend the guest journey beyond one short booking.
Social-Media-Led Discovery and Direct Mobile Booking
Social platforms now account for a large share of first contact in the water adventure tourism market, especially among younger travelers and those interested in visually oriented marine activities. Expedia Group's 2025 Traveler Value Index reported that 73% of travelers said influencer recommendations affected booking decisions, and that figure rose to 84% among travelers under 40. This shifts attention toward operators that can turn inspiration into a fast mobile booking with clear pricing and instant confirmation. It also supports shorter booking windows because travelers increasingly move from content discovery to transaction only after weather, timing, and destination details are clear. As a result, digital response speed is becoming as important as physical equipment quality for many providers in the water adventure tourism market. The growing influence of scuba and marine tourism content trending on social media is also increasing conversion rates for visually immersive travel experiences.
Weather Volatility and Shorter Reliable Operating Windows
Weather volatility is reducing the number of dependable operating days across many parts of the water adventure tourism market. This does not remove underlying demand, but it does make revenue less predictable because bookings move closer to the activity date, and operators face more cancellations, rescheduling, or partial-capacity days. The effect is strongest in destinations where monsoon cycles, storm seasons, or rough water conditions already narrow the commercial season. It also shifts premium demand toward destinations that can prove year-round reliability, such as the Red Sea, the Maldives, and the Canary Islands. In practice, operators with flexible inventory, quick rebooking policies, and a mix of activity types are better placed to protect occupancy when weather patterns turn less stable.
Other drivers and restraints analyzed in the detailed report include:
- Government and Resort Investment in Marine Recreation Infrastructure
- Safety Gear, Training, and Certification Widening First-Time Participation
- Coral Reef Degradation and Carrying-Capacity Caps at Iconic Sites
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Human-powered water adventure accounted for 25.8% of the water adventure tourism market in 2025, making it the largest activity group by value. The segment benefits from broad appeal because kayaking, canoeing, and paddleboarding fit a wide range of age groups, skill levels, and resort formats. It also faces fewer technical barriers than scuba diving or wind-based activities, making it easier for first-time travelers to add on during a short coastal trip. That accessibility supports repeat use across both destination holidays and domestic blue space recreation.
Underwater adventure is projected to grow at a 6.7% CAGR from 2026 to 2031, making it the fastest expanding activity type in the water adventure tourism market. PADI's 2025 network expansion and the strong value of the global diving certificate economy show that training infrastructure is continuing to widen the funnel for paid dive travel. The rest of the activity mix remains relevant, with wind and wave sports drawing loyal users, marine and sailing formats benefiting from premium, low-volume travel, and aerial or towed activities expanding through resort packages. White water and river formats add useful diversification by reducing dependence on beach-only demand and extending the water adventure tourism market's operating footprint inland.
Independent or FIT travelers accounted for 43.9% of the market in 2025, reflecting the self-directed roots of the water adventure tourism market. Certified divers, experienced paddlers, and repeat coastal travelers often prefer flexible scheduling and direct operator choice rather than prebuilt itineraries. This format also suits travelers who want to combine several activities across one trip without being tied to a group pace. As digital discovery improves, FIT travelers can compare operators more quickly and make more selective decisions about quality, safety, and location. That keeps the segment important for specialist providers with strong reviews, direct booking capability, and niche activity depth.
Package or organized travelers are forecast to grow at a 5.6% CAGR through 2031, indicating rising demand from travelers seeking convenience and lower planning friction. This segment benefits from resort-integrated activity menus, bundled marine excursions, and multi-stop holiday formats that make water experiences easier to access for new participants. It also aligns well with cruise-linked shore programs and family travel, where a single organizer often manages safety, timing, and transport. Group travel remains a meaningful middle layer in the water adventure tourism market because schools, youth programs, and institutional buyers often prefer structured oversight. Operators with clear safety documentation, trained staff, and dependable scheduling are likely to capture more of this organized demand as procurement standards become more formal.
Complete Report Scope:
- By Activity Type
- Underwater Adventure (Scuba Diving, Snorkeling, Underwater Sea Walking, etc.)
- Human-Powered Water Adventure (Kayaking, Canoeing, Paddleboarding, etc.)
- White-Water & River Adventure (Rafting, River Tubing, Boarding, etc.)
- Wind & Wave Adventure (Windsurfing, Kitesurfing)
- Motorized Water Adventure (Jet Skiing, Speed Boating, etc.)
- Aerial & Towed Water Adventure (Parasailing, Flyboarding, Towable Rides)
- Marine / Sailing Adventure (Sailing, Deep-Sea Fishing, Expedition Boat Tours)
- By Traveller Type
- Independent / FIT Travelers
- Group Travelers
- Package / Organized Travelers
- By End User
- Corporate / Institutional Adventure Trips
- Leisure / Recreational
- Professional / Training
- Corporate / Team-Building
- By Age Group
- Kids & Youth (Under 24 Years)
- Adults (25-44 Years)
- Middle-Age & Seniors (45+ Years)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
- Middle East And Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East And Africa
- North America
Geography Analysis
Europe accounted for 31.3% of the water adventure tourism market in 2025, making it the largest regional contributor. The region benefits from a dense mix of Mediterranean diving, Nordic Sea kayaking, Atlantic surf culture, and coastal sailing, which supports diverse activities year-round. The EU Blue Economy Report 2025 recorded more than 1.4 billion nights spent in EU coastal regions in 2023, up 6.4% year on year, which shows the depth of the region's coastal demand base. Europe also benefits from mature infrastructure and a broad base of short-haul travelers, which supports both beginner and repeat participation. North America remains a steady market within the global water adventure tourism market because it combines a large installed base in diving, paddling, and rafting with strong domestic trip potential.
Asia-Pacific is projected to grow at a 5.9% CAGR from 2026 to 2031, making it the fastest-growing regional cluster in the water adventure tourism market. Growth is spread across several destination types, including dive-led island systems, resort-based marine recreation, and premium sailing or liveaboard routes. Regional tourism bodies are also moving toward more structured marine development, as shown by the Pacific Tourism Organization and the Market Development Facility strategy work across Tonga, Samoa, Kiribati, and Fiji. Tonga's 2025 eco-tourism guidelines also show how fast-growing island destinations are pairing tourism growth with marine stewardship and community use rules. That combination of natural asset depth, rising infrastructure quality, and more formal operating frameworks supports the region's long runway in the water adventure tourism market.
The Middle East and Africa are gaining visibility in the water adventure tourism market because they offer year-round warm water, premium reef access, and a growing number of destination-led tourism projects. The Red Sea remains particularly important because it offers strong underwater visibility and year-round operating potential, helping offset weather disruptions seen in more seasonal markets. Africa's coastal and reef assets are also becoming more investable when operators can prove environmental management and site discipline. In Jordan, Green Fins reported that Aqaba's dive operators achieved a 51% reduction in environmental threats from marine tourism in the program's second year, which shows how sustainability verification can strengthen destination positioning. South America remains smaller in absolute terms, but it continues to attract expedition-oriented demand through distinct niches in river, coastal, and cold-water adventure formats, broadening the global reach of the water adventure tourism market.
- TUI Group
- G Adventures
- Intrepid Travel
- Lindblad Expeditions
- PADI Travel
- Aggressor Adventures
- Dive The World
- Dive Worldwide
- World Expeditions
- Mountain Travel Sobek
- Quark Expeditions
- Abercrombie & Kent
- Adventure Life
- Exodus Adventure Travels
- REI Travel
- Austin Adventures
- OARS
- ROW Adventures
- Western River Expeditions
- SwimTrek
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Experiential travel shift toward active coastal trips
- 4.2.2 Social-media-led discovery and direct mobile booking
- 4.2.3 Government and resort investment in marine recreation infrastructure
- 4.2.4 Safety gear, training, and certification widening first-time participation
- 4.2.5 Reef restoration and Green Fins standards lifting premium dive and snorkel demand
- 4.2.6 Cruise shore-excursion and beach-resort water-sports integration boosting ancillary spend
- 4.3 Market Restraints
- 4.3.1 Weather volatility and shorter reliable operating windows
- 4.3.2 Liability insurance and compliance costs for high-risk operators
- 4.3.3 Coral reef degradation and carrying-capacity caps at iconic sites
- 4.3.4 Fragmented coastal permits and community access conflicts
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Activity Type
- 5.1.1 Underwater Adventure (Scuba Diving, Snorkeling, Underwater Sea Walking, etc.)
- 5.1.2 Human-Powered Water Adventure (Kayaking, Canoeing, Paddleboarding, etc.)
- 5.1.3 White-Water & River Adventure (Rafting, River Tubing, Boarding, etc.)
- 5.1.4 Wind & Wave Adventure (Windsurfing, Kitesurfing)
- 5.1.5 Motorized Water Adventure (Jet Skiing, Speed Boating, etc.)
- 5.1.6 Aerial & Towed Water Adventure (Parasailing, Flyboarding, Towable Rides)
- 5.1.7 Marine / Sailing Adventure (Sailing, Deep-Sea Fishing, Expedition Boat Tours)
- 5.2 By Traveller Type
- 5.2.1 Independent / FIT Travelers
- 5.2.2 Group Travelers
- 5.2.3 Package / Organized Travelers
- 5.3 By End User
- 5.3.1 Corporate / Institutional Adventure Trips
- 5.3.2 Leisure / Recreational
- 5.3.3 Professional / Training
- 5.3.4 Corporate / Team-Building
- 5.4 By Age Group
- 5.4.1 Kids & Youth (Under 24 Years)
- 5.4.2 Adults (25-44 Years)
- 5.4.3 Middle-Age & Seniors (45+ Years)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Peru
- 5.5.2.3 Chile
- 5.5.2.4 Argentina
- 5.5.2.5 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 5.5.3.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.5.3.8 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 India
- 5.5.4.2 China
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East And Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Nigeria
- 5.5.5.5 Rest of Middle East And Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 TUI Group
- 6.4.2 G Adventures
- 6.4.3 Intrepid Travel
- 6.4.4 Lindblad Expeditions
- 6.4.5 PADI Travel
- 6.4.6 Aggressor Adventures
- 6.4.7 Dive The World
- 6.4.8 Dive Worldwide
- 6.4.9 World Expeditions
- 6.4.10 Mountain Travel Sobek
- 6.4.11 Quark Expeditions
- 6.4.12 Abercrombie & Kent
- 6.4.13 Adventure Life
- 6.4.14 Exodus Adventure Travels
- 6.4.15 REI Travel
- 6.4.16 Austin Adventures
- 6.4.17 OARS
- 6.4.18 ROW Adventures
- 6.4.19 Western River Expeditions
- 6.4.20 SwimTrek
7 Market Opportunities & Future Outlook
- 7.1 Regenerative reef and citizen-science water adventures
- 7.2 Safe year-round inland blue-space formats for families and shoulder seasons

