PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154952

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154952
South America Location Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
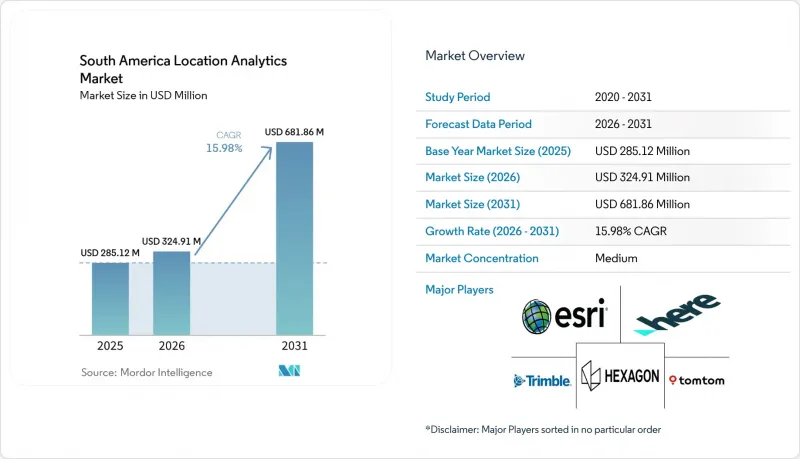
According to Mordor Intelligence, the South America location analytics market size was USD 285.12 million in 2025 and is estimated to increase from USD 324.91 million in 2026 to USD 681.86 million by 2031, at a CAGR of 15.98% during 2026-2031.
South America Location Analytics Market Trends and Insights
Enterprise Shift Toward Real-Time Spatial Decision Intelligence
The South America location analytics market is benefiting as operating teams require current location data rather than daily reports. Logistics, financial services, agribusiness, and public safety teams increasingly use location information when making decisions. Amazon Brazil launched quick-commerce operations across 8 cities in early 2026 and planned a 3-fold expansion by year's end, using location systems that adjust delivery areas through rider positions, inventory, and traffic signals. These operating models create a continuing requirement for data processing instead of a one-time mapping project. Vendors are therefore being assessed on response time, application programming interface performance, and the ability to support changing data feeds. This gives cloud-native platforms an advantage over systems designed mainly for batch processing.
Smart-City and Digital Infrastructure Investment
Smart-city programs and digital infrastructure are increasing the availability of data that can support the South America location analytics market. Rio de Janeiro City Hall announced a USD 550 million investment in the Rio AI City project in June 2026, as part of a program targeting USD 65 billion in investment over the following decade. The program is intended to position Rio de Janeiro among the 10 largest global AI hubs by 2032. Connected infrastructure generates data from sensors, cameras, and vehicles that can be used for urban planning, traffic management, and maintenance. Conecta Infra announced a USD 350 million plan in March 2026 to deploy 6,000 kilometers of fiber connecting Chile and Argentina with Brazil's main digital infrastructure hubs by 2028. These projects extend the networks needed to transmit location data and create demand for ongoing analytics services.
High Cost of Geospatial Data and Platform Deployment
High licensing, integration, and data-acquisition costs limit adoption in the South America location analytics market, especially among mid-sized organizations and public agencies. High-resolution satellite imagery can be costly for commercial users without public programs or co-investment. Integrating spatial systems with enterprise resource planning and customer relationship management platforms also requires specialized software, data remediation, and professional services. These requirements can extend the typical payback period for enterprise deployment to 2-3 years. Currency volatility in Argentina can raise the local-currency cost of USD-denominated licenses during a budget cycle. Consumption-based cloud services provide an alternative to perpetual licenses and can reduce the need to maintain specialized internal teams.
Other drivers and restraints analyzed in the detailed report include:
- Location-Based Retail, Logistics, and Mobility Optimization
- Expansion of Satellite, GNSS, Mobile, and IoT-Derived Data
- Data Privacy, Consent, and Cross-Border Transfer Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software held 59.31% of the South America location analytics market in 2025. This position reflected established GIS deployments in mapping agencies, telecommunications, oil and gas, financial services, and large enterprises. Long-standing commitments to systems such as Esri ArcGIS and Hexagon ERDAS continued to support software revenue. These platforms remain important where organizations require extensive mapping, data management, and governance capabilities.
Services are projected to expand at a 16.38% CAGR through 2031, the fastest rate within this segmentation. Buyers are increasingly purchasing analytical outcomes and managed delivery rather than only software licenses. The shortage of internal GIS specialists and the maintenance needs of AI-enabled models support this shift. Amazon Brazil's quick-commerce expansion relied on external routing optimization and geospatial modeling support rather than building all capabilities in-house. Foursquare introduced the FSQ Spatial Agent in 2026 to enable natural-language spatial queries without GIS expertise, lowering the barrier to recurring service consumption.
Reporting and visualization accounted for 28.83% of the South America location analytics market in 2025. Enterprise dashboard investment and thematic mapping supported this position in government, logistics, and financial services. Geocoding, reverse geocoding, data integration, extract-transform-load processes, thematic mapping, surface and field analytics, and geovisualization each address distinct stages of the spatial workflow. Basic visualization remains necessary because it makes location data understandable for non-specialist users.
Network and location analytics are projected to expand at a 17.38% CAGR through 2031. Enterprises are moving from descriptive maps toward predictive models for delivery networks, financial contagion corridors, and disease propagation pathways. This change reflects buyers' need to use spatial context directly in planning and operating systems. Mapping features within large business intelligence platforms could reduce the standalone value of visualization-only tools. Brazil's IBGE and SERPRO launched a national program in June 2025 to integrate fragmented public records into predictive analytical platforms. The initiative illustrates the demand for analytical systems that go beyond static reporting.
Complete Report Scope:
- By Offering
- Software
- Services
- By Solution and Analytics Type
- Data Integration and ETL
- Geocoding and Reverse Geocoding
- Reporting and Visualization
- Thematic Mapping and Spatial Analysis
- Network and Location Analytics
- Surface and Field Analytics
- Geovisualization
- By Deployment Mode
- Cloud
- On-Premises
- By Data and Sensing Modality
- GNSS and Satellite-Derived Location Data
- Mobile Network and Device-Derived Data
- Wi-Fi and BLE-Derived Data
- IoT and Sensor-Fusion Data
- By End User
- Retail and E-Commerce
- Automotive, Transportation, and Logistics
- BFSI
- Government and Defense
- Telecommunications
- Healthcare and Life Sciences
- Manufacturing and Industrial
- Other End User Industries
- By Organization Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By Geography
- Brazil
- Argentina
- Colombia
- Rest of South America
List of Companies Covered in this Report:
- Environmental Systems Research Institute, Inc.
- HERE Global B.V.
- TomTom N.V.
- Precisely, Inc.
- CARTO, Inc.
- Mapbox, Inc.
- Trimble Inc.
- Hexagon AB
- Bentley Systems, Incorporated
- Fugro N.V.
- Planet Labs PBC
- Maxar Intelligence Inc.
- Spire Global, Inc.
- BlackSky Technology Inc.
- Satellogic Inc.
- MDA Space Ltd.
- SuperMap Software Co., Ltd.
- Nearmap Ltd.
- SafeGraph Inc.
- Kongsberg Geospatial AS
- Orbital Insight, Inc.
- Foursquare Labs, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Enterprise Shift Toward Real-Time Spatial Decision Intelligence
- 4.2.2 Smart-City and Digital-Infrastructure Investment
- 4.2.3 Location-Based Retail, Logistics, and Mobility Optimization
- 4.2.4 Expansion of Satellite, GNSS, Mobile, and IoT-Derived Data
- 4.2.5 AI-Enabled Geospatial Modeling and Digital Twins
- 4.2.6 Fragmented Address and Mobility Data Creating Demand for Regional Data Products
- 4.3 Market Restraints
- 4.3.1 High Total Cost of Geospatial Data and Platform Deployment
- 4.3.2 Data Privacy, Consent, and Cross-Border Transfer Constraints
- 4.3.3 Fragmented Address Standards and Inconsistent Data Quality
- 4.3.4 Shortage of GIS, Data-Science, and Spatial-Engineering Talent
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Offering
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Solution and Analytics Type
- 5.2.1 Data Integration and ETL
- 5.2.2 Geocoding and Reverse Geocoding
- 5.2.3 Reporting and Visualization
- 5.2.4 Thematic Mapping and Spatial Analysis
- 5.2.5 Network and Location Analytics
- 5.2.6 Surface and Field Analytics
- 5.2.7 Geovisualization
- 5.3 By Deployment Mode
- 5.3.1 Cloud
- 5.3.2 On-Premises
- 5.4 By Data and Sensing Modality
- 5.4.1 GNSS and Satellite-Derived Location Data
- 5.4.2 Mobile Network and Device-Derived Data
- 5.4.3 Wi-Fi and BLE-Derived Data
- 5.4.4 IoT and Sensor-Fusion Data
- 5.5 By End User
- 5.5.1 Retail and E-Commerce
- 5.5.2 Automotive, Transportation, and Logistics
- 5.5.3 BFSI
- 5.5.4 Government and Defense
- 5.5.5 Telecommunications
- 5.5.6 Healthcare and Life Sciences
- 5.5.7 Manufacturing and Industrial
- 5.5.8 Other End User Industries
- 5.6 By Organization Size
- 5.6.1 Large Enterprises
- 5.6.2 Small and Medium-Sized Enterprises
- 5.7 By Geography
- 5.7.1 Brazil
- 5.7.2 Argentina
- 5.7.3 Colombia
- 5.7.4 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Environmental Systems Research Institute, Inc.
- 6.4.2 HERE Global B.V.
- 6.4.3 TomTom N.V.
- 6.4.4 Precisely, Inc.
- 6.4.5 CARTO, Inc.
- 6.4.6 Mapbox, Inc.
- 6.4.7 Trimble Inc.
- 6.4.8 Hexagon AB
- 6.4.9 Bentley Systems, Incorporated
- 6.4.10 Fugro N.V.
- 6.4.11 Planet Labs PBC
- 6.4.12 Maxar Intelligence Inc.
- 6.4.13 Spire Global, Inc.
- 6.4.14 BlackSky Technology Inc.
- 6.4.15 Satellogic Inc.
- 6.4.16 MDA Space Ltd.
- 6.4.17 SuperMap Software Co., Ltd.
- 6.4.18 Nearmap Ltd.
- 6.4.19 SafeGraph Inc.
- 6.4.20 Kongsberg Geospatial AS
- 6.4.21 Orbital Insight, Inc.
- 6.4.22 Foursquare Labs, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

