PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155290

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155290
Time-of-Flight Industrial Camera - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
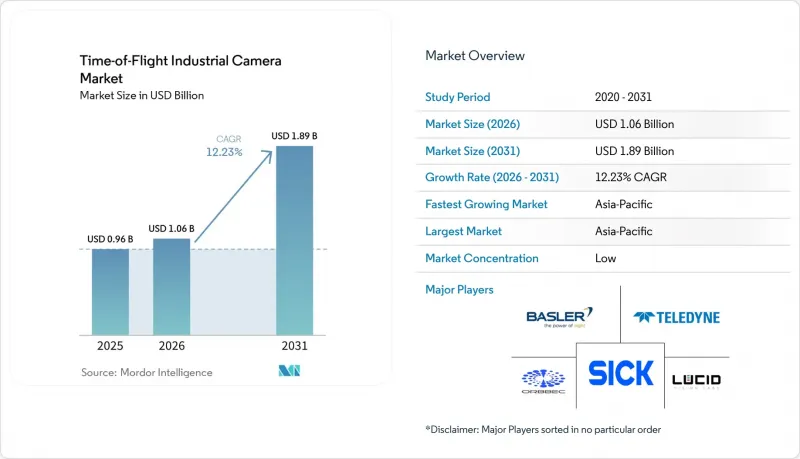
According to Mordor Intelligence, the time-of-flight industrial camera market size is projected to expand from USD 0.96 billion in 2025 to USD 1.06 billion in 2026, and to USD 1.89 billion by 2031, registering a CAGR of 12.23% between 2026 and 2031.
Global Time-of-Flight Industrial Camera Market Trends and Insights
Expansion of Warehouse Automation and Autonomous Mobile Robots
Warehouse automation is a central driver of demand for the Time-of-flight industrial camera market. Autonomous mobile robots need reliable depth information for obstacle avoidance, path planning, and movement around workers. ToF cameras are well-suited to close-range sensing because they rapidly generate three-dimensional occupancy data. This capability is useful in warehouses where lighting varies across aisles, loading areas, and storage zones. Each fleet expansion may require additional depth-sensing hardware, linking camera demand to equipment deployment. The Time-of-flight industrial camera market, therefore, benefits when logistics operators standardize perception hardware across larger robot fleets.
Industry 4.0 Adoption and Machine Vision Modernization
Manufacturers are updating inspection processes as older two-dimensional systems reach replacement cycles. A move from 2D inspection to depth-aware inspection often changes the workflow rather than simply replacing a camera. Production lines may require cameras, illumination, processing capacity, and software licenses simultaneously. This makes the purchase decision broader than a hardware selection. Established vendors are responding by pairing ToF sensing with software development kits and integration ecosystems. The Time-of-flight industrial camera market gains when modernization programs treat machine vision as a connected production system.
High Integration and Calibration Cost
A working machine-vision system requires more than installing a depth camera. Integrators must align the camera with robot coordinates and tune it for lighting and reflective surfaces. They must also account for drift in depth calibration as operating conditions change. These requirements can extend implementation timelines in smaller manufacturing sites. Brownfield facilities can face added mechanical and software work when existing conveyors and racking need custom interfaces. Pre-calibrated cameras and on-camera depth processing can reduce this burden for the Time-of-flight industrial camera market.
Other drivers and restraints analyzed in the detailed report include:
- Demand for Real-Time 3D Inspection and Dimensioning
- Growth of Edge AI Processing in Industrial Cameras
- Ambient-Light and Multipath-Interference Limits
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Standalone industrial ToF cameras held 48.62% of the Time-of-flight industrial camera market share in 2025. System integrators have favored modular designs that let them select camera hardware, illumination, computing, and software separately. This approach gives users flexibility when they have established technical preferences. It also lets an integrator tune the system for a specific working distance or object type. Embedded ToF modules serve a different need in compact robot applications. They fit collaborative robot end effectors, wrist-mounted perception equipment, and automated guided vehicle sensor clusters. These uses have strict limits on space, weight, and power. The Time-of-flight industrial camera market continues to depend on both modular and embedded hardware choices.
ToF camera systems and bundled vision solutions are projected to expand at a 14.36% CAGR from 2026 to 2031. Mid-sized manufacturers often place more value on commissioning speed than on the flexibility of separate components. Bundled systems can deliver calibrated depth, confidence, and intensity data through a defined interface. This reduces the number of decisions required during installation. IDS Imaging placed its Nion 3D ToF camera into series production in August 2026. The product combines an onsemi Hyperlux ID AF0130 sensor with on-chip processing and an IP67 housing. It provides 1.2 MP depth resolution at 30 fps and operates across a 0.3 to 7.5 meter range.
Indirect ToF commanded 61.47% of revenue in 2025. Its installed base reflects its use in indoor mobile robotics, bin picking, and logistics platforms. iToF systems use continuous-wave phase measurement to create dense depth maps. Current cameras cover working distances that suit close-range industrial handling tasks. Sony DepthSense and Infineon REAL3 sensor families support this type of deployment. Their operating profile is aligned with indoor environments where lighting can be controlled. The Time-of-flight industrial camera market size for iToF remains supported by broad compatibility with existing industrial designs.
Direct ToF is projected to expand at a 14.82% CAGR from 2026 to 2031. SPAD arrays measure the arrival time of photons from short laser pulses. This approach is relevant for long-range and high-ambient-light tasks. STMicroelectronics began mass production of the VL53L9 in July 2026. The module offers 2,268 resolution zones at 100 fps across a 5-centimeter to 9-meter sensing range. It produces output intended for edge processing in robotics and industrial automation. Research on SPAD array design also focuses on reducing die area and power requirements.
Complete Report Scope:
- By Product Type
- Standalone Industrial ToF Cameras
- Embedded ToF Camera Modules
- ToF Camera Systems and Bundled Vision Solutions
- By Technology
- Direct ToF (dToF)
- Indirect ToF (iToF)
- Hybrid ToF
- By Application
- Robotic Guidance and Bin Picking
- Autonomous Mobile Robot Navigation and Obstacle Avoidance
- Logistics Dimensioning, Weighing, and Scanning
- Inspection, Measurement, and Quality Control
- Human-Robot Safety and Monitoring
- Inventory, Fill-Level, and Volume Measurement
- Other Applications
- By End-User Industry
- Automotive
- Electronics and Semiconductor
- Food, Beverage, and Consumer Goods
- Logistics, Warehousing, and E-Commerce
- Metals, Machinery, and General Manufacturing
- Healthcare and Life Sciences Facilities
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific held 41.58% of the Time-of-flight industrial camera market share in 2025 and is projected to expand at a 14.28% CAGR through 2031. China supports demand through electronics, electric vehicle battery, and semiconductor factory activity. Depth sensing is used in automated handling, inspection, and intralogistics systems in these settings. Japan contributes through precision equipment and its machine-vision integration base. South Korean semiconductor and display operations also require demanding inspection processes. India is driving demand through electronics manufacturing, semiconductor activity, and mobile device assembly. Regional suppliers are building camera, sensor, software, and robotics capabilities within the same value chain. Goertek Microelectronics offers full-stack 3D ToF solutions for palletizing and depalletizing in logistics, e-commerce, food, and daily-chemicals applications.
North America is the second-largest region in the Time-of-flight industrial camera market. New manufacturing investment is supporting purchases of automation and machine-vision equipment. Logistics providers and e-commerce fulfillment operators deploy depth sensing for AMR navigation and parcel measurement. These buyers can install multiple systems within a single facility. Europe draws demand from German automotive and machinery producers. Safety requirements for collaborative robot environments also support demand for certified systems. GigE Vision 3.0 added RoCEv2 support for lower-latency image transfer in multi-camera environments.
South America remains an emerging area, with Brazil and Argentina as key demand locations. Automotive assembly and domestic e-commerce logistics create the clearest application base. Uneven factory digitalization and limited integration capacity can slow adoption. The Middle East is adding smart warehouse infrastructure in the United Arab Emirates and Saudi Arabia. These investments support autonomous material handling and related perception hardware. Africa is still in the early stages of adoption, with South Africa and Egypt as more active industrial hubs. Price sensitivity in many African applications favors lower-cost stereo and two-dimensional alternatives.
- Basler AG
- LUCID Vision Labs, Inc.
- Orbbec Inc.
- Pmdtechnologies gmbh
- IFM Electronic GmbH
- Teledyne Vision Solutions
- IDS Imaging Development Systems GmbH
- Allied Vision Technologies GmbH
- SICK AG
- Baumer Holding AG
- Cognex Corporation
- KEYENCE CORPORATION
- Hikrobot Co., Ltd.
- Mech-Mind Robotics Technologies Co., Ltd.
- Semiconductor Components Industries, LLC
- Photoneo s. r. o.
- STMicroelectronics
- ESPROS Photonics Corporation
- Domi Sensor Technology Co., Ltd.
- Goertek Microelectronics Inc.
- TOPPAN INC.
- BECOM Systems GmbH
- MESA Imaging AG
- Nerian Vision GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Warehouse Automation and Autonomous Mobile Robots
- 4.2.2 Industry 4.0 Adoption and Machine-Vision Modernization
- 4.2.3 Demand for Real-Time 3D Inspection and Dimensioning
- 4.2.4 Growth of Edge AI Processing in Industrial Cameras
- 4.2.5 Rising Need for Outdoor-Capable Robot Perception
- 4.2.6 Standardization of GigE Vision, GenICam, and ROS Integration
- 4.3 Market Restraints
- 4.3.1 High Integration and Calibration Cost
- 4.3.2 Ambient-Light and Multipath-Interference Limits
- 4.3.3 Availability of Lower-Cost Stereo and Structured-Light Alternatives
- 4.3.4 Interference and Eye-Safety Constraints in Dense Multi-Camera Deployments
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Supply-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Standalone Industrial ToF Cameras
- 5.1.2 Embedded ToF Camera Modules
- 5.1.3 ToF Camera Systems and Bundled Vision Solutions
- 5.2 By Technology
- 5.2.1 Direct ToF (dToF)
- 5.2.2 Indirect ToF (iToF)
- 5.2.3 Hybrid ToF
- 5.3 By Application
- 5.3.1 Robotic Guidance and Bin Picking
- 5.3.2 Autonomous Mobile Robot Navigation and Obstacle Avoidance
- 5.3.3 Logistics Dimensioning, Weighing, and Scanning
- 5.3.4 Inspection, Measurement, and Quality Control
- 5.3.5 Human-Robot Safety and Monitoring
- 5.3.6 Inventory, Fill-Level, and Volume Measurement
- 5.3.7 Other Applications
- 5.4 By End-User Industry
- 5.4.1 Automotive
- 5.4.2 Electronics and Semiconductor
- 5.4.3 Food, Beverage, and Consumer Goods
- 5.4.4 Logistics, Warehousing, and E-Commerce
- 5.4.5 Metals, Machinery, and General Manufacturing
- 5.4.6 Healthcare and Life Sciences Facilities
- 5.4.7 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Egypt
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Basler AG
- 6.4.2 LUCID Vision Labs, Inc.
- 6.4.3 Orbbec Inc.
- 6.4.4 Pmdtechnologies gmbh
- 6.4.5 IFM Electronic GmbH
- 6.4.6 Teledyne Vision Solutions
- 6.4.7 IDS Imaging Development Systems GmbH
- 6.4.8 Allied Vision Technologies GmbH
- 6.4.9 SICK AG
- 6.4.10 Baumer Holding AG
- 6.4.11 Cognex Corporation
- 6.4.12 KEYENCE CORPORATION
- 6.4.13 Hikrobot Co., Ltd.
- 6.4.14 Mech-Mind Robotics Technologies Co., Ltd.
- 6.4.15 Semiconductor Components Industries, LLC
- 6.4.16 Photoneo s. r. o.
- 6.4.17 STMicroelectronics
- 6.4.18 ESPROS Photonics Corporation
- 6.4.19 Domi Sensor Technology Co., Ltd.
- 6.4.20 Goertek Microelectronics Inc.
- 6.4.21 TOPPAN INC.
- 6.4.22 BECOM Systems GmbH
- 6.4.23 MESA Imaging AG
- 6.4.24 Nerian Vision GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

