PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155545

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155545
Phenolic Antioxidant - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the phenolic antioxidant market size was valued at USD 2.43 billion in 2025 and is estimated to grow from USD 2.56 billion in 2026 to reach USD 3.34 billion by 2031, at a CAGR of 5.45% during the forecast period (2026-2031).
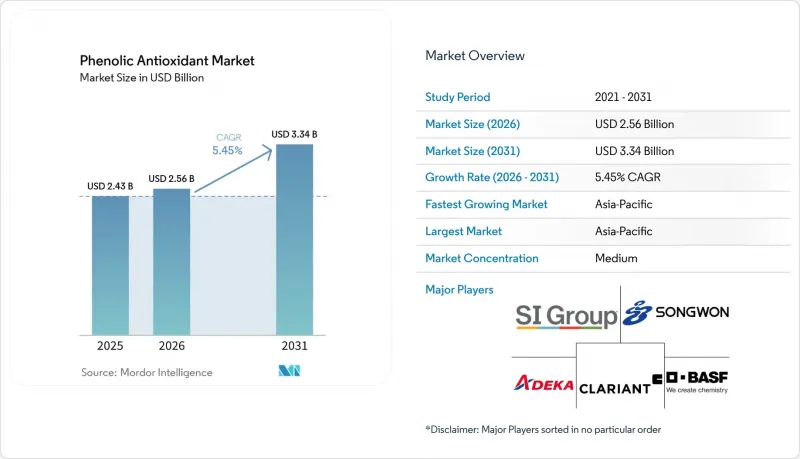
Global Phenolic Antioxidant Market Trends and Insights
Polymer Lightweighting and Electric-Vehicle Adoption
The phenolic antioxidant market benefits from polymer-intensive electric-vehicle platforms beyond battery housing applications. High-voltage cable insulation requires stabilization systems that can withstand continuous operating temperatures of 150 °C. Antioxidant loadings in these automotive compounds can reach 0.15% by weight. Original equipment manufacturers are qualifying polypropylene and thermoplastic elastomer insulation systems in place of polyvinyl chloride (PVC) in some applications. These material changes require higher antioxidant loading per kilogram of polymer and expand demand beyond vehicle production growth. Cable compounders are also reformulating for new electric-vehicle specifications, which favors suppliers that can support specialty grades.
Processed-Food Shelf-Life Extension
The phenolic antioxidant market is being reshaped by food manufacturers that are reviewing legacy butylated hydroxyanisole (BHA) and butylated hydroxytoluene (BHT) use. The U.S. Food and Drug Administration (FDA) began a post-market reassessment of BHA on February 10, 2026. The FDA then published a request for information on BHT in May 2026. These reviews are redirecting formulation activity toward approved high-purity phenolic chemistries and natural alternatives, including rosemary extract and mixed tocopherols. Food suppliers that can provide complete toxicology documentation and validated replacements are better positioned to respond to reformulation needs. The resulting demand is centered on product substitution rather than a broad reduction in antioxidant use.
Regulatory Scrutiny of Synthetic Phenolics
Regulatory scrutiny is a near-term restraint for food-grade synthetic phenolics. The FDA reassessed BHA in February 2026 and opened a BHT review in May 2026. The European Commission's Scientific Committee on Consumer Safety published a scientific opinion on BHA in April 2026. State actions in Texas, Louisiana, and West Virginia add to the policy pressure around BHA in food. The effect is narrower for polymer-grade products because those materials operate under separate compliance systems. Suppliers with food-grade and polymer-grade portfolios can therefore manage a more varied regulatory position than suppliers focused only on food additives.
Other drivers and restraints analyzed in the detailed report include:
- Recycled Polyolefin Stabilization Requirements
- Growth in Fuel, Lubricant, and Biodiesel Applications
- Feedstock Price and Supply Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Synthetic accounted for 62.31% of the revenue in 2025. They remained important in polymer processing, lubricant stabilization, and industrial applications where cost efficiency and performance at processing temperatures guide procurement. Synthetic hindered phenolics retain a cost advantage in high-volume polymer compounding. Antioxidant loading is measured in parts per million across large polymer production runs, making unit-price differences significant. Natural is projected to advance at a 5.79% CAGR through 2031. Clean-label expectations and efforts to remove BHA and BHT from ingredient lists support this growth in food and feed uses.
Natural products are gaining wider use in food, personal care, and pharmaceutical formulations. Synthetic is also being upgraded for polymer applications that must meet food-contact and chemical compliance requirements. The European Union update to Regulation (EC) No 1333/2008 in August 2026 added requirements that affect documentation and third-party testing for natural antioxidant exports. This requirement can favor suppliers with sufficient compliance resources over smaller extractors. It may slow supply-chain entry even while the underlying demand for natural options remains strong. Suppliers with both synthetic and natural portfolios can serve the different requirements of these end uses.
Mono-functional held 38.05% of the revenue in 2025. These products are widely used in standard polyolefin, rubber, and lubricant formulations where single-mechanism oxidative protection meets technical needs. Their cost profile remains relevant to high-volume polypropylene and polyethylene compounding in the Asia-Pacific. Qualified formulations are not changed easily without a clear performance reason. Bi-functional grades support applications that need primary and secondary stabilization without the higher complexity of multi-functional blends. Rubber and engineering thermoplastics are important end uses for these products.
Multi-functional is projected to advance at a 6.33% CAGR through 2031. Formulators are adopting integrated additive packages that address processing stability, service life, and discoloration control in a single product. Research from the Fraunhofer Institute found that phenyl propionates performed better in polypropylene extrusion than single-mechanism alternatives. Their bimolecular disproportionation mechanism enables antioxidant regeneration and forms additional stabilizing compounds during processing. Electric-vehicle polymer compounds and medical-device plastics reinforce demand for these grades because they need stability through demanding processing cycles.
Complete Report Scope:
- By Source
- Synthetic
- Natural
- By Type
- Mono-Functional
- Bi-Functional
- Multi-Functional
- By Form
- Powder
- Granule
- Liquid
- By Application
- Plastics and Rubber
- Food and Feed Additives
- Pharmaceuticals
- Personal Care
- Fuel and Lubricants
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 36.63% of the market revenue in 2025 and is projected to advance at a 5.84% CAGR through 2031. The phenolic antioxidant market in the region is supported by major polyolefin compounding capacity and electric-vehicle production. China accounts for much regional consumption through these activities. Chinese suppliers also export standard-grade products across Southeast Asia, maintaining pressure on regional pricing. Japan contributes demand for specification-grade additives used in lightweight materials for electric and hybrid vehicles. South Korea's automotive polymer supplier base supports demand for products with stringent thermal-stability certifications. India offers a growing opportunity as manufacturing programs and plastics processing expand.
North America and Europe have matured but have changing demand patterns. FDA reviews of BHA and BHT are moving food-ingredient demand toward other phenolic chemistries. Higher recycled-polyolefin volumes also raise the need for stabilization during processing. Europe has a substantial recycling base, and recycled materials can need 1.3 to 1.6 times the antioxidant loading of virgin-grade resins. BASF announced an expansion of standard hindered amine light stabilizer (HALS) and NOR HALS capacity in April 2026 to support demand in high-performance plastics and China's plasticulture sector. Germany remains an important center for premium grades used in automotive and industrial polymer applications.
South America and Middle East and Africa are developing use areas for fuel, lubricant, and polymer-grade products. Brazil's B15 biodiesel blend requirement and Argentina's soy-based biodiesel production support demand for fuel stabilization. Saudi Arabia's petrochemical capacity expansion supports domestic consumption of polymer and lubricant additives. South Africa remains a distribution point for specialty antioxidants in Sub-Saharan Africa. Infrastructure and construction polymers are expected to support the addressable base through the forecast period. These geographies add demand diversity to the phenolic antioxidant market.
- 3V Sigma S.p.A.
- ADEKA CORPORATION
- BASF
- CLARIANT
- Dover Chemical Corporation
- Eastman Chemical Company
- Everspring Chemical Co., Ltd.
- Evonik Industries AG
- LANXESS
- Oxiris Chemicals S.A.
- Rianlon Corporation
- SI Group, Inc.
- SONGWON
- Sumitomo Chemical Co., Ltd.
- Syensqo
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Processed-Food Shelf-Life Extension
- 4.2.2 Polymer Lightweighting and Electric-Vehicle Adoption
- 4.2.3 Recycled Polyolefin Stabilization Requirements
- 4.2.4 Growth in Fuel, Lubricant, and Biodiesel Applications
- 4.2.5 Clean-Label and Plant-Derived Formulation Demand
- 4.2.6 Encapsulation and Delivery-System Improvements
- 4.3 Market Restraints
- 4.3.1 Regulatory Scrutiny of Synthetic Phenolics
- 4.3.2 Feedstock Price and Supply Volatility
- 4.3.3 Additive Proliferation Complicating Polymer Recycling
- 4.3.4 Limited Toxicology and Migration Data for Near-Duplicate Molecules
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Source
- 5.1.1 Synthetic
- 5.1.2 Natural
- 5.2 By Type
- 5.2.1 Mono-Functional
- 5.2.2 Bi-Functional
- 5.2.3 Multi-Functional
- 5.3 By Form
- 5.3.1 Powder
- 5.3.2 Granule
- 5.3.3 Liquid
- 5.4 By Application
- 5.4.1 Plastics and Rubber
- 5.4.2 Food and Feed Additives
- 5.4.3 Pharmaceuticals
- 5.4.4 Personal Care
- 5.4.5 Fuel and Lubricants
- 5.4.6 Other Applications
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3V Sigma S.p.A.
- 6.4.2 ADEKA CORPORATION
- 6.4.3 BASF
- 6.4.4 CLARIANT
- 6.4.5 Dover Chemical Corporation
- 6.4.6 Eastman Chemical Company
- 6.4.7 Everspring Chemical Co., Ltd.
- 6.4.8 Evonik Industries AG
- 6.4.9 LANXESS
- 6.4.10 Oxiris Chemicals S.A.
- 6.4.11 Rianlon Corporation
- 6.4.12 SI Group, Inc.
- 6.4.13 SONGWON
- 6.4.14 Sumitomo Chemical Co., Ltd.
- 6.4.15 Syensqo
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

