PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155554

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155554
Pink Hydrogen - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
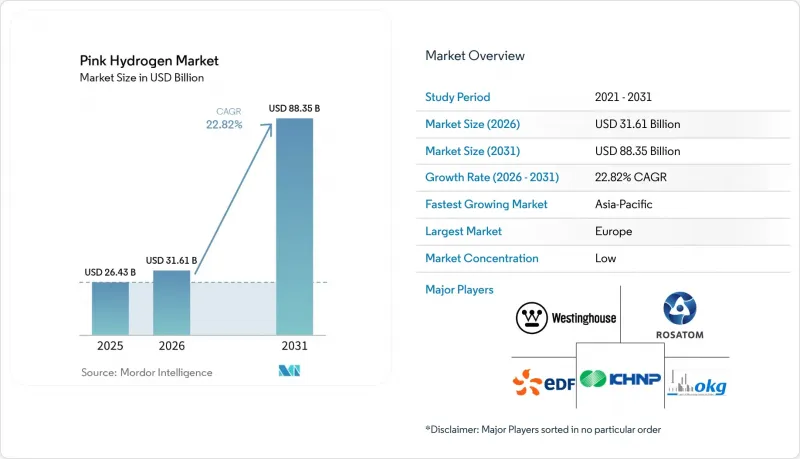
According to Mordor Intelligence, the pink hydrogen market size was valued at USD 26.43 billion in 2025 and is estimated to grow from USD 31.61 billion in 2026 to reach USD 88.35 billion by 2031, at a CAGR of 22.82% during the forecast period (2026-2031).
Global Pink Hydrogen Market Trends and Insights
Nuclear Power Availability for Continuous Electrolysis
Nuclear power enables electrolyzers to operate at utilization rates above 90%, supporting steady hydrogen output. This operating pattern spreads equipment costs across a larger production output than intermittent power sources can support. A U.S. Gulf Coast assessment found that nuclear-integrated hydrogen can become competitive under Section 45V credits at a hydrogen price of USD 2.50/kg and electricity prices ranging from USD 32.86/MWh to USD 60/MWh. Reactor heat can also support solid oxide electrolysis, reducing electricity use compared with systems that rely solely on electrical input. EDF reports that thermal coupling can improve hydrogen yield by 20% to 30% compared with Proton Exchange Membrane (PEM) and alkaline alternatives. These operating characteristics provide the pink hydrogen market with a path to continuous output for refinery-scale operations without relying on large storage buffers.
Government Clean-Hydrogen Funding and Net-Zero Policies
The United States finalized rules for the Section 45V clean hydrogen production credit in January 2025. The program provides an incentive of up to USD 3.00/kg for hydrogen that meets the lowest carbon-intensity threshold. The rules include eligibility pathways for qualifying merchant reactors, restarted reactors, and reactors receiving power uprates. The European Commission introduced its Small Modular Reactor (SMR) strategy in March 2026 and proposed SMR Valleys that can cluster hydrogen, ammonia, and synthetic fuel production near new reactor sites. The United Kingdom launched its Advanced Nuclear Framework in February 2025 to support planning, regulation, and fuel supply processes for advanced reactor projects. Together, these measures improve investment conditions for the pink hydrogen market by reducing uncertainty across reactor and electrolyzer development.
High Nuclear and Electrolysis Capital Requirements
Pink hydrogen projects require investment in reactor capacity, electrolyzers, storage, and connecting infrastructure before revenue begins. Proton Exchange Membrane (PEM) installations in Europe cost USD 2,000/kW to USD 2,550/kW. A 2026 study found that balance-of-plant capital for PEM systems fell from USD 848/kW at 1 MW to USD 87/kW at 1 GW, demonstrating the role of scale in lowering costs. Large reactors can cost more than USD 6 billion per unit, adding another layer of capital expenditure to co-located projects. Long-term offtake contracts are therefore important for recovering investment across the pink hydrogen market. Compliance with International Electrotechnical Commission (IEC) electrolyzer standards and Nuclear Regulatory Commission requirements adds preparation work and upfront expense.
Other drivers and restraints analyzed in the detailed report include:
- Decarbonization of Refining and Chemical Hydrogen Demand
- Hydrogen Demand from Steel, Heavy Transport, and Energy Storage
- Limited Nuclear Fleet and Project-Siting Availability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PEM electrolysis accounted for 49.34% of the pink hydrogen market share in 2025. This position reflects operating reliability, established component supply chains, and compatibility with existing nuclear output profiles. PEM systems can manage varying electrical loads when nuclear stations follow grid demand, making the technology practical for operators seeking commercial deployment without specialized heat integration. In February 2025, Korea Hydro & Nuclear Power Co., Ltd. (KHNP) partnered with Nel ASA to combine alkaline technology with nuclear power. This collaboration followed KHNP's national demonstration program, which began in April 2024. Alkaline systems remain relevant as a lower-capital option for large installations. The pink hydrogen market, therefore, has more than one process route available for early deployment.
Solid oxide electrolysis is projected to grow at a CAGR of 23.56% through 2031. This process uses high-temperature steam from reactor heat exchangers and can reduce the electrical input required for hydrogen production. EDF estimates that reactor heat integration can raise hydrogen yield by 20% to 30% compared with low-temperature systems. A 2026 study evaluated intermediate-temperature solid oxide electrolysis supplied with high-temperature reactor steam. KHNP presented preliminary work on process-heat capacity and potential demonstration sites at its July 2026 K-SOC symposium. The process remains less established than Proton Exchange Membrane (PEM) for commercial projects. However, its energy profile is suited to nuclear systems that can supply steady heat. This gives the pink hydrogen market a technology option focused on higher system efficiency and explains why process selection will depend on reactor configuration and project timeline.
Complete Report Scope:
- By Process
- PEM Electrolysis
- Alkaline Electrolysis
- Solid Oxide Electrolysis
- By Form
- Gaseous Hydrogen
- Liquid Hydrogen
- By End-User Industry
- Refinery
- Ammonia Production
- Methanol Production
- Steel Production
- Transport
- Cement Industry
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Europe accounted for 58.38% of the pink hydrogen market share in 2025. France plays a central role in the region, with its 56-reactor fleet providing substantial nuclear generation capacity. France's Multi-Year Energy Plan 3 (PPE3) for 2026 to 2035 sets a nuclear production target of 380-420 TWh annually. In July 2026, EDF signed its first Nuclear Production Allocation Contract with H4 Marseille Fos. The agreement allocates 150 MW of nuclear capacity for 10 years, starting in 2032, to power a EUR 1.6 billion (USD 1.85 billion) electro-Sustainable Aviation Fuel (e-SAF) facility. EDF is also assessing solid oxide electrolysis at its Bay Hydrogen Hub near Heysham. France and Poland support low-carbon recognition for nuclear hydrogen, while the European Commission has deferred formal classification until July 2028. Sweden and Finland also have nuclear capacity that could support certified production if the classification is resolved.
Asia-Pacific is expected to grow at a CAGR of 24.18% through 2031. South Korea's program includes KHNP's national nuclear hydrogen research project, which has operated since April 2024 with 8 industrial partners. The pilot facility is targeted for completion in 2027. KHNP's July 2026 K-SOC council linked research among industry, academia, and national laboratories. Japan is developing liquid hydrogen infrastructure at the Kawasaki LH2 Terminal in Ogishima. The project includes a 50,000-cubic-meter storage tank and is paired with the January 2026 carrier contract. The Japan Atomic Energy Agency filed a regulatory review application in March 2025 for a hydrogen facility at the High Temperature Engineering Test Reactor. India inaugurated a copper-chlorine thermochemical cycle hydrogen facility at Kalpakkam in June 2026, adding a non-electrolytic route to the regional production base.
- EDF
- Korea Hydro & Nuclear Power (KHNP)
- NuScale Power Corporation
- OKG Aktiebolag
- Rolls-Royce SMR Limited
- Rosatom State Atomic Energy Corporation
- Westinghouse Electric Company LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Nuclear Power Availability for Continuous Electrolysis
- 4.2.2 Government Clean-Hydrogen Funding and Net-Zero Policies
- 4.2.3 Decarbonization of Refining and Chemical Hydrogen Demand
- 4.2.4 Hydrogen Demand from Steel, Heavy Transport and Energy Storage
- 4.2.5 Monetization of Nuclear Power Surplus and Curtailment Periods
- 4.3 Market Restraints
- 4.3.1 High Nuclear and Electrolyzer Capital Requirements
- 4.3.2 Limited Nuclear Fleet and Project-Siting Availability
- 4.3.3 Nuclear-Hydrogen Licensing Interface and Safety Case Complexity
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Process
- 5.1.1 PEM Electrolysis
- 5.1.2 Alkaline Electrolysis
- 5.1.3 Solid Oxide Electrolysis
- 5.2 By Form
- 5.2.1 Gaseous Hydrogen
- 5.2.2 Liquid Hydrogen
- 5.3 By End-User Industry
- 5.3.1 Refinery
- 5.3.2 Ammonia Production
- 5.3.3 Methanol Production
- 5.3.4 Steel Production
- 5.3.5 Transport
- 5.3.6 Cement Industry
- 5.3.7 Others
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 EDF
- 6.4.2 Korea Hydro & Nuclear Power (KHNP)
- 6.4.3 NuScale Power Corporation
- 6.4.4 OKG Aktiebolag
- 6.4.5 Rolls-Royce SMR Limited
- 6.4.6 Rosatom State Atomic Energy Corporation
- 6.4.7 Westinghouse Electric Company LLC
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

