PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157139

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157139
Specialty Polystyrene Resin - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
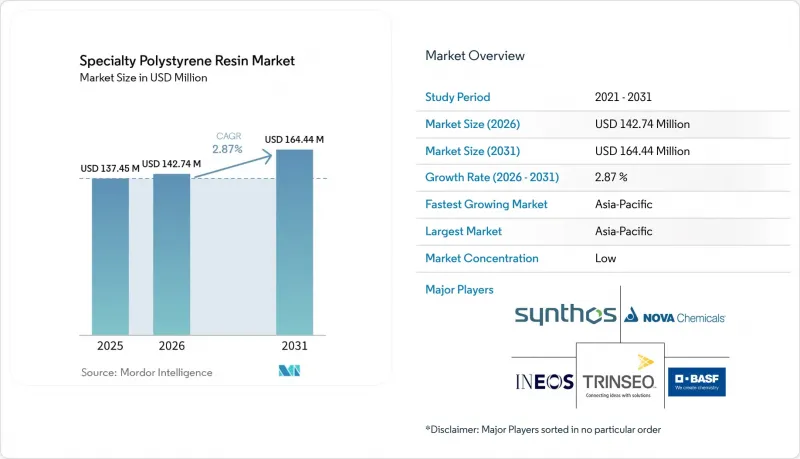
According to Mordor Intelligence, the specialty polystyrene resin market size was valued at USD 137.45 million in 2025 and is estimated to grow from USD 142.74 million in 2026 to reach USD 164.44 million by 2031, at a CAGR of 2.87% during the forecast period (2026-2031).
Global Specialty Polystyrene Resin Market Trends and Insights
Growth in Protective and Thermal Packaging Demand
Protective and thermal packaging supports demand for specialty expanded polystyrene (EPS) as direct-to-consumer distribution increases handling requirements for fragile and temperature-sensitive goods. Electronics, appliances, and industrial components require molded inserts with controlled shock absorption, differentiating specialty grades from standard bulk foam. The specialty polystyrene resin market also benefits from distributors' need for lightweight, insulated packaging for last-mile delivery and air freight. Graphite-enhanced EPS provides thermal performance with thinner walls, reducing package weight while maintaining the required thermal payload. Japan recorded 111,000 tons of EPS shipments in 2025, with fisheries, agriculture, and protective logistics accounting for most shipments. This shipment pattern indicates that protective containers and cold-box applications remain relevant, even as electronics conversion slows.
Energy-Efficiency Requirements in Buildings
Building energy codes make insulation-grade specialty polystyrene resin a specified material rather than a discretionary construction input. The recast Energy Performance of Buildings Directive requires EU member states to establish minimum energy performance standards for new buildings and major renovations. These requirements support renovation activity across Europe's aging building stock and generate recurring demand for insulation materials. Japan's construction-material EPS shipments totaled 16,332 tons in 2025, an increase of 100.5% from the previous year, as highly insulated housing specifications gained adoption. BASF states that Neopor provides up to 30% better insulation performance per unit thickness than standard white EPS and is adding 55,116 tons of annual capacity at Ludwigshafen, with start-up targeted for early 2027. These factors enable the specialty polystyrene resin market to capture higher resin value in applications where insulation performance is more important than material use.
Single-Use Plastic Restrictions and Waste-Management Requirements
Restrictions on single-use expanded polystyrene (EPS) have reduced demand from large-scale foodservice applications and increased compliance costs for converters. By May 2025, at least 12 U.S. states had enacted statewide bans on EPS foodware, and New York extended its prohibition to polystyrene cold-storage containers effective January 1, 2026. The European Union has restricted the use of expanded polystyrene food and beverage containers under the Single-Use Plastics Directive since 2021. The Packaging and Packaging Waste Regulation took effect across the EU on August 12, 2026, introducing recyclability requirements and phasing in recycled-content obligations by 2030. Lower foodservice demand may shift producer capacity toward insulation and healthcare grades, potentially affecting specialty-material pricing. However, gaps in low-density EPS collection remain a constraint, as recycled-grade supply depends on adequate collection density and sorting capabilities.
Other drivers and restraints analyzed in the detailed report include:
- Healthcare and Cold-Chain Packaging Adoption
- Lightweighting and Impact-Performance Requirements in Transportation
- Volatile Styrene and Hydrocarbon Feedstock Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Protection accounted for 42.34% of the specialty polystyrene resin market share in 2025, making it the largest functional category. The specialty polystyrene resin market for protection is projected to expand at a CAGR of 3.24% from 2026 to 2031. This position reflects demand for shock-absorbing materials in protective packaging and safety-related transportation components. Specialty EPS protection grades are replacing alternative materials in applications that require precise weight, density, and energy-absorption characteristics. The category also benefits from the shift from bulk foam grades to precision-molded products, which can support higher value realization.
Cushioning grades primarily serve the electronics and appliances industries, where pack-out specifications require dimensional accuracy and high surface quality. These requirements differentiate specialty materials from commodity resin grades used in less demanding applications. Other functional applications include EPS geofoam for civil engineering, lightweight architectural profiles, and specialty horticultural containers. The functional mix is also shifting toward gray and recycled-content variants as brands incorporate sustainability requirements into procurement specifications. This shift can sustain per-unit resin value, even when demand growth remains limited.
Complete Report Scope:
- By Function
- Protection
- Insulation
- Cushioning
- Other Functions
- By Application
- Protective Packaging
- Building and Construction
- Automotive and Transportation
- Electrical and Electronics
- Healthcare
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 39.41% of the specialty polystyrene resin market share in 2025 and is projected to expand at a CAGR of 3.31% through 2031. China remains the primary national demand center, supported by applications in e-commerce, protective packaging, and construction insulation. Although commodity polystyrene oversupply has weakened overall pricing, performance grades continue to see demand from sectors where multinational brands and healthcare supply chains require qualified materials. India also contributes to demand through residential construction and energy-efficient housing projects.
North America and Europe are mature markets with distinct regulatory frameworks and construction demand patterns. In the United States, foodservice restrictions are reducing demand for commodity grades, while energy-efficient home programs support demand for insulation grades. The European specialty polystyrene resin market is supported by requirements under the Energy Performance of Buildings Directive (EPBD) and the use of Expanded Polystyrene (EPS) in external thermal insulation composite systems. European Manufacturers of EPS (EUMEPS) identifies EPS-based external thermal insulation composite systems as a means of reducing thermal bridges and heating demand. The Packaging and Packaging Waste Regulation is also increasing the importance of recycled-content and recyclability requirements in European packaging procurement.
South America, the Middle East, and Africa represent smaller demand regions for specialty resin grades. Brazil and Argentina support demand for construction insulation and protective packaging as awareness of residential energy efficiency and e-commerce adoption increases. Saudi Arabia's construction activity supports demand as insulation specifications continue to evolve. In South Africa, the pharmaceutical distribution network supports demand for validated cold-chain shippers in the specialty polystyrene resin market.
- Americas Styrenics LLC (AmSty)
- BASF
- BEWI
- Epsilyte
- INEOS
- KANEKA CORPORATION
- LG Chem
- NOVA Chemicals Corporate
- SEKISUI CHEMICAL CO., LTD.
- SUNPOR Kunststoff GmbH
- Synthos
- Taita Chemical Co., Ltd.
- TotalEnergies
- Trinseo
- Versalis S.p.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in Protective and Thermal Packaging Demand
- 4.2.2 Energy-Efficiency Requirements in Buildings
- 4.2.3 Healthcare and Cold-Chain Packaging Adoption
- 4.2.4 Lightweighting and Impact-Performance Requirements in Transportation
- 4.2.5 Recycled-Content Qualification for Food-Contact and Medical Grades
- 4.3 Market Restraints
- 4.3.1 Single-Use Plastic Restrictions and Waste-Management Requirements
- 4.3.2 Volatile Styrene and Hydrocarbon Feedstock Costs
- 4.3.3 Collection Density Gaps for Low-Density EPS and Specialty-Grade Recycling
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Function
- 5.1.1 Protection
- 5.1.2 Insulation
- 5.1.3 Cushioning
- 5.1.4 Other Functions
- 5.2 By Application
- 5.2.1 Protective Packaging
- 5.2.2 Building and Construction
- 5.2.3 Automotive and Transportation
- 5.2.4 Electrical and Electronics
- 5.2.5 Healthcare
- 5.2.6 Other Applications
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Americas Styrenics LLC (AmSty)
- 6.4.2 BASF
- 6.4.3 BEWI
- 6.4.4 Epsilyte
- 6.4.5 INEOS
- 6.4.6 KANEKA CORPORATION
- 6.4.7 LG Chem
- 6.4.8 NOVA Chemicals Corporate
- 6.4.9 SEKISUI CHEMICAL CO., LTD.
- 6.4.10 SUNPOR Kunststoff GmbH
- 6.4.11 Synthos
- 6.4.12 Taita Chemical Co., Ltd.
- 6.4.13 TotalEnergies
- 6.4.14 Trinseo
- 6.4.15 Versalis S.p.A.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

