PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2163329

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2163329
South America Inflight Catering - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
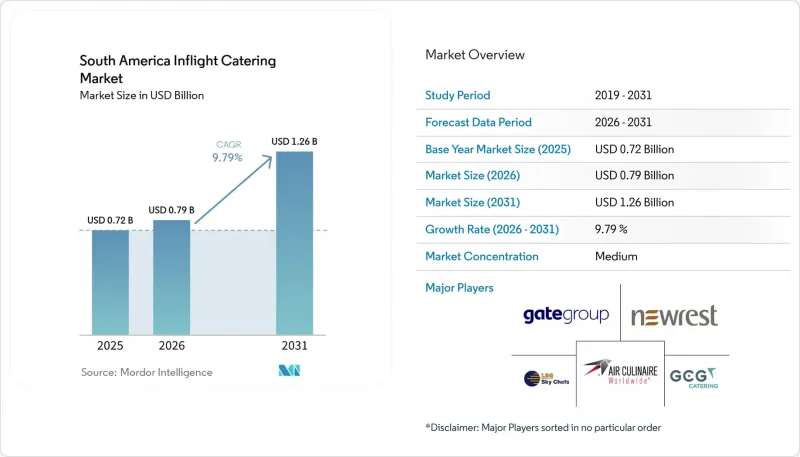
According to Mordor Intelligence, the South America inflight catering market size was valued at USD 0.72 billion in 2025, and is forecast to grow from USD 0.79 billion in 2026 to reach USD 1.26 billion by 2031, at a 9.79% CAGR during the forecast period (2026-2031).
South America Inflight Catering Market Trends and Insights
Air Passenger Traffic And Flight Frequency Recovery
South American airlines' international passenger traffic increased by 8.6% in 2025, surpassing global international RPK growth of 7.1%. IATA's latest outlook forecasts 5.0% growth in South American RPK in 2026. Brazil recorded 129.6 million passengers in 2025, including 101.2 million domestic passengers, while Peru and Argentina recorded 28.5 million and 33.3 million passengers, respectively. Rising passenger volumes and expanding flight frequencies are increasing catering demand and operational requirements at major airports. Higher aircraft utilization shortens turnaround windows. The South America inflight catering market, therefore, favors operators that can deliver meals on time and maintain food safety records. This requires practical coordination among airline planners, kitchen teams, loading crews, and transport staff. It also makes dependable daily execution more important than isolated menu changes. Providers must match production plans to flight schedules and customer requirements. Strong operating controls can limit waste, missed uplifts, and last-minute substitutions during busy periods.
Narrowbody Fleet Expansion And Network Development
Narrowbody aircraft are expected to support airline network growth across South America. In September 2025, LATAM placed orders for up to 74 Embraer E195-E2 aircraft, including 24 firm orders, with Brazilian operations scheduled to commence from November 2026. LATAM is also expected to receive six A320neo aircraft and one A321neo aircraft during Q2 2026. Abra Group's previously announced A320neo expansion is progressing, with 50 aircraft from its remaining order receiving LEAP-1A engines in July 2026. These additions will support new routes and increased flight frequencies, creating additional catering opportunities. The South America inflight catering market will require standardized meal boxes for single-aisle aircraft that accommodate dietary needs on international routes. Airline procurement teams are likely to evaluate both price and service reliability. This places greater value on providers that can maintain quality across different airports and flight schedules, including during peak holiday travel periods.
Food, Labor, Logistics, And Cold-Chain Cost Inflation
Food, labor, logistics, and cold-chain costs continue to pressure South American airline catering supply chains. Brazil's food-away-from-home prices increased 6.97% in 2025, while Argentina also faced elevated food costs. Argentina maintained collective bargaining arrangements covering catering and food-service workers in 2025. Fixed-price contracts can compress caterer margins when input costs rise, while cost-linked pricing can increase airline spending. These conditions can limit menu flexibility and investment within the South America inflight catering market. Providers must manage ingredient sourcing, staffing, airport logistics, and cold-chain requirements while maintaining consistent service across their networks.
Other drivers and restraints analyzed in the detailed report include:
- Premium Cabins, Branded Meals, And Local Cuisine
- Outsourcing To Specialized Catering Providers
- Airline Margin Pressure And Passenger Demand Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Meals accounted for 46.85% of the market in 2025, making them the largest food category. FSCs continue to provide onboard meals, with more extensive hot-meal service on longer flights. This requirement supports routine production at hub kitchens. Gategroup's Guarulhos facility produces around 18,000 meals each day and serves more than 30 long-haul flights. Bakery and confectionery products provide practical snack options on shorter flights and fit buy-on-board models where products are sold individually. Snacks, condiments, and dietary products remain smaller categories. These items require ingredient traceability and careful stock control. The South America inflight catering market continues to depend on meal volumes at major airports. Providers must match production plans to flight schedules and customer requirements. Strong operating controls can limit waste, missed uplifts, and last-minute substitutions during busy periods.
Beverages are forecast to grow at an 11.30% CAGR through 2031. LCCs monetize beverage menus that cover water, coffee, soft drinks, juices, and other beverages, while premium travel supports demand for more varied beverage selections. LATAM's Pre-Select service allows eligible Premium Business passengers to select meals in advance, with WhatsApp invitations sent 44 hours before departure; the airline links the service to improved operational efficiency and lower food waste. ANVISA and INVIMA requirements also influence food handling, packaging, and imported-input compliance. The South America inflight catering market for beverages is supported by onboard sales and digital service models. Airline procurement teams must balance price with service reliability, placing greater value on providers that can maintain quality across airports and flight schedules.
FSCs accounted for 56.10% of revenue in 2025. LATAM and Avianca operate extensive regional and long-haul networks, while Copa serves a broad South American network through its Panama hub. Their service models include cabin-specific menus and special dietary options such as gluten-free, vegetarian, and kosher meals. Multi-year catering agreements, including LATAM's renewed partnership with gategroup in March 2026, provide greater visibility into demand for catering providers. The revenue share held by FSCs reflects the continued role of included meals, particularly in premium cabins and on longer international routes. Charter and business aviation represent smaller but specialized catering opportunities. As passenger volumes and daily departures increase, facilities require clear procedures for sourcing, preparation, storage, and aircraft delivery.
LCCs are forecast to grow at a 12.10% CAGR through 2031. Their expansion supports demand for buy-on-board food and beverages. JetSMART is targeting a fleet of 100 aircraft by 2028, while Flybondi's USD 1.70 billion fleet expansion plan covers 35 new aircraft, with deliveries beginning in 2027. SKY Airline is preparing to introduce the A321XLR in late 2026, with Santiago-Punta Cana service scheduled from December 2026. Its service model now includes Economy Premier, which offers added benefits and an onboard snack. The South America inflight catering market therefore serves both premium meal programs and retail-led onboard models. IATA standards reinforce standardized ground and turnaround procedures across airline and airport operations.
Complete Report Scope:
- By Food Type
- Meals
- Bakery and Confectionery
- Beverages
- Other Food Types
- By Flight Service Type
- Full-Service Carriers (FSCs)
- Low-Cost Carriers (LCCs)
- Other Flight Types
- By Aircraft Seating Class
- Economy
- Business
- First
- By Catering Type
- Classic (Complimentary and Pre-ordered)
- Retail On Board (Buy-on-board)
- By Flight Duration
- Short-Haul
- Long-Haul
- By Geography
- Brazil
- Colombia
- Argentina
- Chile
- Peru
- Venezuela
- Rest of South America
List of Companies Covered in this Report:
- gategroup
- LSG Group (AURELIUS Group)
- Newrest Group Services SAS
- GCG
- RAMIREZ ARANA Y CIA S.A.S
- SCI Nutricion Institucional
- Marcia's Catering
- Air Culinaire Worldwide, LLC
- Inflight Chef Delight
- Dark Wing Inflight
- Altitude Dining
- Inflight Gourmet
- Inflight Supply
- Aevias Onboard Supply Services
- CVL Food Service (Assis Inernational Holding)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Air passenger traffic and flight frequency recovery
- 4.2.2 Narrowbody fleet expansion and network development
- 4.2.3 Premium cabins, branded meals, and local cuisine
- 4.2.4 Outsourcing to specialized catering providers
- 4.2.5 Pre-order, personalization, and waste-optimized programs
- 4.2.6 Regional, dietary-specific, and sustainable options
- 4.3 Market Restraints
- 4.3.1 Food, labor, logistics, and cold-chain cost inflation
- 4.3.2 Airline margin pressure and passenger demand volatility
- 4.3.3 Capacity concentration at major aviation hubs
- 4.3.4 Country-specific food safety, customs, and traceability rules
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Food Type
- 5.1.1 Meals
- 5.1.2 Bakery and Confectionery
- 5.1.3 Beverages
- 5.1.4 Other Food Types
- 5.2 By Flight Service Type
- 5.2.1 Full-Service Carriers (FSCs)
- 5.2.2 Low-Cost Carriers (LCCs)
- 5.2.3 Other Flight Types
- 5.3 By Aircraft Seating Class
- 5.3.1 Economy
- 5.3.2 Business
- 5.3.3 First
- 5.4 By Catering Type
- 5.4.1 Classic (Complimentary and Pre-ordered)
- 5.4.2 Retail On Board (Buy-on-board)
- 5.5 By Flight Duration
- 5.5.1 Short-Haul
- 5.5.2 Long-Haul
- 5.6 By Geography
- 5.6.1 Brazil
- 5.6.2 Colombia
- 5.6.3 Argentina
- 5.6.4 Chile
- 5.6.5 Peru
- 5.6.6 Venezuela
- 5.6.7 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 gategroup
- 6.4.2 LSG Group (AURELIUS Group)
- 6.4.3 Newrest Group Services SAS
- 6.4.4 GCG
- 6.4.5 RAMIREZ ARANA Y CIA S.A.S
- 6.4.6 SCI Nutricion Institucional
- 6.4.7 Marcia's Catering
- 6.4.8 Air Culinaire Worldwide, LLC
- 6.4.9 Inflight Chef Delight
- 6.4.10 Dark Wing Inflight
- 6.4.11 Altitude Dining
- 6.4.12 Inflight Gourmet
- 6.4.13 Inflight Supply
- 6.4.14 Aevias Onboard Supply Services
- 6.4.15 CVL Food Service (Assis Inernational Holding)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

