PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185046

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185046
Ultrasonic Imaging Systems For Industrial Inspection - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the ultrasonic imaging systems for industrial inspection market size is projected to expand from USD 0.82 billion in 2025 and USD 0.87 billion in 2026 to USD 1.23 billion by 2031, registering a CAGR of 7.17% between 2026 and 2031.
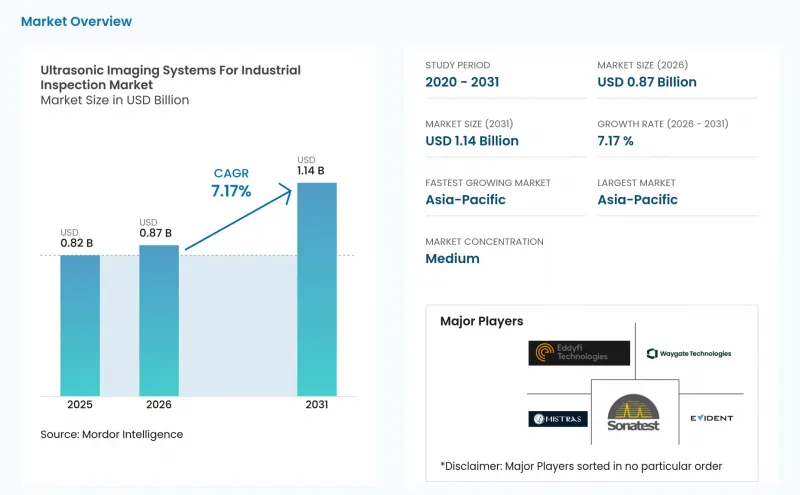
Global Ultrasonic Imaging Systems For Industrial Inspection Market Trends and Insights
Tightening Asset Integrity and Public Safety Requirements
The Ultrasonic imaging systems for industrial inspection market benefits when inspection rules require traceable records rather than visual spot checks. In April 2026, PHMSA updated 49 CFR Part 195 to reference the 2022 edition of ASME B31.4 for liquid pipeline transportation requirements in the United States. The October 2025 incorporation of ASTM A578/A578M into 49 CFR Part 192 established ultrasonic straight-beam examination of rolled steel plates for specified natural gas pipeline construction applications. These requirements make inspection records more relevant to construction, maintenance, and compliance decisions. They also favor systems that retain scan files and calibration records, rather than reporting only a pass or fail result. This creates a related need for inspection-data management capabilities that can be supplied with imaging hardware.
Aging Pipelines, Pressure Vessels, Bridges, and Rail Assets
The Ultrasonic imaging systems for industrial inspection market draws continuing demand from fixed assets that require repeated condition assessment. Older pipelines, pressure vessels, bridges, and rail assets need inspection programs that can identify corrosion, cracking, and changes in material condition before they affect serviceability. Risk-based inspection directs resources toward higher-consequence locations instead of relying only on fixed calendar intervals. This approach increases the value of detailed inspection data for oil and gas operators and power-generation asset owners. Materials that have experienced hydrogen embrittlement or microstructural coarsening can reduce acoustic-wave performance during inspection. These conditions increase the need for phased-array and FMC/TFM systems that can assess anisotropic or highly attenuating materials more effectively than single-element instruments.
High Capital Cost of Advanced Imaging Systems
The Ultrasonic imaging systems for industrial inspection market faces adoption constraints because advanced phased-array instruments and robotic scanning rigs require substantial up-front investment. FMC/TFM-capable platforms can require additional computing capacity, probes, encoded scanners, and application-specific software. Small and mid-sized inspection contractors often face the greatest challenge in price-sensitive markets. The issue is especially relevant where regional service providers conduct outsourced inspection work on narrow margins. Procedure qualification under ASME or ISO frameworks also requires engineering effort and documentation before a system can be used for regulated work. These combined equipment and qualification requirements can delay replacement cycles for firms without in-house Level III NDT resources.
Other drivers and restraints analyzed in the detailed report include:
- AI-Assisted Defect Recognition and Digital Inspection Records
- Industrial Automation and Robotic Scanning Adoption
- Shortage of Certified Phased-Array and Imaging Technicians
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Portable and handheld imaging systems held 42.73% of the Ultrasonic imaging systems for industrial inspection market size in 2025. Their position reflects long-established field workflows that require battery-powered phased-array equipment at elevated platforms, confined spaces, and remote pipeline corridors. Portable systems remain useful where moving a component to a fixed inspection station is impractical or unsafe. They are widely aligned with plant turnaround work, pipeline maintenance, and in-service pressure-equipment inspection. Their value rests on mobility, rapid setup, and the ability to collect repeatable imaging data close to the asset.
Stationary and benchtop systems serve manufacturing quality-control work where throughput and repeatability matter more than mobility. These systems support inspection tasks in automotive, electronics, and precision-machined component production. Automated and robotic imaging systems are projected to expand at an 8.17% CAGR through 2031, the fastest rate within this segmentation. Testia delivered a fully automated ultrasonic cobot inspection system to Airbus in 2025 for serial composite inspection. Six-axis robotic systems can follow mapped scan paths across varying curves, reducing manual repositioning and recalibration requirements.
Phased array ultrasonic testing held 34.86% of the Ultrasonic imaging systems for industrial inspection market size in 2025. Electronic beam steering allows multi-angle S-scan and E-scan data collection without moving the probe for every inspection angle. This capability supports complex weld geometry assessment in pressure vessels and structural steel. Conventional ultrasonic testing retains a substantial installed base among operators that use established equipment and procedures. Time-of-flight diffraction remains relevant for sizing embedded and near-surface planar flaws in compliance-focused applications.
Immersion ultrasonic testing supports precision aerospace component inspection, while guided-wave testing supports long-range pipeline screening where physical access is limited. Laser ultrasonics and scanning acoustic microscopy serve specialized needs in semiconductor packaging and additive manufacturing. FMC/TFM is projected to expand at an 8.43% CAGR through 2031, making it the fastest-growing primary technology. A 2025 study found that total focusing method imaging improved near-surface flaw resolution in laser powder bed fusion Ti-5Al-5V-5Mo-3Cr components and detected features at 0.40 +- 0.05 mm. Real-time processing also supports in-process quality-control uses that were less practical with post-process inspection methods.
Complete Report Scope:
- By System Configuration
- Portable and Handheld Imaging Systems
- Stationary and Benchtop Imaging Systems
- Automated and Robotic Imaging Systems
- By Primary Ultrasonic Technology
- Conventional Ultrasonic Testing (UT)
- Phased Array Ultrasonic Testing (PAUT)
- Time-of-Flight Diffraction (TOFD)
- Immersion Ultrasonic Testing
- Guided-Wave Ultrasonic Testing
- Full Matrix Capture and Total Focusing Method (FMC/TFM)
- Other Advanced Ultrasonic Technologies
- By Application
- Weld Inspection
- Corrosion Detection and Mapping
- Thickness Measurement
- Crack and Inclusion Detection
- Bond and Delamination Testing
- Material Characterization
- Additive Manufacturing Part Inspection
- Other Applications
- By End-User Industry
- Oil and Gas
- Power Generation
- Aerospace and Defense
- Automotive and Electric Vehicles
- Manufacturing and Heavy Engineering
- Construction and Infrastructure
- Chemical and Petrochemical
- Marine and Shipbuilding
- Electronics and Semiconductor
- Mining
- Medical Devices
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of the Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific held 38.46% of the Ultrasonic imaging systems for industrial inspection market share in 2025 and is projected to expand at an 8.27% CAGR through 2031. The region combines infrastructure investment, large-scale manufacturing, and rapid adoption of inspection automation. China supports demand through pipeline expansion, nuclear construction, and high-speed rail maintenance. Japan and South Korea contribute precision inspection demand from semiconductor, aerospace-component, and shipbuilding activities. India adds demand through investments in bridges, refineries, and power plants that use local inspection contractors.
North America held the second-largest regional position in 2025. The region is supported by a stringent pipeline and pressure-equipment inspection environment. Updates to 49 CFR Parts 192 and 195 in 2025 and 2026 reinforced the role of periodic external and inline inspection across U.S. transmission systems. Canadian pipeline corridors also face rising assessment needs as older assets require fitness-for-service documentation. Aerospace maintenance, repair, and overhaul facilities, along with OEM production lines, provide further demand for automated inspection systems.
Europe is supported by industrial assets in Germany, the United Kingdom, France, and Italy, including pressure equipment, chemical plants, and power-generation facilities. France remains a focal point for robotic composite inspection, with IRT Jules Verne reporting its FANTOM cobotic platform for nondestructive testing structures in 2026. South America is anchored by Brazil's oil and gas infrastructure, where regional TIC branches often shape the equipment channel. The Middle East and Africa draw demand from Gulf petrochemical facilities and South African mining operations, with Saudi Arabia and the UAE supporting major in-service inspection procurement programs.
- Baker Hughes Company
- EVIDENT Corporation
- Eddyfi Technologies
- Sonatest Ltd.
- MISTRAS Group, Inc.
- NDT Systems Inc.
- SGS Societe Generale de Surveillance SA
- Intertek Group plc
- Applus Services, S.A.
- TUV Rheinland AG
- DEKRA SE
- Element Materials Technology Group Limited
- NDT Global GmbH and Co. KG
- ROSEN Swiss AG
- TecScan Systems Inc.
- Innerspec Technologies, Inc.
- Cygnus Instruments Ltd.
- Jireh Industries Ltd.
- Magnaflux Corporation
- Testia SAS
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 Tightening Asset-Integrity and Public-Safety Requirements
- 4.3.2 Aging Pipelines, Pressure Vessels, Bridges, and Rail Assets
- 4.3.3 AI-Assisted Defect Recognition and Digital Inspection Records
- 4.3.4 Industrial Automation and Robotic Scanning Adoption
- 4.3.5 Inline Ultrasonic Quality Control in Electric-Vehicle Battery Manufacturing
- 4.3.6 Contactless and Remote Ultrasonic Inspection for Hazardous Areas
- 4.4 Market Restraints
- 4.4.1 High Capital Cost of Advanced Imaging Systems
- 4.4.2 Shortage of Certified Phased-Array and Imaging Technicians
- 4.4.3 Material, Geometry, Couplant, and Surface-Preparation Limitations
- 4.4.4 Fragmented Inspection Data and Qualification Workflows
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By System Configuration
- 5.1.1 Portable and Handheld Imaging Systems
- 5.1.2 Stationary and Benchtop Imaging Systems
- 5.1.3 Automated and Robotic Imaging Systems
- 5.2 By Primary Ultrasonic Technology
- 5.2.1 Conventional Ultrasonic Testing (UT)
- 5.2.2 Phased Array Ultrasonic Testing (PAUT)
- 5.2.3 Time-of-Flight Diffraction (TOFD)
- 5.2.4 Immersion Ultrasonic Testing
- 5.2.5 Guided-Wave Ultrasonic Testing
- 5.2.6 Full Matrix Capture and Total Focusing Method (FMC/TFM)
- 5.2.7 Other Advanced Ultrasonic Technologies
- 5.3 By Application
- 5.3.1 Weld Inspection
- 5.3.2 Corrosion Detection and Mapping
- 5.3.3 Thickness Measurement
- 5.3.4 Crack and Inclusion Detection
- 5.3.5 Bond and Delamination Testing
- 5.3.6 Material Characterization
- 5.3.7 Additive Manufacturing Part Inspection
- 5.3.8 Other Applications
- 5.4 By End-User Industry
- 5.4.1 Oil and Gas
- 5.4.2 Power Generation
- 5.4.3 Aerospace and Defense
- 5.4.4 Automotive and Electric Vehicles
- 5.4.5 Manufacturing and Heavy Engineering
- 5.4.6 Construction and Infrastructure
- 5.4.7 Chemical and Petrochemical
- 5.4.8 Marine and Shipbuilding
- 5.4.9 Electronics and Semiconductor
- 5.4.10 Mining
- 5.4.11 Medical Devices
- 5.4.12 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of the Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Baker Hughes Company
- 6.4.2 EVIDENT Corporation
- 6.4.3 Eddyfi Technologies
- 6.4.4 Sonatest Ltd.
- 6.4.5 MISTRAS Group, Inc.
- 6.4.6 NDT Systems Inc.
- 6.4.7 SGS Societe Generale de Surveillance SA
- 6.4.8 Intertek Group plc
- 6.4.9 Applus Services, S.A.
- 6.4.10 TUV Rheinland AG
- 6.4.11 DEKRA SE
- 6.4.12 Element Materials Technology Group Limited
- 6.4.13 NDT Global GmbH and Co. KG
- 6.4.14 ROSEN Swiss AG
- 6.4.15 TecScan Systems Inc.
- 6.4.16 Innerspec Technologies, Inc.
- 6.4.17 Cygnus Instruments Ltd.
- 6.4.18 Jireh Industries Ltd.
- 6.4.19 Magnaflux Corporation
- 6.4.20 Testia SAS
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

