PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185078

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185078
Timestamping Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
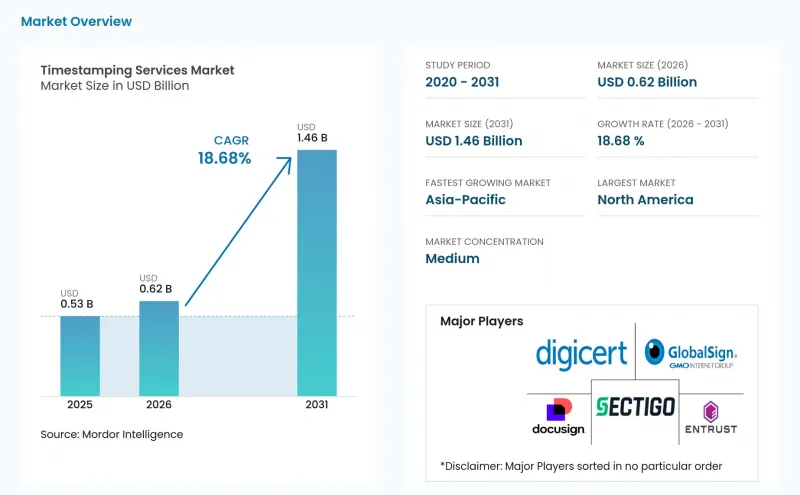
According to Mordor Intelligence, the timestamping services market size was valued at USD 0.53 billion in 2025 and is estimated to grow from USD 0.62 billion in 2026 to reach USD 1.46 billion by 2031, at a CAGR of 18.68% during the forecast period (2026-2031).
Global Timestamping Services Market Trends and Insights
Growth in Digital Compliance and Legally Binding Electronic Records
Digital records are becoming central to regulated transactions, which increases the need to show when a file was created, approved, or changed. The European Commission established standards for qualified electronic time-stamping services through Commission Implementing Regulation 2025/1929, which identifies ETSI EN 319 421 and ETSI EN 319 422 as applicable standards. These requirements support the use of qualified timestamps in workflows where document integrity and timing may later be called into question. The timestamping services market, therefore, benefits when organizations standardize records used for cross-border contracts, e-invoicing, and regulated retention. GDPR-related accountability requirements also increase the value of records that show access and modification history. The timestamping services market gains further support as companies outside Europe align internal controls with eIDAS-based practices to avoid maintaining separate evidence processes.
Expansion of Code-Signing and Software Supply-Chain Security
Software publishers increasingly need evidence that signed code was released through a controlled and traceable process. Microsoft made Signing Transparency generally available in 2026, using the IETF SCITT architecture to create tamper-evident software supply-chain records. The CA/B Forum change that limited code-signing certificate lifetimes to 460 days, effective March 2026, makes valid timestamp tokens more important after a signing certificate expires. This change affects existing signed artifacts as well as future releases, potentially increasing transaction volumes without a corresponding increase in software output. NIST also described code signing as part of software supply-chain management in its 2025 guidance. The timestamping services market is consequently becoming more connected to DevSecOps practices than to traditional public key infrastructure purchases alone.
Interoperability Gaps Across Timestamp Protocols and Legacy Systems
Organizations often manage RFC 3161 tokens, blockchain-anchored proofs, and archive formats from multiple signing systems. These formats may require different validation processes and increase the cost of managing long-lived document archives. Sectigo completed the migration of more than 500,000 public certificates from Entrust in September 2025, demonstrating the downstream effects that changes in certificate hierarchies can have on validation chains. DigiCert also notified customers in 2026 that QuoVadis timestamping certificates would be replaced, requiring some customers to review pinned references. Smaller organizations may face particular difficulty when they need to rebuild certificate paths, update hashes, or re-timestamp older signatures. The timestamping services market can grow more slowly where customers cannot validate records across providers without specialized tools. Providers that simplify migration and validation have a clearer retention advantage.
Other drivers and restraints analyzed in the detailed report include:
- API-Based Cloud Timestamping Adoption
- Rising Digital Fraud and Evidentiary Requirements
- Data-Residency and Cross-Border Trust-Service Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Timestamping platforms and software held 42.89% of the timestamping services market in 2025. Enterprise deployments use software such as Ascertia ADSS TSA Server, Utimaco TimestampServer HSM, and Keyfactor SignServer to support qualified trust-service operations and document integrations. These installations remain important where companies require direct control over infrastructure, controlled archives, audit evidence, and complex internal approval workflows. Managed Timestamping and Trust Services is projected to record a 22.71% CAGR through 2031. This growth reflects a buyer preference for subscription services that combine timestamp issuance, service-level commitments, accreditation, and certificate lifecycle support.
Utimaco completed its eIDAS conformity assessment in July 2026 after implementing FIPS 140-3 Level 3 hardware security modules and geo-redundant service architecture. That example shows the operational standards that managed providers must sustain. Professional Services remains the smallest component, yet it supports implementation, eIDAS 2.0 readiness work, and cryptographic migration projects. Signicat moved to Ascertia ADSS TSA Server after its prior solution became technically obsolete, showing how platform replacement can create demand for deployment and transition support. The timestamping services industry is likely to favor vendors that can support recurring conformity obligations while simplifying customer transitions from older systems.
Cloud held 63.27% of the timestamping services market size in 2025 and is projected to grow at a 23.64% CAGR through 2031. Cloud services allow companies to connect signing applications through application programming interfaces without acquiring hardware security modules. GMO GlobalSign recorded more than 5.5 million timestamp operations during June 2026, which indicates active use of API-based delivery at scale. This model suits buyers that need fast implementation, flexible usage, centralized service management, and predictable capacity during fluctuating document volumes. It also supports smaller companies that previously could not justify a dedicated timestamp authority.
On-premises systems retain importance where defense, financial services, healthcare, or public-sector users require physical control of keys and locally managed records. Hybrid configurations combine cloud capacity for high-volume activity with controlled infrastructure for high-assurance signing. Regulation 2025/1929 includes technical expectations for hardware security modules that apply to qualified services. DigiCert's 2026 certificate replacement notice also showed that cloud users must manage dependency changes where their applications pin a specific timestamp certificate. The timestamping services market size for cloud delivery is therefore supported by convenience, while hybrid and on-premises models remain relevant for strict control requirements.
Complete Report Scope:
- By Component
- Timestamping Platforms and Software
- Managed Timestamping and Trust Services
- Professional Services
- By Deployment Model
- Cloud
- On-Premises
- Hybrid
- By Organization Size
- Large Enterprises
- Small and Medium-sized Enterprises
- By End User Industry
- Banking, Financial Services and Insurance
- Government and Public Sector
- Information Technology and Telecommunications
- Legal and Professional Services
- Healthcare and Life Sciences
- Other End User Industries
- By Geography
- North America
- United States
- Canada
- South America
- Brazil
- Mexico
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 36.72% of the timestamping services market share in 2025. The region benefits from global certificate authorities and widespread use of cryptographic controls in software and financial services, where mature digital workflows are common. Executive Order 14412 requires U.S. federal high-value systems to migrate digital signatures to post-quantum cryptography by December 31, 2031, while a related OMB memorandum requires agencies to submit migration plans during 2026. This direction supports procurement for providers capable of managing cryptographic transitions and long-term validation. Shorter code-signing certificate lifetimes also increase activity in the region's software supply chains, while Canada follows similar trust-service practices in government and finance.
Europe is the second-largest regional area because eIDAS provides an established legal basis for qualified electronic timestamps. France's ANSSI supervises trust services under eIDAS, supporting a quality-led environment for public and private users. Namirial completed eIDAS 2 compliance across Italy, France, and Spain in 2026. The timestamping services market has a structured European compliance base, although technical and audit obligations can limit smaller providers. South America is developing through Brazil's electronic invoice framework and Mexico's CFDI requirements, which have familiarized users with controlled digital records and support wider private-sector adoption.
Asia-Pacific is projected to advance at a 23.91% CAGR through 2031, the highest regional rate. India is expanding trust-service capacity through certificate authority partnerships and financial-market infrastructure, while Japan maintains a national certification framework, and Seiko Trust renewed its certification in February 2025. China's localization requirements support domestic providers and create a distinct operating environment. Digital government programs in the United Arab Emirates and Saudi Arabia, along with digital finance demand in South Africa, are driving adoption across the Middle East and Africa.
- GlobalSign
- Entrust Corporation
- DocuSign, Inc.
- DigiCert, Inc.
- Sectigo Limited
- Asseco Data Systems S.A.
- SwissSign AG
- SK ID Solutions AS
- Utimaco GmbH
- Ascertia Limited
- EDICOM Capital, S.L.
- eMudhra Limited
- Namirial S.p.A.
- InfoCert S.p.A.
- Signicat AS
- Evidency SAS
- LuxTrust S.A.
- Guardtime AS
- OriginStamp AG
- OpenTimestamps
- DigiStamp, Inc.
- Notarius International AG
- T-Systems International GmbH
- Seiko Solutions Inc.
- OneSpan Inc.
- Thales Digital Identity and Security
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in Digital Compliance and Legally Binding Electronic Records
- 4.2.2 Expansion of Code-Signing and Software Supply-Chain Security
- 4.2.3 API-Based Cloud Timestamping Adoption
- 4.2.4 Rising Digital Fraud and Evidentiary Requirements
- 4.2.5 Blockchain and Distributed-Ledger Provenance Use Cases
- 4.2.6 Regulatory Recognition of Qualified Electronic Timestamps
- 4.3 Market Restraints
- 4.3.1 Interoperability Gaps Across Timestamp Protocols and Legacy Systems
- 4.3.2 Data-Residency and Cross-Border Trust-Service Constraints
- 4.3.3 Cryptographic Migration and Long-Term Validation Costs
- 4.3.4 Dependence on High-Assurance Time Sources and HSM Infrastructure
- 4.4 Impact of Macroeconomic Factors
- 4.5 Value-Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Competitive Rivalry
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of New Entrants
- 4.8.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Timestamping Platforms and Software
- 5.1.2 Managed Timestamping and Trust Services
- 5.1.3 Professional Services
- 5.2 By Deployment Model
- 5.2.1 Cloud
- 5.2.2 On-Premises
- 5.2.3 Hybrid
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium-sized Enterprises
- 5.4 By End User Industry
- 5.4.1 Banking, Financial Services and Insurance
- 5.4.2 Government and Public Sector
- 5.4.3 Information Technology and Telecommunications
- 5.4.4 Legal and Professional Services
- 5.4.5 Healthcare and Life Sciences
- 5.4.6 Other End User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Mexico
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 GlobalSign
- 6.4.2 Entrust Corporation
- 6.4.3 DocuSign, Inc.
- 6.4.4 DigiCert, Inc.
- 6.4.5 Sectigo Limited
- 6.4.6 Asseco Data Systems S.A.
- 6.4.7 SwissSign AG
- 6.4.8 SK ID Solutions AS
- 6.4.9 Utimaco GmbH
- 6.4.10 Ascertia Limited
- 6.4.11 EDICOM Capital, S.L.
- 6.4.12 eMudhra Limited
- 6.4.13 Namirial S.p.A.
- 6.4.14 InfoCert S.p.A.
- 6.4.15 Signicat AS
- 6.4.16 Evidency SAS
- 6.4.17 LuxTrust S.A.
- 6.4.18 Guardtime AS
- 6.4.19 OriginStamp AG
- 6.4.20 OpenTimestamps
- 6.4.21 DigiStamp, Inc.
- 6.4.22 Notarius International AG
- 6.4.23 T-Systems International GmbH
- 6.4.24 Seiko Solutions Inc.
- 6.4.25 OneSpan Inc.
- 6.4.26 Thales Digital Identity and Security
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

