PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185087

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185087
North America Virtual Schools - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the North America virtual schools market was valued at USD 21.4 billion in 2025 and estimated to grow from USD 23.3 billion in 2026 to reach USD 36.4 billion by 2031, at a CAGR of 9.30% during the forecast period (2026-2031).
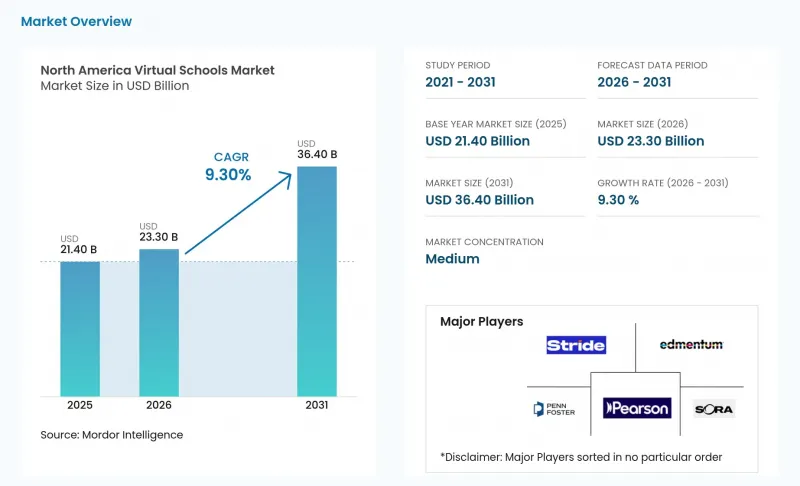
North America Virtual Schools Market Trends and Insights
Rising Demand for Flexible Remote Education
Flexible learning remains a key driver for the North America virtual school's market. An official report on Education indicated that 57% of returning adult learners considered online or hybrid access essential to their decision to re-enroll, with 33% specifically selecting hybrid programs. This demonstrates that online access has shifted from being a temporary alternative to a critical factor in enrollment decisions. The trend supports the growth of adult education, hybrid learning models, and outcome-focused online programs in the region. Providers offering both flexibility and recognized credentials are well-positioned to attract and retain learners managing work, family, and education simultaneously.
State-Level Digital Infrastructure Funding
State and federal funding initiatives are strengthening the foundation of the North America virtual school's market. North Carolina has introduced grants to support districts implementing digital learning programs aligned with the state plan. Similarly, Minnesota expanded online learning state aid eligibility to include students beyond traditional K-12 age groups. These developments enhance both the digital infrastructure and the pool of accessible learners. The simultaneous progress of funding and eligibility reforms is particularly impactful in rural and low-density areas, where demand exists but has been constrained by inconsistent digital access and limited funding coverage.
Regional Broadband Gaps and Uneven Device Access
Broadband access remains a critical structural challenge for the North America virtual schools' market. Reports indicate that students in remote rural areas have significantly lower fixed home broadband access compared to their suburban counterparts. Additionally, disparities in internet speeds persist across states and between urban and rural regions, as noted in recent studies. These connectivity issues undermine the reliability of live classes, video-based instruction, and scheduled assessments for students in less-connected areas. Consequently, the virtual schools' market in North America faces limitations in expanding enrollment in regions where demand exists but household connectivity remains insufficient.
Other drivers and restraints analyzed in the detailed report include:
- Personalized Learning Paths for Diverse Learners
- Career and Technical Education Integration in Virtual Schools
- Complex State Accreditation and Teacher Certification Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
High schools held 41.84% of the North America virtual schools market share in 2025, making them the largest end-user segment. This reflects demand for credit recovery, dual enrollment, Advanced Placement access, and diploma pathways linked to career and technical education. The market relies on high school demand as a stable base, driven by older learners' needs for graduation timelines, course flexibility, and work-related options. Stride's operations across general education and career learning schools support this segment in several United States. High school demand also aligns with supplemental programs, allowing districts to add courses without fully transferring student enrollment. Middle and elementary school segments are smaller but significant due to the value of maintaining a single provider relationship across K-12 education. Edmentum's 2025 Courseware update, which unified K-5 curriculum and support tools, enhances providers' ability to serve younger learners through one platform.
Adult education is expected to grow at a 12.70% CAGR through 2031, making it the fastest-growing end-user segment in the North America virtual schools' market. The 2026 ACE findings indicate that online and hybrid access has influenced re-enrollment decisions among returning adult learners. Providers serving both school-age and adult learners on a shared platform are likely to achieve a balanced enrollment mix as labor, policy, and demographic conditions evolve.
Complete Report Scope:
- By End User
- Elementary Schools
- Middle Schools
- High Schools
- Adult Education
- By School Type
- Full-Time Virtual Schools
- Supplemental/Part-Time Virtual Schools
- Hybrid Virtual Schools
- By Delivery Mode
- Synchronous Learning (Live Classes)
- Asynchronous Learning (Self-Paced)
- Blended Learning
- By Geography
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Stride Inc.
- Pearson Plc
- Penn Foster
- Edmentum Inc.
- Sora Schools Inc.
- Excel High School
- Forest Trail Academy
- American Virtual Academy
- Laurel Springs School
- Keystone School
- Whitmore School
- Ontario Virtual School Inc.
- Enlightium Academy
- WiloStar3D Academy
- Educere LLC
- Smart Schools LLC
- My First Montessori School Online
- E-School Virtual Private Academy
- International Schooling
- Bridgeway Academy
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Flexible Remote Education
- 4.2.2 State-Level Digital Infrastructure Funding
- 4.2.3 Personalized Learning Paths for Diverse Learners
- 4.2.4 Career and Technical Education Integration in Virtual Schools
- 4.2.5 Parent-Coach Learning Models and Engagement Analytics
- 4.2.6 Expansion of Hybrid, Credit-Recovery, and Alternative Schooling Pathways
- 4.3 Market Restraints
- 4.3.1 Regional Broadband Gaps and Uneven Device Access
- 4.3.2 Complex State Accreditation and Teacher Certification Requirements
- 4.3.3 Rising Cybersecurity, Data Privacy, and Compliance Costs
- 4.3.4 District Budget Pressures and ROI Scrutiny for Virtual Programs
- 4.4 Value Chain / Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By End User
- 5.1.1 Elementary Schools
- 5.1.2 Middle Schools
- 5.1.3 High Schools
- 5.1.4 Adult Education
- 5.2 By School Type
- 5.2.1 Full-Time Virtual Schools
- 5.2.2 Supplemental/Part-Time Virtual Schools
- 5.2.3 Hybrid Virtual Schools
- 5.3 By Delivery Mode
- 5.3.1 Synchronous Learning (Live Classes)
- 5.3.2 Asynchronous Learning (Self-Paced)
- 5.3.3 Blended Learning
- 5.4 By Geography
- 5.4.1 United States
- 5.4.2 Canada
- 5.4.3 Mexico
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Stride Inc.
- 6.4.2 Pearson Plc
- 6.4.3 Penn Foster
- 6.4.4 Edmentum Inc.
- 6.4.5 Sora Schools Inc.
- 6.4.6 Excel High School
- 6.4.7 Forest Trail Academy
- 6.4.8 American Virtual Academy
- 6.4.9 Laurel Springs School
- 6.4.10 Keystone School
- 6.4.11 Whitmore School
- 6.4.12 Ontario Virtual School Inc.
- 6.4.13 Enlightium Academy
- 6.4.14 WiloStar3D Academy
- 6.4.15 Educere LLC
- 6.4.16 Smart Schools LLC
- 6.4.17 My First Montessori School Online
- 6.4.18 E-School Virtual Private Academy
- 6.4.19 International Schooling
- 6.4.20 Bridgeway Academy
7 Market Opportunities & Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Opportunity Assessment
- 7.2.1 AI-Driven Adaptive Learning and Student Success Prediction
- 7.2.2 Credentialed Career Pathways, Dual Enrollment, and Micro-Credentials

