PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187209

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187209
India Residential Real Estate - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the India residential real estate market size is expected to increase from USD 438.5 billion in 2026 to USD 481.9 billion in 2027 and reach USD 757.2 billion by 2032, growing at a CAGR of 9.46% over 2027-2032.
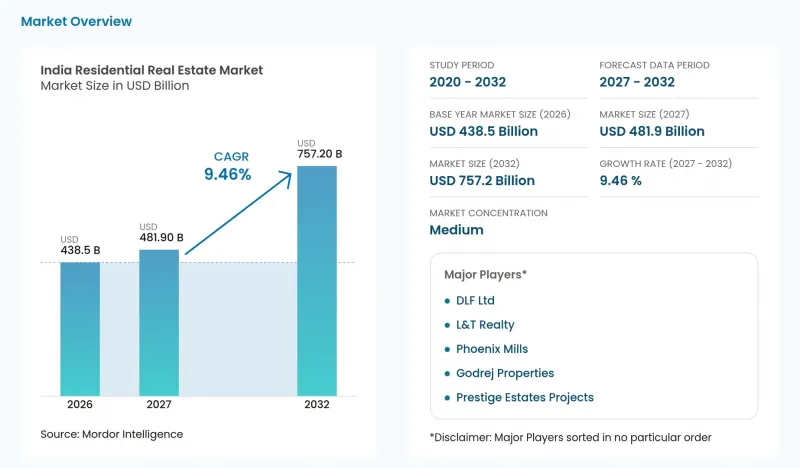
This report is segmented by Property Type (Apartments & Condominiums and Villas & Landed Houses), Price Band (Mid-Market, Affordable, and more), Business Model (Sales and Rental), Mode of Sale (Primary and Secondary), and Geography (Rest of India, Mumbai, and more). The market forecasts are provided in terms of value (USD), based on availability.
India Residential Real Estate Market Trends and Insights
RBI Rate-Cut Cycle From Q1-2025 Reinvigorating Mortgage Affordability Across Tier-1 Cities
Lower mortgage pricing can expand a household's borrowing capacity without requiring a corresponding increase in its monthly repayment ceiling. The Reserve Bank of India reported that scheduled commercial banks' weighted-average rate on fresh rupee housing loans fell from 8.7% in February 2025 to 7.61% in February 2026. State Bank of India cut its home-loan rate by 25 basis points to 8.25%, effective February 15, 2025, after the RBI's repo-rate cut. For eligible buyers, that dated easing increased the amount that a given repayment limit could finance, strengthening their capacity to purchase a dwelling.
Union Budget 2025 'Green Home' Tax Deductions Accelerating Sustainable Unit Launches
A green-home deduction would strengthen demand only when its value to an eligible buyer offsets part of the dwelling's additional cost. For a household able to claim qualifying relief, the relevant comparison would be the purchase price after tax savings against the price of an alternative home. That mechanism could give a developer room to supply more sustainable units without requiring buyers to accept the entire cost difference unaided. The benefit would depend on eligibility, usable tax relief, and a price that leaves the household better able to complete the purchase. Sustainable launches would therefore respond to the buyer's effective transaction cost, rather than the presence of a green designation alone.
Existing Capital-Gains Surcharge Discouraging Short-Term Upgrades
A homeowner considering an early upgrade must compare the replacement dwelling's cost with sale proceeds after tax, rather than headline appreciation. India uses a 24-month holding period for land and buildings to qualify as long-term capital assets. For transfers under India's post-July 2024 tax regime, gains from short-term assets outside listed securities are taxed at normal rates, with applicable surcharge and cess. For an affected seller, that liability can reduce the equity available for a larger home even when the existing property appreciates. This makes upgrades after a short ownership period more dependent on additional savings, since a higher sale price need not provide enough usable equity to finance the move.
Other drivers and restraints analyzed in the detailed report include:
- IT & GCC Expansion Into Tier-2 Hubs Unlocking Fresh Residential Corridors
- Progress on 'Housing for All' Targets Could Release Pent-Up Affordable Demand
- Peripheral Micro-Market Inventory Glut (Greater Noida West, Yelahanka) Suppressing Price Appreciation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Apartments and condominiums accounted for a 64.96% share of the India residential real estate market size in 2026, making this the largest segment. Embassy Developments reported that its Embassy Greenshore apartment project in North Bengaluru was sold out by October 5, 2026. Its December 2025 first-phase launch comprised 700 units within an 878-apartment, two-phase project. The progression from a large phase release to reported sellout demonstrates project-specific capacity to absorb sizable apartment supply. For suppliers, a shared development provides a platform for repeated unit-level transactions, with release scale supported by the depth of project-specific buyer demand.
Villas and landed houses are the fastest-growing segment, with a forecast CAGR of 10.12% over 2027-2032. Century Real Estate's Ferie Villas at Century Wintersun on Yelahanka-Doddaballapura Road in North Bengaluru were fully booked by April 1, 2025. This project-level result gives a villa developer a demand signal tied to a particular residential offering and location. For this format, the proposition centers on an individual landed home, so expansion depends on matching that product with suitable development sites. Scaling the offering therefore requires a sequence of viable local projects, with each site needing its own buyer response before the supplier can treat the format as a repeatable source of sales.
Mid-market homes represented a 47.86% India residential real estate market share in 2026, making this the largest segment. Ajmera Realty & Infra India Ltd. reported cumulative sales of 257,699 square feet of carpet area out of 260,288 square feet at Bengaluru's Lugaano and Florenza projects by June 30, 2026. The developer identified these projects with its mid-market portfolio and held 70% ownership, while the reported area covered the full projects. Full completion gives their remaining dwellings a different proposition from a pre-construction commitment, since buyers can assess an existing development. Near-complete sell-through across these completed projects demonstrates depth in Ajmera's mid-market buyer base and leaves limited scope for further sales from the same developments.
Affordable housing is the fastest-growing segment, with a forecast CAGR of 10% over 2027-2032. The Maharashtra Housing and Area Development Authority's Pune Board completed a sale lottery for 4,186 affordable housing units in Pune and other Maharashtra districts on February 10, 2026, with 215,965 eligible applicants. Such a bounded allocation process can make eligibility-qualified buyer interest visible before households complete property purchases. Buyer participation can exceed available allocations without producing an immediate increase in dwelling transactions. The supply of allocatable homes, together with the ability to convert an allocation into a purchase, therefore sets the commercial pace more directly than the applicant pool alone.
Complete Report Scope:
- By Property Type
- Apartments & Condominiums
- Villas & Landed Houses
- By Price Band
- Affordable
- Mid-Market
- Luxury
- By Business Model
- Sales
- Rental
- By Mode of Sale
- Primary (New-Build)
- Secondary (Existing Home Resale)
- By Geography
- Bengaluru
- Mumbai
- Delhi-NCR
- Hyderabad
- Pune
- Chennai
- Ahmedabad
- Kolkata
- Rest of India
List of Companies Covered in this Report:
- DLF Ltd
- Godrej Properties
- Prestige Estates Projects
- Brigade Enterprises
- Sobha Ltd
- Oberoi Realty
- L&T Realty
- Phoenix Mills
- Mahindra Lifespace Developers
- Puravankara Ltd
- Kolte-Patil Developers
- Sunteck Realty
- Lodha Group (Lodha Developers)
- Embassy Developments
- NBCC (India)
- Omaxe Ltd
- Ansal Properties & Infrastructure
- Bharti Realty
- Total Environment
- Casagrand Builders
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 RBI Rate-Cut Cycle From Q1-2025 Reinvigorating Mortgage Affordability Across Tier-1 Cities
- 4.2.2 Union Budget 2025 'Green Home' Tax Deductions Accelerating Sustainable Unit Launches
- 4.2.3 IT & GCC Expansion Into Tier-2 Hubs Unlocking Fresh Residential Corridors
- 4.2.4 Progress on 'Housing for All' Targets Could Release Pent-Up Affordable Demand
- 4.2.5 API-Based National Land Record Digitization Could Shorten NRI Due-Diligence Timelines
- 4.2.6 Fractional Ownership & REIT-Lite Platforms Drawing Millennial Capital Into Premium Projects
- 4.3 Market Restraints
- 4.3.1 Existing Capital-Gains Surcharge Discouraging Short-Term Upgrades
- 4.3.2 Peripheral Micro-Market Inventory Glut (Greater Noida West, Yelahanka) Suppressing Price Appreciation
- 4.3.3 Skilled Construction Labor Diversion to Infra Megaprojects Delaying Residential Completions
- 4.3.4 SEBI BRSR Core ESG Compliance Costs Squeezing Mid-Sized Developer Margins
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Overview of the Economy and Market
- 4.9 Real Estate Buying Trends - Socio-economic and Demographic Insights
- 4.10 Insights into Rental Yields in Real Estate Segment
- 4.11 Real Estate Lending Dynamics
- 4.12 Insights Into Affordable Housing Support Provided by Government and Public-private Partnerships
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Property Type
- 5.1.1 Apartments & Condominiums
- 5.1.2 Villas & Landed Houses
- 5.2 By Price Band
- 5.2.1 Affordable
- 5.2.2 Mid-Market
- 5.2.3 Luxury
- 5.3 By Business Model
- 5.3.1 Sales
- 5.3.2 Rental
- 5.4 By Mode of Sale
- 5.4.1 Primary (New-Build)
- 5.4.2 Secondary (Existing Home Resale)
- 5.5 By Geography
- 5.5.1 Bengaluru
- 5.5.2 Mumbai
- 5.5.3 Delhi-NCR
- 5.5.4 Hyderabad
- 5.5.5 Pune
- 5.5.6 Chennai
- 5.5.7 Ahmedabad
- 5.5.8 Kolkata
- 5.5.9 Rest of India
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 DLF Ltd
- 6.4.2 Godrej Properties
- 6.4.3 Prestige Estates Projects
- 6.4.4 Brigade Enterprises
- 6.4.5 Sobha Ltd
- 6.4.6 Oberoi Realty
- 6.4.7 L&T Realty
- 6.4.8 Phoenix Mills
- 6.4.9 Mahindra Lifespace Developers
- 6.4.10 Puravankara Ltd
- 6.4.11 Kolte-Patil Developers
- 6.4.12 Sunteck Realty
- 6.4.13 Lodha Group (Lodha Developers)
- 6.4.14 Embassy Developments
- 6.4.15 NBCC (India)
- 6.4.16 Omaxe Ltd
- 6.4.17 Ansal Properties & Infrastructure
- 6.4.18 Bharti Realty
- 6.4.19 Total Environment
- 6.4.20 Casagrand Builders
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

