PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187262

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187262
India Chocolate - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the India chocolate market size is expected to increase from USD 2.72 billion in 2026 to USD 2.93 billion in 2027 and reach USD 4.16 billion by 2032, growing at a CAGR of 7.28% over 2027-2032.
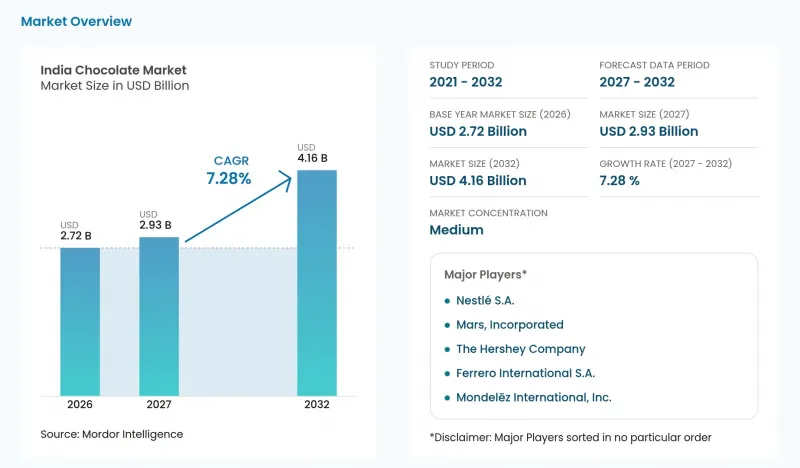
The market's volume is expected to increase from 297.4 thousand tons in 2026 to 312 thousand tons in 2027 and reach 396.3 thousand tons by 2032, growing at a CAGR of 4.9% over 2027-2032. This report is segmented by Product Type (Milk and White Chocolate and Dark Chocolate), Form (Tablets and Bars, Molded Blocks, and more), Price Range (Mass and Premium), Ingredient Type (Dairy-based, Plant-based, and more), and Distribution Channel (Convenience Stores, Supermarkets/Hypermarkets, and more). The market forecasts are provided in terms of value (USD) and volume (tons), based on availability.
India Chocolate Market Trends and Insights
Health and wellness trends
Health-conscious preferences create room for craft chocolate designed around buyers' priorities for ingredients, cocoa content and sugar content. In May 2025, The Economic Times described Indian craft-chocolate buyers as seeking high-cocoa chocolate, clean labels and low-sugar options. Recipe composition and clear ingredient information can connect those preferences with a chocolate choice for craft buyers limiting sugar intake. The same article contrasted mass-market chocolate at 50% to 60% sugar with craft bars that usually contain 20% to 30%. To match the craft bars' usual sugar level, the compared mass-market recipes would need reformulation, making a lower-sugar offer a product-development commitment for established brands.
Strong gifting culture during festivals and occasions
Gifting occasions can expand chocolate demand beyond individual consumption by giving buyers a specific recipient and a deadline for purchase. Amazon India reported over 1.3 times year-over-year growth in luxury chocolates and curated hampers on Amazon.in around Valentine's Day 2026. Amazon India's broader gifting category recorded 1.2 times year-over-year growth for the same occasion. The contrast suggests that occasion demand can reward a premium gift proposition, making recipient suitability a relevant commercial choice for chocolate sellers. For sellers, premium chocolates and curated hampers outpacing gifting overall points to curated gift assortments as the stronger offer within the occasion.
High temperature sensitivity and climate challenges
Heat sensitivity can separate an accepted chocolate order from a dependable delivery date, particularly when intact presentation matters to the purchase. Cocoacraft, an artisan single-origin chocolate seller from Kerala, says summer heat may prevent its chocolates from arriving intact. Its policy describes freezing chocolate before dispatch and using temperature-controlled boxes, yet it offers to hold an order until cooler weather. For orders handled under this policy, protective packaging does not remove the tradeoff between prompt shipment and confidence in product condition. A hold lasts until the weather cools, so a summer order may arrive well after the date the buyer wanted, which matters most for gifts bought for a fixed occasion.
Other drivers and restraints analyzed in the detailed report include:
- Product innovation and flavor experimentation
- Sustainability and ethical sourcing narratives
- Cold chain infrastructure gaps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Milk and white chocolate accounted for a 75.45% share of the India chocolate market size in 2026, making it the largest segment. In July 2026, Mondelez India launched COTE D'OR with dark and milk chocolate variants and said the range would be available through leading quick-commerce platforms. The milk variants illustrate product renewal within the leading category, without requiring buyers to choose a different chocolate type. For a milk-chocolate supplier, a distinct branded range offers a way to compete for buyers who retain that recipe preference. The commercial test is whether the additional range earns a separate purchase occasion instead of merely dividing existing milk-chocolate purchases among more labels.
Dark chocolate is forecast to be the fastest-growing segment at a CAGR of 7.78% over 2027-2032. In July 2026, the Gujarat Co-operative Milk Marketing Federation said Amul's sugar-free dark chocolate contributed nearly 10% of Amul's total chocolate sales. That company-specific result shows how a defined formulation can earn a place within an established chocolate portfolio. For producers considering this category, a sugar-free dark recipe can address buyers seeking that particular combination of attributes. Amul was also described as India's dark-chocolate leader in July 2026, making sugar-free recipes a field where specialists would compete with an established incumbent.
Tablets and bars represented a 48.26% India chocolate market share in 2026, making them the largest segment. A tablet or bar can place one recipe at the center of a tasting or sharing occasion. Buyers can compare cocoa intensity and texture within that recipe rather than choose among separately filled pralines. For a producer, this concentrates the product decision on the chocolate itself, making recipe development more consequential than the breadth of an assortment.
Pralines and truffles are forecast to be the fastest-growing segment at a CAGR of 7.58% over 2027-2032. Neuhaus opened its first Indian boutique at Navi Mumbai International Airport in 2026, extending retail access to the praline maker's Belgian-made chocolates. That expansion gives a specialist producer a direct consumer-facing setting in India, linking the format with an identifiable seller. For buyers selecting a chocolate collection, the proposition can center on the composition and presentation of the assortment. Neuhaus later reported that its first 2 boutiques in Mumbai had opened.
Complete Report Scope:
- By Product Type
- Dark Chocolate
- Milk and White Chocolate
- By Form
- Tablets and Bars
- Molded Blocks
- Pralines and Truffles
- Other Forms
- By Price Range
- Mass
- Premium
- By Ingredient Type
- Dairy-based
- Plant-based
- Single Origin
- By Distribution Channel
- Supermarkets/Hypermarkets
- Online Retail Stores
- Convenience Stores
- Other Distribution Channels
List of Companies Covered in this Report:
- Mondelez International, Inc.
- Nestle S.A.
- Ferrero International S.A.
- Mars, Incorporated
- ITC Limited
- The Hershey Company
- Gujarat Co-operative Milk Marketing Federation (Amul)
- DS Group (Laderach)
- Reliance Consumer Products Ltd
- Surya Food & Agro Ltd (Priyagold)
- Lotus Chocolate Company Ltd
- Campco Chocolates
- Paul & Mike Craft Chocolates
- Soklet
- Pascati
- Rage Chocolate
- Choko La
- Wellversed Health Private Limited (Ketofy Keto Chocolate)
- Bean Therapy
- SMOOR Chocolates
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Health and wellness trends
- 4.2.2 Strong gifting culture during festivals and occasions
- 4.2.3 Product innovation and flavor experimentation
- 4.2.4 Sustainability and ethical sourcing narratives
- 4.2.5 Strong brand marketing and emotional positioning
- 4.2.6 Premiumization and indulgence seeking
- 4.3 Market Restraints
- 4.3.1 High temperature sensitivity and climate challenges
- 4.3.2 Cold chain infrastructure gaps
- 4.3.3 Health concerns over high sugar and fat content
- 4.3.4 Heavy import dependency for cocoa
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Consumer Behaviour Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE AND VOLUME)
- 5.1 By Product Type
- 5.1.1 Dark Chocolate
- 5.1.2 Milk and White Chocolate
- 5.2 By Form
- 5.2.1 Tablets and Bars
- 5.2.2 Molded Blocks
- 5.2.3 Pralines and Truffles
- 5.2.4 Other Forms
- 5.3 By Price Range
- 5.3.1 Mass
- 5.3.2 Premium
- 5.4 By Ingredient Type
- 5.4.1 Dairy-based
- 5.4.2 Plant-based
- 5.4.3 Single Origin
- 5.5 By Distribution Channel
- 5.5.1 Supermarkets/Hypermarkets
- 5.5.2 Online Retail Stores
- 5.5.3 Convenience Stores
- 5.5.4 Other Distribution Channels
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Mondelez International, Inc.
- 6.4.2 Nestle S.A.
- 6.4.3 Ferrero International S.A.
- 6.4.4 Mars, Incorporated
- 6.4.5 ITC Limited
- 6.4.6 The Hershey Company
- 6.4.7 Gujarat Co-operative Milk Marketing Federation (Amul)
- 6.4.8 DS Group (Laderach)
- 6.4.9 Reliance Consumer Products Ltd
- 6.4.10 Surya Food & Agro Ltd (Priyagold)
- 6.4.11 Lotus Chocolate Company Ltd
- 6.4.12 Campco Chocolates
- 6.4.13 Paul & Mike Craft Chocolates
- 6.4.14 Soklet
- 6.4.15 Pascati
- 6.4.16 Rage Chocolate
- 6.4.17 Choko La
- 6.4.18 Wellversed Health Private Limited (Ketofy Keto Chocolate)
- 6.4.19 Bean Therapy
- 6.4.20 SMOOR Chocolates
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

