PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187779

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187779
United Kingdom Chocolate - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the United Kingdom chocolate market size was valued at USD 13.12 billion in 2026 and estimated to grow from USD 13.79 billion in 2027 to reach USD 17.42 billion by 2032, at a CAGR of 4.78% during the forecast period (2027-2032).
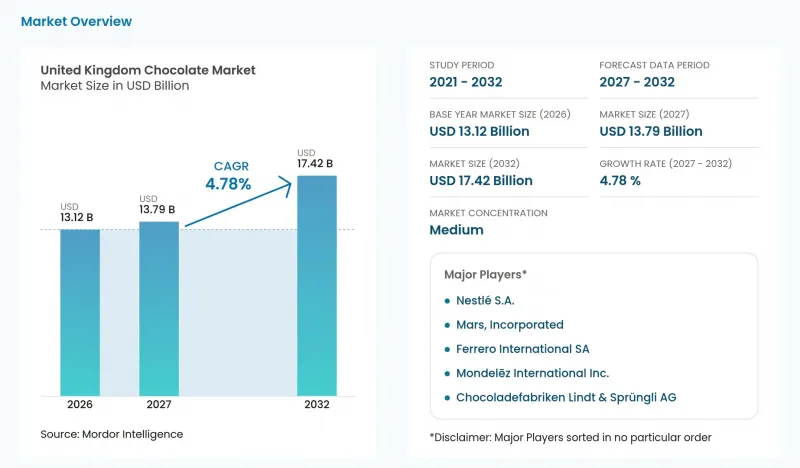
The market volume was valued at 520.3 thousand tons in 2026 and estimated to grow from 526 thousand tons in 2027 to reach 555.6 thousand tons by 2032, at a CAGR of 1.1% during the forecast period (2027-2032). This report is segmented by Product Type (Milk and White Chocolate and more), Form (Tablets and Bars and more), Price Range (Mass and more), Ingredient Type (Dairy-based and more), Category (Conventional Chocolate and more), and Distribution Channel (Supermarkets/Hypermarkets and more). The market forecasts are provided in terms of value (USD) and volume (tons), based on availability.
United Kingdom Chocolate Market Trends and Insights
Rising popularity of premium and artisanal chocolates
Premium producers can build demand through a combination of differentiated chocolate and direct access to shoppers. In 2025, Lindt & Sprungli reported that its UK and Ireland business outpaced the market and gained share. Lindt attributed these gains to Lindt Dubai Style Chocolate and a record Lindor Pistachio launch, showing buyer response to new flavors and formats within its premium range. Its rapid direct-to-consumer expansion included the opening of a Piccadilly flagship store in London. Lindt can therefore capture the retail sale as well as supply the chocolate, making the store expansion a downstream revenue opportunity.
Growth in plant-based and vegan chocolate alternatives
Plant-based alternatives can extend the chocolate offer to shoppers seeking a plant-powered ingredient profile. Zertus UK & Ireland reported that NOMO held 19% value share in the plant-powered and free-from chocolate brand category for the 52 weeks ending November 1, 2025, citing Nielsen Scantrack and Homescan data. For retailers extending these chocolate ranges, NOMO's position makes specialist-brand selection consequential alongside ingredient suitability.
Fluctuating cocoa prices due to climate change
Climate-related cocoa cost pressure reaches consumers through higher prices, limiting manufacturers' room to recover additional increases. ECIU reported that average pre-promotion prices for popular Easter chocolates at UK supermarkets rose by two-thirds between 2023 and January-March 2026. ECIU attributed that Easter price increase primarily to cocoa costs following climate-driven extreme weather in West Africa. Separately, UK chocolate confectionery value sales rose 9.2% in 2025 while volume sales fell 2.6% amid commodity cost increases. For UK manufacturers, these conditions make price-led revenue growth a poor basis for assuming that consumers can absorb further cost increases. Suppliers therefore face a choice between absorbing input-cost volatility and risking additional pressure on quantities sold when raising shelf prices.
Other drivers and restraints analyzed in the detailed report include:
- Innovation in flavors and formats
- Seasonal demand spikes during holidays
- Rising health concerns over sugar content and obesity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Milk and white chocolate accounted for a 53.2% share of the United Kingdom chocolate market size in 2026. On October 19, 2026, Mondelez's Bournville manufacturing lead reported production of over 1.5 million Cadbury Dairy Milk tablets daily. Because this rate concerns a single branded tablet, it illustrates how much manufacturing capacity can be concentrated behind one milk-chocolate product. Matching that line's physical throughput would require a substantial manufacturing commitment from a challenger.
Dark chocolate is the fastest-growing segment, with a projected CAGR of 5.75% during 2027-2032. Ocado Retail reported that searches for dark chocolate Easter eggs on Ocado.com increased 247% in the period from December 15, 2025, to March 8, 2026, compared with December 16, 2024, to March 9, 2025. Search activity gives retailers a direct signal of interest in a precisely defined seasonal dark-chocolate offer. That makes the link between product description and discovery commercially relevant when shoppers seek a dark-chocolate version of an existing gifting format. Retailers that list dark Easter eggs under searchable names can meet that interest where shoppers are looking for the product.
Tablets and bars represented a 64.86% United Kingdom chocolate market share in 2026. In May 2026, Mars said its Slough factory produced Mars bars and Snickers bars for UK demand. The same site also produced chocolate for distribution in Ireland and the Netherlands. Decisions about the plant's capacity must account for UK bar demand alongside overseas chocolate distribution.
Pralines and truffles are the fastest-growing segment, with a projected CAGR of 5.55% during 2027-2032. Lindt Lindor Truffles 200 g appeared among Unitas Wholesale's gifting-confectionery bestsellers by convenience value sales in the 52 weeks ending May 18, 2025, alongside Ferrero Rocher Pralines 200 g. Retailers can position truffle and praline lines as choices for shoppers seeking confectionery gifts. A new gift-pack line entering convenience stores competes for shelf space against established Lindor and Ferrero Rocher offers.
Complete Report Scope:
- By Product Type
- Dark Chocolate
- Milk and White Chocolate
- By Form
- Tablets and Bars
- Molded Blocks
- Pralines and Truffles
- Other Forms
- By Price Range
- Mass
- Premium
- By Ingredient Type
- Dairy-based
- Plant-based
- By Category
- Single Origin Chocolate
- Conventional Chocolate
- By Distribution Channel
- Supermarkets/Hypermarkets
- Online Retail Stores
- Convenience Store
- Other Distribution Channels
List of Companies Covered in this Report:
- Mars, Incorporated
- Ferrero International SA
- Nestle S.A.
- Chocoladefabriken Lindt & Sprungli AG
- Mondelez International Inc.
- The Hershey Company
- Barry Callebaut AG
- The London Chocolate Company
- YIldIz Holding A.S. (Godiva / Ulker)
- Lotte Corporation
- Arcor S.A.I.C.
- Whitakers Chocolates Ltd
- Artisan du Chocolat Ltd
- Morinaga & Co., Ltd.
- Tony's Chocolonely UK Ltd
- Divine Chocolate Ltd
- Pecan Deluxe Candy Company
- Land Chocolate Ltd
- Fazer Group
- Green & Black's Organic
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising popularity of premium and artisanal chocolates
- 4.2.2 Growth in plant-based and vegan chocolate alternatives
- 4.2.3 Innovation in flavors and formats
- 4.2.4 Seasonal demand spikes during holidays
- 4.2.5 Demand for allergen-free options
- 4.2.6 Advancements in Chocolate Processing
- 4.3 Market Restraints
- 4.3.1 Fluctuating cocoa prices due to climate change
- 4.3.2 Rising health concerns over sugar content and obesity
- 4.3.3 Intense competition from multinational brands
- 4.3.4 Regulatory pressures on food safety
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Consumer Behaviour Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE AND VOLUME)
- 5.1 By Product Type
- 5.1.1 Dark Chocolate
- 5.1.2 Milk and White Chocolate
- 5.2 By Form
- 5.2.1 Tablets and Bars
- 5.2.2 Molded Blocks
- 5.2.3 Pralines and Truffles
- 5.2.4 Other Forms
- 5.3 By Price Range
- 5.3.1 Mass
- 5.3.2 Premium
- 5.4 By Ingredient Type
- 5.4.1 Dairy-based
- 5.4.2 Plant-based
- 5.5 By Category
- 5.5.1 Single Origin Chocolate
- 5.5.2 Conventional Chocolate
- 5.6 By Distribution Channel
- 5.6.1 Supermarkets/Hypermarkets
- 5.6.2 Online Retail Stores
- 5.6.3 Convenience Store
- 5.6.4 Other Distribution Channels
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Mars, Incorporated
- 6.4.2 Ferrero International SA
- 6.4.3 Nestle S.A.
- 6.4.4 Chocoladefabriken Lindt & Sprungli AG
- 6.4.5 Mondelez International Inc.
- 6.4.6 The Hershey Company
- 6.4.7 Barry Callebaut AG
- 6.4.8 The London Chocolate Company
- 6.4.9 YIldIz Holding A.S. (Godiva / Ulker)
- 6.4.10 Lotte Corporation
- 6.4.11 Arcor S.A.I.C.
- 6.4.12 Whitakers Chocolates Ltd
- 6.4.13 Artisan du Chocolat Ltd
- 6.4.14 Morinaga & Co., Ltd.
- 6.4.15 Tony's Chocolonely UK Ltd
- 6.4.16 Divine Chocolate Ltd
- 6.4.17 Pecan Deluxe Candy Company
- 6.4.18 Land Chocolate Ltd
- 6.4.19 Fazer Group
- 6.4.20 Green & Black's Organic
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

