PUBLISHER: Roots Analysis | PRODUCT CODE: 2132673
PUBLISHER: Roots Analysis | PRODUCT CODE: 2132673
China RNA Delivery Technologies Market by Type of RNA Delivered, Delivery Technology, Application, Therapeutic Area, End User, and Company Size - Trends and Forecast Till 2035
CHINA RNA DELIVERY TECHNOLOGIES MARKET: OVERVIEW
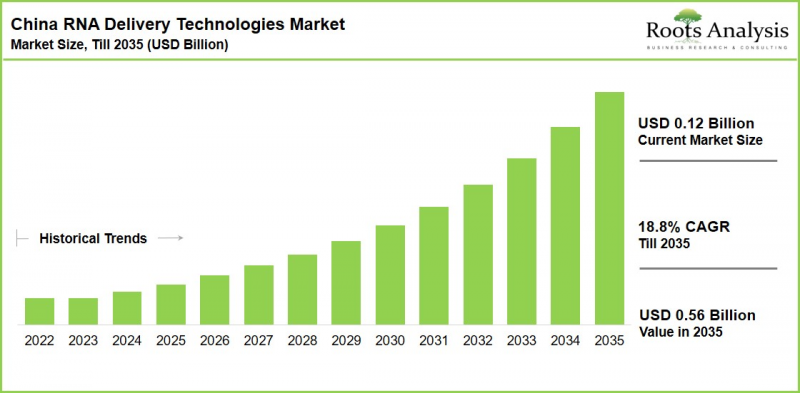
The China RNA delivery technologies market is estimated to grow from USD 0.12 billion in the current year to USD 0.56 billion by 2035, registering a CAGR of 18.8% during the forecast period. Growth is being propelled by the country's expanding mRNA vaccine and siRNA therapeutic pipelines, sustained government backing for nucleic acid drug innovation, and the rapid build-out of domestic lipid nanoparticle (LNP) and polymer-based formulation capacity that reduces reliance on imported delivery platforms.
China RNA Delivery Technologies Market: Growth and Trends
China's biopharmaceutical innovators are advancing an increasingly diverse portfolio of RNA-based candidates, spanning prophylactic and therapeutic mRNA vaccines, siRNA-based chronic disease treatments, antisense oligonucleotides, and early-stage circular RNA (circRNA) and self-amplifying RNA (saRNA) programs. As these pipelines mature from proof-of-concept to clinical and commercial scale, sponsors are placing growing emphasis on the delivery layer, since the choice of lipid, polymer, or viral vector platform directly determines tissue tropism, immunogenicity, and manufacturability.
Lipid nanoparticle formulation remains the most widely adopted delivery approach, reflecting its validated track record in mRNA vaccine deployment and its adaptability across multiple RNA payload types. At the same time, polymer-based nanoparticles, GalNAc-conjugate platforms, and exosome-based carriers are gaining traction as domestic developers look for alternatives to licensed international lipid technologies and seek to reduce patent-related restrictions linked to foreign-owned LNP intellectual property.
Regional capability is becoming increasingly concentrated around a small number of biotechnology clusters. The Yangtze River Delta, the Beijing-Tianjin-Hebei region, and the Guangdong-Hong Kong-Macao Greater Bay Area collectively host the majority of formulation development, microfluidic manufacturing, and analytical testing capacity, supported by provincial biomanufacturing incentives and proximity to contract development and manufacturing organization (CDMO) infrastructure.
Domestic groups are also broadening their service offerings through strategic collaborations with global platform originators and specialty lipid suppliers, enabling access to validated ionizable lipid chemistries while building in-house formulation, fill/finish, and quality-control capabilities. As RNA-based modalities transition from a pandemic-driven niche to a mainstream drug development platform, the China RNA delivery technologies market is positioned for sustained, long-term expansion.
Growth Drivers: Factors Fueling Market Expansion
Expansion of the China RNA delivery technologies market is being driven by the growing clinical and commercial pipeline of mRNA vaccines, siRNA therapeutics, and gene-modulating oligonucleotides, alongside continued policy support under national biotechnology innovation initiatives. Delivery technology providers give biotech and pharmaceutical sponsors direct access to validated lipid and polymer chemistries, microfluidic mixing platforms, and formulation know-how that would otherwise require significant upfront capital and specialized expertise to build in-house.
The increasing prevalence of oncological, infectious, cardiovascular, and rare genetic diseases is widening the addressable set of indications for RNA-based interventions, while improvements in endosomal escape efficiency and organ-selective targeting are expanding delivery platforms beyond liver-centric applications. Growing venture and strategic investment in China-based RNA therapeutics developers is further reinforcing demand for specialized delivery technology partners capable of supporting programs from preclinical development through commercial-scale manufacturing.
Market Challenges: Critical Barriers Hindering Progress
Despite favorable growth prospects, the market faces several challenges. Patent freedom-to-operate constraints tied to internationally held lipid nanoparticle intellectual property continue to limit the commercial flexibility of some domestic developers, prompting increased investment in proprietary, non-infringing lipid and polymer chemistries. High capital requirements for microfluidic formulation and analytical infrastructure, combined with evolving NMPA regulatory expectations for nucleic acid-based products, add cost and time to development programs.
Additionally, the technical complexity of achieving reproducible encapsulation efficiency, particle size distribution, and stability at commercial scale remains a persistent barrier, particularly for emerging modalities such as circRNA and exosome-based delivery. Supply chain dependence on imported specialty lipids and reagents introduces further uncertainty, and addressing , technical, and supply chain challenges will be critical for stakeholders seeking to capture the full commercial opportunity within this space.
China RNA Delivery Technologies Market: Key Insights
This report delves into the current state of the China RNA delivery technologies market and identifies potential growth opportunities for distribution partners, channel intermediaries, and specialty logistics providers. Some key findings include:
- Local RNA tech developers rely heavily on direct licensing and co-development with pharma sponsors. Traditional distributors are bypassed despite their cold-chain capabilities.
- Ultra-low-temperature (ULT) logistics providers are vital for LNP stability. Entry into this sector strictly requires GMP-compliant infrastructure and verified handling protocols.
- Rapid manufacturing growth in the Yangtze River Delta and Greater Bay Area is creating demand for regional logistics partners versed in provincial regulations.
- Geopolitical and IP pressures are accelerating local sourcing of ionizable lipids and specialty excipients, forcing developers to localize their supply chains.
- M&A and licensing among top developers heighten entry barriers, opening selective opportunities for distributors with cluster- or modality-specific expertise.
- Channel partners now compete on regulatory compliance, real-time temperature tracking, and inventory management rather than baseline freight costs.
Recent Deal Activity Signaling Investor Momentum
- Roivant subsidiary Genevant Sciences and Arbutus Biopharma reached a global settlement covering unauthorized use of lipid nanoparticle delivery technology, underscoring the continued commercial value and enforcement of foreign-held LNP intellectual property relevant to Chinese licensees.
- Eli Lilly entered a major licensing and acquisition agreement with Orna Therapeutics for its circular RNA (circRNA) platform, highlighting rising strategic interest in next-generation RNA modalities that domestic Chinese developers are also pursuing.
- AbbVie entered a collaboration with Capstan Therapeutics centered on a targeted lipid nanoparticle platform for in vivo RNA delivery, reflecting the broader industry shift toward organ-selective, non-liver-centric delivery chemistries.
- CSPC Pharmaceutical Group continued to scale its self-developed lipid nanoparticle manufacturing capability, reporting progress toward domestic substitution of key ionizable lipid components for its mRNA pipeline.
- Domestic mRNA vaccine developers, including CanSino Biologics, continued to expand microfluidic formulation partnerships to support late-stage and commercial-scale lipid nanoparticle production.
Collectively, these transactions underscore sustained investor and strategic-acquirer confidence in RNA delivery platform technology, with intellectual property positioning, organ-selective targeting, and domestic manufacturing self-sufficiency emerging as themes directly relevant to distributors and investors evaluating exposure to the China market.
China RNA Delivery Technologies Market Segments
The market sizing and opportunity analysis has been segmented across the following parameters:
By Type of RNA Delivered
- mRNA
- siRNA
- Antisense Oligonucleotides (ASOs)
- Self-Amplifying RNA (saRNA)
- Circular RNA (circRNA)
- Other RNA Types
By Delivery Technology
- Lipid Nanoparticles (LNPs)
- Polymer-Based Nanoparticles
- Viral Vector-Based Delivery
- Peptide / Conjugate-Based Delivery
- Exosome / Extracellular Vesicle-Based Delivery
- Other Delivery Technologies
By Application
- Vaccines
- Therapeutics
- Research Use
By Therapeutic Area
- Oncological Disorders
- Infectious Diseases
- Genetic and Rare Disorders
- Cardiovascular Disorders
- Other Disorders
By End User
- Pharmaceutical and Biotechnology Companies
- CDMOs / CROs
- Academic and Research Institutes
By Company Size
- Small Companies
- Mid-Sized Companies
- Large and Very Large Companies
China RNA Delivery Technologies Market: Key Segment Insights
Lipid Nanoparticles Lead the Delivery Technology Segment
Based on current pipeline and commercial activity, the lipid nanoparticle (LNP) segment currently secures the largest share of overall market revenue. This leading position reflects LNPs' validated performance in mRNA vaccine delivery, their adaptability across multiple RNA payload types, and continued investment by domestic developers in proprietary ionizable lipid chemistries. Looking ahead, polymer-based nanoparticles and exosome-based delivery are expected to register comparatively higher CAGRs, supported by growing interest in non-liver-centric, organ-selective targeting.
mRNA Continues to Dominate the Type of RNA Delivered
According to current pipeline analysis, mRNA accounts for the largest market share. This high share is underpinned by its central role in prophylactic vaccines, cancer immunotherapies, and protein-replacement therapeutics. siRNA is the second-largest contributor, driven by an expanding portfolio of chronic disease candidates. circRNA and saRNA, while smaller in current share, are anticipated to grow at a comparatively faster pace as platform validation studies progress through clinical development.
Therapeutic Applications Register Higher CAGR in Long-Term Growth
According to the proprietary report, accines currently represent the largest application segment given the scale of China's mRNA vaccine manufacturing base. However, therapeutics applications spanning oncology, rare genetic disorders, and cardiovascular disease are projected to expand at a higher CAGR through 2035 as siRNA and antisense oligonucleotide pipelines mature toward commercial approval.
Yangtze River Delta and Greater Bay Area Dominate Regional Capability
The Yangtze River Delta cluster, encompassing Shanghai, Jiangsu, and Zhejiang, currently holds the largest share of installed formulation and fill / finish capacity, supported by dense biotechnology infrastructure and proximity to leading CDMOs. The Guangdong-Hong Kong-Macao Greater Bay Area is expected to register the fastest capacity growth over the forecast period, reflecting substantial provincial investment in biomanufacturing incentives and cross-border collaboration with international platform originators.
Large and Very Large Companies Hold the Highest Market Share
Companies with large and very large operational scale currently account for the highest market share. This dominance reflects their established formulation infrastructure, regulatory expertise, and long-standing sponsor relationships. On the other hand, smaller and mid-sized players continue to expand their footprint through partnerships and targeted capability investments in proprietary lipid and polymer chemistries to compete for a growing share of outsourced delivery development work.
Example Players in China RNA Delivery Technologies Market
- Abogen Biosciences
- CanSino Biologics
- CSPC Pharmaceutical Group
- Fosun Pharma / Fosun Kite
- RNACure Biopharma
- Sinopharm CNBG
- Stemirna Therapeutics
- Walvax Biotechnology
- Yuxi Watson Biotechnology
CHINA RNA DELIVERY TECHNOLOGIES MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: An in-depth analysis of the market focusing on key segments, including type of RNA delivered, delivery technology, application, therapeutic area, end user, company size, and key regional clusters within China.
- Delivery Technology Landscape: A detailed assessment of active RNA delivery technology providers, featuring information on year of establishment, company size, location of headquarters, and range of platforms offered.
- Company Profiles: In-depth profiles of prominent players engaged in RNA delivery technology development, covering year of establishment, headquarters location, company size, platform portfolio, and key recent initiatives.
- Case Study I (mRNA Vaccine Manufacturing and Delivery): A focused assessment of the mRNA vaccine delivery landscape in China, covering development stages, NMPA regulatory requirements, outsourcing drivers, and key challenges.
- Case Study II (Comparison of Delivery Platforms): A concise comparison of lipid nanoparticle, viral vector, and polymer-based delivery systems, highlighting key characteristics, manufacturing processes, and associated challenges.
- Case Study III (In-House versus Outsourced Development): A concise assessment of in-house and outsourced delivery development strategies, covering key benefits, risks, and trends to support informed make-versus-buy decisions.
- Make versus Buy Decision-Making Framework: A concise framework evaluating in-house development versus outsourcing for RNA delivery technologies, using predefined assumptions and scenario-based analyses.
- Partnerships and Collaborations: An analysis of partnerships and collaborations inked by China-based RNA delivery technology providers, based on year, type, RNA and platform involved, and most active players.
- Funding and Investments Analysis: A detailed analysis of funding and investments in this domain, based on year, type of funding, amount invested, geography, and most active investors.
- Recent Expansions Analysis: A comprehensive assessment of recent expansion initiatives, analyzing trends by type, quarter, investment, and facility location across China's key biotechnology clusters.
- Big Pharma / Big Biotech Initiatives: An analysis of initiatives undertaken by leading pharmaceutical and biotechnology companies, covering partnerships, acquisitions, and expansions relevant to RNA delivery.
- Capacity Analysis: A comprehensive assessment of installed formulation capacity across company sizes, delivery technologies, and China's key regional clusters.
- Demand Analysis: A comprehensive evaluation of demand across applications, examining requirements for emerging modalities including circRNA and saRNA delivery.
- Total Cost of Ownership Analysis: A comprehensive evaluation of the total cost of ownership for RNA delivery technology providers over a 10-year period, covering CAPEX and OPEX for mid-sized and large/very large facilities.
- SWOT Analysis: A strategic assessment of the China RNA delivery technologies market, evaluating strengths, weaknesses, opportunities, and threats relative to global peers.
KEY QUESTIONS ANSWERED IN THIS REPORT
- Which are the leading companies in the China RNA delivery technologies market?
- Which delivery technology dominates the market, and which is growing the fastest?
- What are the key trends observed in this market?
- What factors are likely to influence the evolution of this market?
- What are the primary challenges faced by China-based RNA delivery technology providers?
- What is the current and future market size?
- What is the CAGR of this market through 2035?
- How is current and future market opportunity distributed across key segments?
- What opportunities exist for distributors and logistics partners entering this space?
- Which regional clusters within China offer the greatest near-term commercial opportunity?
REASONS TO BUY THIS REPORT
This report is designed to give distributors, channel partners, and investors a decisive analytical edge in a fast-evolving market. Its core differentiators include:
- Top-Down and Bottom-Up Triangulated Forecasting: Market estimates are built using a hybrid methodology that cross-validates top-down macro assessments against bottom-up, company-level capacity and pipeline data, minimizing forecast bias.
- Comprehensive Chapter Coverage: Extensive coverage spanning market sizing, competitive benchmarking, pipeline and patent landscape, funding and M&A analysis, and regulatory mapping across China's key biotechnology clusters.
- Primary Research-Backed Insights: Findings are validated through direct interviews with CEOs, CSOs, and commercial leaders across small, mid-sized, and large China-based delivery technology providers.
- Actionable Segmentation: Seven-parameter segmentation (type of RNA delivered, delivery technology, application, therapeutic area, end user, company size, and regional cluster) enables precise opportunity sizing for any go-to-market or investment thesis.
ADDITIONAL BENEFITS
- Complementary PPT Insights Pack
- Complementary Excel Data Packs for all Analytical Modules in the Report
- 15% Free Content Customization
- Detailed Report Walkthrough Session with Research Team
- Free Updated Report if the Report is 6-12 Months Old or Older
TABLE OF CONTENTS
1. PREFACE
- 1.1. Introduction
- 1.2. Market Share Insights
- 1.3. Key Market Insights
- 1.4. Report Coverage
- 1.5. Key Questions Answered
- 1.6. Chapter Outlines
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.2.1. Market Landscape and Market Trends
- 2.2.2. Market Forecast and Opportunity Analysis
- 2.2.3. Comparative Analysis
- 2.3. Database Building
- 2.3.1. Data Collection
- 2.3.2. Data Validation
- 2.3.3. Data Analysis
- 2.4. Project Methodology
- 2.4.1. Secondary Research
- 2.4.1.1. Annual Reports
- 2.4.1.2. Academic Research Papers
- 2.4.1.3. Company Websites
- 2.4.1.4. Investor Presentations
- 2.4.1.5. Regulatory Filings
- 2.4.1.6. White Papers
- 2.4.1.7. Industry Publications
- 2.4.1.8. Conferences and Seminars
- 2.4.1.9. Government Portals (incl. NMPA)
- 2.4.1.10. Media and Press Releases
- 2.4.1.11. Newsletters
- 2.4.1.12. Industry Databases
- 2.4.1.13. Proprietary Databases
- 2.4.1.14. Paid Databases and Sources
- 2.4.1.15. Social Media Portals
- 2.4.1.16. Other Secondary Sources
- 2.4.2. Primary Research
- 2.4.2.1. Types of Primary Research
- 2.4.2.1.1. Qualitative Research
- 2.4.2.1.2. Quantitative Research
- 2.4.2.1.3. Hybrid Approach
- 2.4.2.2. Advantages of Primary Research
- 2.4.2.3. Techniques for Primary Research
- 2.4.2.3.1. Interviews
- 2.4.2.3.2. Surveys
- 2.4.2.3.3. Focus Groups
- 2.4.2.3.4. Observational Research
- 2.4.2.3.5. Social Media Interactions
- 2.4.2.4. Key Opinion Leaders Considered in Primary Research
- 2.4.2.4.1. Company Executives (CXOs)
- 2.4.2.4.2. Board of Directors
- 2.4.2.4.3. Company Presidents and Vice Presidents
- 2.4.2.4.4. Research and Development Heads
- 2.4.2.4.5. Technical Experts
- 2.4.2.4.6. Subject Matter Experts
- 2.4.2.4.7. Scientists
- 2.4.2.4.8. Regulatory Affairs Specialists
- 2.4.2.5. Ethics and Integrity
- 2.4.2.5.1. Research Ethics
- 2.4.2.5.2. Data Integrity
- 2.4.2.1. Types of Primary Research
- 2.4.3. Analytical Tools and Databases
- 2.4.1. Secondary Research
- 2.5. Robust Quality Control
3. MARKET DYNAMICS
- 3.1. Chapter Overview
- 3.2. Forecast Methodology
- 3.2.1. Top-down Approach
- 3.2.2. Bottom-up Approach
- 3.2.3. Hybrid Approach
- 3.3. Market Assessment Framework
- 3.3.1. Total Addressable Market (TAM)
- 3.3.2. Serviceable Addressable Market (SAM)
- 3.3.3. Serviceable Obtainable Market (SOM)
- 3.3.4. Currently Acquired Market (CAM)
- 3.4. Forecasting Tools and Techniques
- 3.4.1. Qualitative Forecasting
- 3.4.2. Correlation
- 3.4.3. Regression
- 3.4.4. Extrapolation
- 3.4.5. Convergence
- 3.4.6. Sensitivity Analysis
- 3.4.7. Scenario Planning
- 3.4.8. Data Visualization
- 3.4.9. Time Series Analysis
- 3.4.10. Forecast Error Analysis
- 3.5. Key Considerations
- 3.5.1. Demographics
- 3.5.2. Government Regulations (NMPA / CDE)
- 3.5.3. Reimbursement Scenarios
- 3.5.4. Market Access
- 3.5.5. Supply Chain
- 3.5.6. Industry Consolidation
- 3.5.7. Pandemic / Unforeseen Disruptions Impact
- 3.6. Limitations
4. MACRO-ECONOMIC INDICATORS
- 4.1. Chapter Overview
- 4.2. Market Dynamics
- 4.2.1. Time Period
- 4.2.1.1. Historical Trends
- 4.2.1.2. Current and Forecasted Estimates
- 4.2.2. Currency Coverage (CNY / USD)
- 4.2.2.1. Major Currencies Affecting the Market
- 4.2.2.2. Factors Affecting Currency Fluctuations on the Industry
- 4.2.2.3. Impact of Currency Fluctuations on the Industry
- 4.2.3. Foreign Currency Exchange Rate
- 4.2.3.1. Impact of Foreign Exchange Rate Volatility on the Market
- 4.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 4.2.4. China's Biotechnology and Innovation Policy Landscape
- 4.2.4.1. Healthy China 2030 and Related Initiatives
- 4.2.4.2. 14th / 15th Five-Year Plan Biotechnology Priorities
- 4.2.4.3. NMPA Regulatory Reform for Nucleic Acid Therapeutics
- 4.2.5. Inflation
- 4.2.5.1. Measurement and Analysis of Inflationary Pressures in the Economy
- 4.2.5.2. Potential Impact of Inflation on the Market Evolution
- 4.2.6. Interest Rates
- 4.2.6.1. Interest Rates and Their Impact on the Market
- 4.2.6.2. Strategies for Managing Interest Rate Risk
- 4.2.7. Trade Dynamics and Tariff Exposure
- 4.2.7.1. Import Scenario for Lipids, Reagents, and Raw Materials
- 4.2.7.2. Export Scenario for Domestically Developed RNA Delivery Platforms
- 4.2.7.3. Trade Policies
- 4.2.7.4. Strategies for Mitigating Risks Associated with Trade Barriers
- 4.2.7.5. Impact of Trade Barriers on the Market
- 4.2.8. Other Indicators
- 4.2.8.1. Fiscal Policy
- 4.2.8.2. Healthcare Spending
- 4.2.8.3. Gross Domestic Product
- 4.2.8.4. Employment in Biotechnology Sector
- 4.2.8.5. Stock Market and Capital Markets Performance (STAR Market / HKEX)
- 4.2.8.6. Cross-Border Licensing Dynamics
- 4.2.1. Time Period
- 4.3. Conclusion
5. EXECUTIVE SUMMARY
- 5.1. Executive Summary: Market Landscape
- 5.2. Executive Summary: Market Trends
- 5.3. Executive Summary: Market Forecast and Opportunity Analysis
6. INTRODUCTION
- 6.1. Chapter Overview
- 6.2. Overview of RNA-Based Therapeutics and Vaccines
- 6.3. Types of RNA Molecules
- 6.3.1. mRNA
- 6.3.2. siRNA
- 6.3.3. Antisense Oligonucleotides (ASOs)
- 6.3.4. Self-Amplifying RNA (saRNA)
- 6.3.5. Circular RNA (circRNA)
- 6.3.6. Other RNA Types
- 6.4. Overview of RNA Delivery Technologies
- 6.4.1. Lipid Nanoparticles (LNPs)
- 6.4.2. Polymer-Based Nanoparticles
- 6.4.3. Viral Vector-Based Delivery
- 6.4.4. Peptide / Conjugate-Based Delivery
- 6.4.5. Exosome / Extracellular Vesicle-Based Delivery
- 6.4.6. Other Delivery Technologies
- 6.5. Barriers to Effective Intracellular RNA Delivery
- 6.5.1. Endosomal Escape
- 6.5.2. Immunogenicity and Innate Immune Activation
- 6.5.3. Tissue and Organ Tropism
- 6.5.4. Stability and Degradation
- 6.6. Manufacturing Process for RNA Delivery Systems
- 6.6.1. Lipid / Polymer Synthesis
- 6.6.2. Nanoparticle Formulation and Microfluidic Mixing
- 6.6.3. Purification and Fill / Finish
- 6.7. Need for Specialized Delivery Technology Partners
- 6.7.1. Commonly Outsourced Delivery Development Activities
- 6.7.2. Advantages of Partnering with Delivery Technology Providers
- 6.7.3. Risks and Challenges Associated with Outsourcing Delivery Development
- 6.8. Key Considerations While Selecting an RNA Delivery Technology Partner
- 6.9. Future Perspectives
7. MARKET LANDSCAPE
- 7.1. Chapter Overview
- 7.2. China RNA Delivery Technology Providers: Overall Market Landscape
- 7.2.1. Analysis by Year of Establishment
- 7.2.2. Analysis by Company Size
- 7.2.3. Analysis by Location of Headquarters (Province / City)
- 7.2.4. Analysis by Company Size and Location of Headquarters
- 7.3. China RNA Delivery Technology Providers: Analysis of Key Players
- 7.3.1. Analysis by Regulatory Compliance / Certifications
- 7.3.2. Analysis by Type of RNA Supported
- 7.3.3. Analysis by Delivery Technology Offered
- 7.3.4. Analysis by Application
- 7.3.5. Analysis by Scale of Operation
- 7.3.6. Analysis by Type of Formulation Platform Offered
8. COMPANY COMPETITIVENESS ANALYSIS
- 8.1. Chapter Overview
- 8.2. Assumptions and Key Parameters
- 8.3. Methodology
- 8.4. Overview of Peer Groups Based in China
9. COMPANY PROFILES
- 9.1. Chapter Overview
- 9.2. RNA Delivery Technology Providers headquartered in Beijing-Tianjin-Hebei
- 9.2.1. Abogen Biosciences
- 9.2.2. Financial Information
- 9.2.3. Service / Product Portfolio
- 9.2.4. Recent Developments and Future Outlook
- Similar details are presented for other below mentioned companies based on information in the public domain
- 9.3. CanSino Biologics
- 9.4. CSPC Pharmaceutical Group
- 9.5. Fosun Pharma / Fosun Kite
- 9.6. RNACure Biopharma
- 9.7. Sinopharm CNBG
- 9.8. Stemirna Therapeutics
- 9.9. Walvax Biotechnology
- 9.10. Yuxi Watson Biotechnology
10. PARTNERSHIPS AND COLLABORATIONS
- 10.1. Chapter Overview
- 10.2. Partnership Models
- 10.3. China RNA Delivery Technologies: Partnerships and Collaborations
- 10.3.1. Analysis by Year of Partnership
- 10.3.2. Analysis by Type of Partnership
- 10.3.3. Analysis by Year and Type of Partnership
- 10.3.4. Analysis by Type of Partner
- 10.3.5. Analysis by Type of Partnership and Type of Partner
- 10.3.6. Most Active Players: Analysis by Number of Partnerships
- 10.4. Analysis by Region
- 10.4.1. Local and International Agreements
- 10.4.2. Intracontinental and Intercontinental Agreements
11. FUNDING AND INVESTMENT ANALYSIS
- 11.1. Chapter Overview
- 11.2. Funding Models
- 11.3. China RNA Delivery Technologies: Funding and Investment Analysis
- 11.3.1. Analysis by Year of Funding
- 11.3.1.1. Cumulative Year-wise Trend of Funding Instances
- 11.3.1.2. Cumulative Year-wise Trend of Amount Invested
- 11.3.2. Analysis by Type of Funding
- 11.3.2.1. Analysis of Funding Instances
- 11.3.2.2. Analysis of Amount Invested
- 11.3.3. Analysis by Year and Type of Funding
- 11.3.4. Analysis of Amount Invested by Year and Type of Funding
- 11.3.5. Analysis by Region
- 11.3.6. Most Active Players
- 11.3.6.1. Analysis by Number of Funding Instances
- 11.3.6.2. Analysis by Amount Raised
- 11.3.6.3. Leading Investors: Analysis by Number of Funding Instances
- 11.3.1. Analysis by Year of Funding
12. MEGA TRENDS
- 12.1. Chapter Overview
- 12.2. China RNA Delivery Technologies: Key Megatrends
13. MARKET IMPACT ANALYSIS:
- 13.1. Chapter Overview
- 13.2. Market Drivers
- 13.3. Market Restraints
- 13.4. Market Opportunities
- 13.5. Market Challenges
- 13.6. Conclusion
14. CHINA RNA DELIVERY TECHNOLOGIES MARKET
- 14.1. Chapter Overview
- 14.2. Assumptions and Methodology
- 14.3. China RNA Delivery Technologies Market, Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 14.3.1. Perspective on Market Growth
- 14.3.2. Scenario Analysis
- 14.3.2.1. Conservative Scenario
- 14.3.2.2. Optimistic Scenario
- 14.4. Key Market Segmentations
15. CHINA RNA DELIVERY TECHNOLOGIES MARKET, BY TYPE OF RNA DELIVERED
- 15.1. Chapter Overview
- 15.2. Key Assumptions and Methodology
- 15.3. China RNA Delivery Technologies Market: Distribution by Type of RNA Delivered
- 15.3.1. mRNA: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 15.3.2. siRNA: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 15.3.3. Antisense Oligonucleotides (ASOs): Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 15.3.4. Self-Amplifying RNA (saRNA): Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 15.3.5. Circular RNA (circRNA): Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 15.3.6. Other RNA Types: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 15.4. Data Triangulation and Validation
16. CHINA RNA DELIVERY TECHNOLOGIES MARKET, BY DELIVERY TECHNOLOGY
- 16.1. Chapter Overview
- 16.2. Key Assumptions and Methodology
- 16.3. China RNA Delivery Technologies Market: Distribution by Delivery Technology
- 16.3.1. Lipid Nanoparticles (LNPs): Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 16.3.2. Polymer-Based Nanoparticles: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 16.3.3. Viral Vector-Based Delivery: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 16.3.4. Peptide / Conjugate-Based Delivery: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 16.3.5. Exosome / Extracellular Vesicle-Based Delivery: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 16.3.6. Other Delivery Technologies: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 16.4. Data Triangulation and Validation
17. CHINA RNA DELIVERY TECHNOLOGIES MARKET, BY APPLICATION
- 17.1. Chapter Overview
- 17.2. Key Assumptions and Methodology
- 17.3. China RNA Delivery Technologies Market: Distribution by Application
- 17.3.1. Vaccines: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 17.3.2. Therapeutics: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 17.3.3. Research Use: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 17.4. Data Triangulation and Validation
18. CHINA RNA DELIVERY TECHNOLOGIES MARKET, BY THERAPEUTIC AREA
- 18.1. Chapter Overview
- 18.2. Key Assumptions and Methodology
- 18.3. China RNA Delivery Technologies Market: Distribution by Therapeutic Area
- 18.3.1. Oncological Disorders: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 18.3.2. Infectious Diseases: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 18.3.3. Genetic and Rare Disorders: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 18.3.4. Cardiovascular Disorders: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 18.3.5. Other Disorders: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 18.4. Data Triangulation and Validation
19. CHINA RNA DELIVERY TECHNOLOGIES MARKET, BY END USER
- 19.1. Chapter Overview
- 19.2. Key Assumptions and Methodology
- 19.3. China RNA Delivery Technologies Market: Distribution by End User
- 19.3.1. Pharmaceutical and Biotechnology Companies: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 19.3.2. CDMOs / CROs: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 19.3.3. Academic and Research Institutes: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 19.4. Data Triangulation and Validation
20. CHINA RNA DELIVERY TECHNOLOGIES MARKET, BY COMPANY SIZE
- 20.1. Chapter Overview
- 20.2. Key Assumptions and Methodology
- 20.3. China RNA Delivery Technologies Market: Distribution by Company Size
- 20.3.1. Small Companies: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 20.3.2. Mid-Sized Companies: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 20.3.3. Large and Very Large Companies: Historical Trends (since 2022) and Forecasted Estimates (till 2035)
- 20.4. Data Triangulation and Validation
21. CONCLUSION
22. EXECUTIVE INSIGHTS
23. APPENDIX I: TABULATED DATA
24. APPENDIX II: LIST OF COMPANIES AND ORGANIZATIONS

