PUBLISHER: Roots Analysis | PRODUCT CODE: 2161682
PUBLISHER: Roots Analysis | PRODUCT CODE: 2161682
Global In-Vivo CAR-T Therapeutics Market - Trends and Forecast Till 2035
IN-VIVO CAR-T THERAPEUTICS MARKET: OVERVIEW
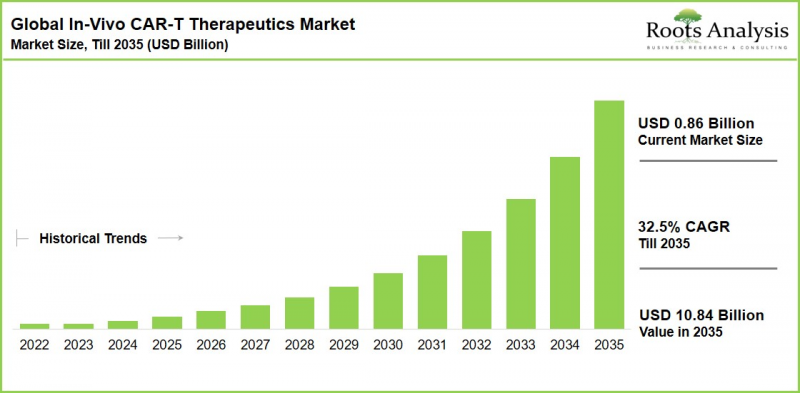
As per Roots Analysis, the global in-vivo CAR-T therapeutics market is estimated to grow from USD 0.86 billion in the current year to USD 10.84 billion by 2035, registering a CAGR of 32.5% across the forecast period.
In-Vivo CAR-T Market: Growth and Trends
In-vivo CAR-T therapeutics have emerged as one of the fastest-evolving frontiers in cell and gene therapy, marking a significant shift from conventional ex-vivo approaches. The field initially comprised a cohort of platform-focused biotechs, including Capstan Therapeutics, Interius BioTherapeutics, Orna Therapeutics, Kelonia Therapeutics, EsoBiotec, Orbital Therapeutics, and Umoja Biopharma. However, the competitive landscape is rapidly consolidating as major pharmaceutical companies including AbbVie, Gilead (Kite), Bristol Myers Squibb, AstraZeneca, and Eli Lilly secure in-vivo CAR-T delivery technologies through acquisitions and licensing partnerships.
Viral-vector platforms, particularly lentiviral systems developed by companies such as Umoja, Interius, EsoBiotec, and Kelonia, currently represent the largest share of pipeline activity due to their durable gene delivery capabilities. In contrast, non-viral platforms based on LNP-formulated mRNA or circular RNA, including approaches pursued by Capstan, Orna, and Orbital, are gaining momentum rapidly, supported by their re-dosing potential, scalable manufacturing economics, and suitability for chronic autoimmune diseases where permanent genetic integration may be less desirable.
While early in-vivo CAR-T programs targeted CD19- and BCMA-driven hematologic malignancies, several leading candidates are now advancing into B-cell-mediated autoimmune diseases such as lupus and systemic sclerosis, a shift that materially broadens the addressable patient population and commercial opportunity relative to first-generation ex-vivo CAR-T therapies.
Growth Drivers: Factors Fueling Market Expansion
The in-vivo CAR-T therapeutics market is being driven by the potential to eliminate costly and time-intensive ex-vivo cell manufacturing, reducing treatment from a multi-week process to a single infusion-based intervention. By removing the need for patient-specific leukapheresis and specialized cleanroom manufacturing, these platforms could lower per-patient costs and expand CAR-T access beyond the limited number of centers currently equipped to deliver autologous cell therapies.
Rising global cancer incidence, an expanding base of clinical trials evaluating in-vivo constructs, and continued technological refinement of lentiviral, AAV, and LNP delivery systems including improved cell-type targeting ligands and reduced off-target biodistribution are reinforcing the growth trajectory. Sustained big-pharma validation is further strengthening the in-vivo CAR-T therapeutics market, with more than USD 15 billion in disclosed acquisition and licensing commitments since early 2025. This heightened strategic interest is also driving capital toward early-stage platform companies and specialized CDMOs focused on viral-vector and LNP manufacturing capabilities.
Market Challenges: Critical Barriers Hindering Progress
Despite favorable growth prospects, the in-vivo CAR-T therapeutics market faces several barriers that could temper near-term commercial progress. Viral-vector platforms must manage pre-existing immunity and anti-vector immune responses that can blunt in-vivo transduction efficiency, while non-viral LNP platforms face open questions around achieving sufficiently durable and cell-type-specific gene expression outside the liver. Manufacturing at commercial scale for GMP-grade lentiviral vectors and LNP-formulated RNA remains capital-intensive and supply-constrained. Further, regulatory pathways for in-vivo gene delivery platforms are still being defined by agencies as long-term durability, re-dosing, and off-target editing safety data accumulate. Addressing these technical, manufacturing, and regulatory challenges will be central to converting early clinical proof-of-concept into approved, reimbursed therapies.
In-Vivo CAR-T Therapeutics Market: Key Insights
This report examines the current state of the global in-vivo CAR-T therapeutics market and identifies the growth opportunities available to biopharmaceutical innovators, CDMOs, and investors. Some of the key findings include:
- Lentiviral vector-based platforms currently anchor the largest share of the clinical-stage in-vivo CAR-T pipeline, though non-viral LNP-mRNA and circular RNA platforms are the fastest-growing delivery category given their re-dosing potential and applicability to autoimmune indications.
- North America leads the global market on the strength of concentrated clinical trial activity, dense biopharma and CDMO infrastructure, and early regulatory engagement, while Asia-Pacific's higher CAGR is supported by China's expanding cell and gene therapy manufacturing base.
- CD19- and BCMA-targeted programs dominate current clinical activity in B-cell malignancies and multiple myeloma respectively, while CD20 and CD22 constructs are advancing as differentiated or combination options, and autoimmune-focused CD19 programs are emerging as a distinct, high-growth indication category.
- Since March 2025, big pharma has committed more than USD 17 billion in disclosed acquisition and partnership value to in-vivo CAR-T platforms, consolidating a previously fragmented field of venture-backed biotechs into a small number of pharma-owned delivery platforms.
- Specialty viral vector and LNP manufacturing capacity, along with GMP-grade plasmid, mRNA, and lipid-component supply, represents a critical near-term bottleneck and a corresponding opportunity for CDMOs and raw-material suppliers positioning around this modality.
- The competitive field has organized into distinct technology camps, such as lentiviral integration platforms, LNP-mRNA and circular RNA platforms, and hybrid enveloped delivery vehicle (EDV) systems each carrying different manufacturing, durability, and regulatory profiles that will shape licensing and M&A activity over the next 12-24 months.
Global In-Vivo CAR-T Therapeutics Market Segments
The market sizing and opportunity analysis has been segmented across the following parameters:
By Delivery Platform
- Viral Vector-Based
- Lentiviral Vectors
- Adeno-Associated Virus (AAV)
- Non-Viral
- LNP-mRNA
- Circular RNA
- Other Non-Viral Systems
- Hybrid / Enveloped Delivery Vehicle (EDV) Platforms
By Target Antigen
- CD19
- CD20
- CD22
- BCMA
- Other Targets
By Route of Administration
- Systemic (Intravenous) Delivery
- Localized (Intratumoral) Delivery
By Therapeutic Area
- Oncological Disorders (Hematologic Malignancies)
- Autoimmune Disorders
- Other Indications
By End User
- Hospitals
- Specialty Care Centers
- Academic and Research Institutes
By Geographical Regions
- North America
- US
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and North Africa
- Saudi Arabia
- UAE
- Latin America
- Brazil
- Argentina
- Rest of Latin America
In-Vivo CAR-T Therapeutics Market: Key Segment Insights
Viral Vector Platforms Lead Current Delivery Share
Lentiviral vector-based delivery currently accounts for the largest share of the market. This highest share is supported by a well-characterized safety and manufacturing track record inherited from ex-vivo CAR-T and broader gene therapy programs. Non-viral LNP-mRNA and circular RNA platforms represent the fastest-growing delivery category as developers prioritize re-dosable non-integrating constructs suited to chronic autoimmune disease treatment.
Localized Delivery Is the Fastest-Growing Route of Administration
According to the Roots Analysis market report, localized, intratumoral delivery accounted for the largest market share and is projected to register the fastest growth through 2035. This dual dominance reflects the approach's ability to deliver therapeutic constructs directly into the tumor microenvironment, thereby increasing local drug exposure and enhancing antitumor activity while potentially reducing systemic exposure and treatment-related toxicity compared with intravenous administration. The resulting combination of higher tumor-site concentration, improved therapeutic precision, and a potentially more favorable safety profile is expected to support continued adoption of intratumoral delivery approaches.
Hospitals Dominate the End-User Landscape
According to our projection, hospitals held the highest market share and are likely to remain dominant in the future. This largest share reflects their role as the primary setting equipped for advanced-therapy administration, multidisciplinary patient management, and management of cytokine release syndrome and neurotoxicity risk associated with CAR-T mechanisms of action.
North America Leads; Asia-Pacific Set for Fastest Growth
North America is expected to maintain its position as the leading regional market through 2035. This dominance is supported by a strong concentration of in-vivo CAR-T developers, clinical research infrastructure, and specialized viral-vector and LNP manufacturing capabilities in the US. Asia-Pacific is projected to record the fastest CAGR, driven primarily by China's expanding cell and gene therapy ecosystem, increasing manufacturing capacity, and rising clinical trial activity.
Example Players in the In-Vivo CAR-T Therapeutics Market
- AbbVie (Capstan Therapeutics)
- AstraZeneca (EsoBiotec)
- Beam Therapeutics
- Bristol Myers Squibb (Orbital Therapeutics)
- Cellectis
- CRISPR Therapeutics
- Eli Lilly and Company (Orna Therapeutics, Kelonia Therapeutics)
- Gilead Sciences / Kite Pharma (Interius BioTherapeutics)
- Intellia Therapeutics
- Legend Biotech
- Myeloid Therapeutics
- Novartis
- Poseida Therapeutics
- Precision BioSciences
- Pregene Biopharma
- Sana Biotechnology
- Umoja Biopharma
- Vyriad
IN-VIVO CAR-T THERAPEUTICS MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: In-depth analysis across delivery platform, target antigen, route of administration, therapeutic area, end user, and geography.
- Competitive Landscape: A detailed assessment of active in-vivo CAR-T developers, including platform technology, pipeline stage, and ownership status following recent M&A activity.
- Company Profiles: Profiles of prominent players, covering platform overview, pipeline, recent financing/M&A history, and strategic partnerships.
- Technology Benchmarking: Comparative assessment of lentiviral, AAV, LNP-mRNA, circular RNA, and hybrid EDV delivery platforms across manufacturing complexity, durability, re-dosability, and safety profile.
- Pipeline Analysis: Clinical and preclinical pipeline mapped by phase of development, target antigen, indication, and sponsor.
- Partnerships and Collaborations: Analysis of licensing deals, co-development agreements, and other partnerships by year, deal type, and platform.
- Funding and M&A Analysis: A detailed review of venture financing, acquisitions, and licensing transactions, including deal value, structure, and most active acquirers.
- SWOT Analysis: Strategic assessment of strengths, weaknesses, opportunities, and threats facing in-vivo CAR-T developers and delivery-platform licensors.
KEY QUESTIONS ANSWERED IN THIS REPORT
- Which companies and delivery platforms are leading the in-vivo CAR-T therapeutics market?
- Which region dominates the market today, and which region is growing the fastest?
- What are the key technology and clinical trends shaping this market?
- What factors are likely to influence the evolution of the in-vivo CAR-T market?
- What are the primary technical, manufacturing, and regulatory challenges facing developers?
- What is the current and projected future size of the in-vivo CAR-T therapeutics market?
- What is the CAGR of this market through 2035?
- How is current and future market opportunity distributed across delivery platform, target antigen, and therapeutic area?
- What licensing, partnership, and acquisition opportunities exist for pharmaceutical companies and investors entering this space?
REASONS TO BUY THIS REPORT
This report is designed to give biopharmaceutical companies, investors, and manufacturing partners a decisive analytical edge in a fast-consolidating market. Its core differentiators include:
- Top-Down and Bottom-Up Triangulated Forecasting: Market estimates are built using a hybrid methodology that cross-validates top-down macro assessments against bottom-up, platform-level pipeline and deal data to minimize forecast bias.
- M&A and Licensing Deal Lens: Unlike conventional cell therapy landscape reports, this study maps the full wave of in-vivo CAR-T acquisitions and licensing deals, and the strategic logic behind each major pharma's platform bet.
- Technology Platform Benchmarking: Comparative evaluation of lentiviral, AAV, LNP-mRNA, circular RNA, and hybrid delivery systems, supporting technology diligence for in-licensing, partnership, or in-house platform investment decisions.
- Primary Research-Backed Insights: Findings are informed by review of company disclosures, clinical trial data, and deal documentation, ensuring insights reflect real development and commercial conditions.
- Actionable Segmentation: Multi-parameter segmentation (delivery platform, target antigen, route of administration, therapeutic area, end user, geography) enables precise opportunity sizing for any go-to-market, licensing, or investment thesis.
ADDITIONAL BENEFITS
- Complementary data packs covering key market segments
- Content customization available on request
- Detailed report walkthrough session with the research team
- Free report update if the report is 6-12 months old or older
TABLE OF CONTENTS
1. PREFACE
- 1.1. Introduction
- 1.2. Market Share Insights
- 1.3. Key Market Insights
- 1.4. Report Coverage
- 1.5. Key Questions Answered
- 1.6. Chapter Outlines
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.2.1. Market Landscape and Market Trends
- 2.2.2. Market Forecast and Opportunity Analysis
- 2.2.3. Comparative Analysis
- 2.3. Database Building
- 2.3.1. Data Collection
- 2.3.2. Data Validation
- 2.3.3. Data Analysis
- 2.4. Project Methodology
- 2.4.1. Secondary Research
- 2.4.1.1. Annual Reports
- 2.4.1.2. Academic Research Papers
- 2.4.1.3. Company Websites
- 2.4.1.4. Investor Presentations
- 2.4.1.5. Regulatory Filings
- 2.4.1.6. White Papers
- 2.4.1.7. Industry Publications
- 2.4.1.8. Conferences and Seminars
- 2.4.1.9. Government Portals
- 2.4.1.10. Media and Press Releases
- 2.4.1.11. Newsletters
- 2.4.1.12. Industry Databases
- 2.4.1.13. Roots Proprietary Databases
- 2.4.1.14. Paid Databases and Sources
- 2.4.1.15. Social Media Portals
- 2.4.1.16. Other Secondary Sources
- 2.4.2. Primary Research
- 2.4.2.1. Types of Primary Research
- 2.4.2.1.1. Qualitative Research
- 2.4.2.1.2. Quantitative Research
- 2.4.2.1.3. Hybrid Approach
- 2.4.2.2. Advantages of Primary Research
- 2.4.2.3. Techniques for Primary Research
- 2.4.2.3.1. Interviews
- 2.4.2.3.2. Surveys
- 2.4.2.3.3. Focus Groups
- 2.4.2.3.4. Observational Research
- 2.4.2.3.5. Social Media Interactions
- 2.4.2.4. Key Opinion Leaders Considered in Primary Research
- 2.4.2.4.1. Company Executives (CXOs)
- 2.4.2.4.2. Board of Directors
- 2.4.2.4.3. Company Presidents and Vice Presidents
- 2.4.2.4.4. Research and Development Heads
- 2.4.2.4.5. Technical Experts
- 2.4.2.4.6. Subject Matter Experts
- 2.4.2.4.7. Scientists
- 2.4.2.4.8. Doctors and Other Healthcare Providers
- 2.4.2.5. Ethics and Integrity
- 2.4.2.5.1. Research Ethics
- 2.4.2.5.2. Data Integrity
- 2.4.2.1. Types of Primary Research
- 2.4.3. Analytical Tools and Databases
- 2.4.1. Secondary Research
- 2.5. Robust Quality Control
3. MARKET DYNAMICS
- 3.1. Chapter Overview
- 3.2. Forecast Methodology
- 3.2.1. Top-down Approach
- 3.2.2. Bottom-up Approach
- 3.2.3. Hybrid Approach
- 3.3. Market Assessment Framework
- 3.3.1. Total Addressable Market (TAM)
- 3.3.2. Serviceable Addressable Market (SAM)
- 3.3.3. Serviceable Obtainable Market (SOM)
- 3.3.4. Currently Acquired Market (CAM)
- 3.4. Forecasting Tools and Techniques
- 3.4.1. Qualitative Forecasting
- 3.4.2. Correlation
- 3.4.3. Regression
- 3.4.4. Extrapolation
- 3.4.5. Convergence
- 3.4.6. Sensitivity Analysis
- 3.4.7. Scenario Planning
- 3.4.8. Data Visualization
- 3.4.9. Time Series Analysis
- 3.4.10. Forecast Error Analysis
- 3.5. Key Considerations
- 3.5.1. Demographics
- 3.5.2. Government Regulations
- 3.5.3. Reimbursement Scenarios
- 3.5.4. Market Access
- 3.5.5. Supply Chain
- 3.5.6. Industry Consolidation
- 3.5.7. Pandemic / Unforeseen Disruptions Impact
- 3.6. Limitations
4. MACRO-ECONOMIC INDICATORS
- 4.1. Chapter Overview
- 4.2. Market Dynamics
- 4.2.1. Time Period
- 4.2.1.1. Historical Trends
- 4.2.1.2. Current and Forecasted Estimates
- 4.2.2. Currency Coverage
- 4.2.2.1. Major Currencies Affecting the Market
- 4.2.2.2. Factors Affecting Currency Fluctuations
- 4.2.2.3. Impact of Currency Fluctuations on the Industry
- 4.2.3. Foreign Currency Exchange Rate
- 4.2.3.1. Impact of Foreign Exchange Rate Volatility on the Market
- 4.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 4.2.4. Recession
- 4.2.4.1. Assessment of Current Economic Conditions and Potential Impact on the Market
- 4.2.4.2. Historical Analysis of Past Recessions and Lessons Learnt
- 4.2.5. Inflation
- 4.2.5.1. Measurement and Analysis of Inflationary Pressures in the Economy
- 4.2.5.2. Potential Impact of Inflation on the Market Evolution
- 4.2.6. Interest Rates
- 4.2.6.1. Interest Rates and Their Impact on the Market
- 4.2.6.2. Strategies for Managing Interest Rate Risk
- 4.2.7. Commodity Flow Analysis
- 4.2.7.1. Type of Commodity
- 4.2.7.2. Origins and Destinations
- 4.2.7.3. Values and Weights
- 4.2.7.4. Modes of Transportation
- 4.2.8. Global Trade Dynamics
- 4.2.8.1. Import Scenario
- 4.2.8.2. Export Scenario
- 4.2.8.3. Trade Policies
- 4.2.8.4. Strategies for Mitigating the Risks Associated with Trade Barriers
- 4.2.8.5. Impact of Trade Barriers on the Market
- 4.2.9. War Impact Analysis
- 4.2.9.1. Russian-Ukraine War
- 4.2.9.2. Israel-Hamas War
- 4.2.10. COVID Impact / Related Factors
- 4.2.10.1. Global Economic Impact
- 4.2.10.2. Industry-specific Impact
- 4.2.10.3. Government Response and Stimulus Measures
- 4.2.10.4. Future Outlook and Adaptation Strategies
- 4.2.11. Other Indicators
- 4.2.11.1. Fiscal Policy
- 4.2.11.2. Consumer Spending
- 4.2.11.3. Gross Domestic Product (GDP)
- 4.2.11.4. Employment
- 4.2.11.5. Taxes
- 4.2.11.6. Stock Market Performance
- 4.2.11.7. Cross-Border Dynamics
- 4.2.1. Time Period
- 4.3. Conclusion
5. EXECUTIVE SUMMARY
6. INTRODUCTION
- 6.1. Chapter Overview
- 6.2. Overview of T-cell Immunotherapies
- 6.2.1. Historical Evolution
- 6.2.2. Key Considerations for Developing T-cell Immunotherapies
- 6.2.3. Strategies Employed for the Redirection of T-cells
- 6.2.4. Manufacturing of Engineered T-cells
- 6.3. Chimeric Antigen Receptor T-cell (CAR-T) Therapy
- 6.3.1. Development History
- 6.3.2. Structure of CAR
- 6.3.2.1. Ectodomain
- 6.3.2.2. Transmembrane (TM) Domain
- 6.3.2.3. Endodomain
- 6.3.3. Development of CAR-T Cells
- 6.3.4. Universal CAR-T Cells
- 6.3.5. Route of Administration
- 6.3.6. Challenges Associated with In Vivo CAR-T Therapeutics
- 6.3.6.1. Competitive Risks
- 6.3.6.2. Clinical Risks
- 6.3.6.3. Regulatory Risks
- 6.3.6.4. Commercial Risks
- 6.4. Concluding Remarks
7. IN VIVO CAR-T THERAPEUTICS: MARKET LANDSCAPE
- 7.1. Chapter Overview
- 7.2. In Vivo CAR-T Therapeutics: Market Landscape
- 7.2.1. Analysis by Type of Delivery Platform
- 7.2.2. Analysis by Type of Target Antigen
- 7.2.3. Analysis by Therapeutic Area
- 7.2.4. Analysis by Route of Administration
- 7.2.5. Analysis by End User
- 7.3. In Vivo CAR-T Therapeutics: Overall Developer Landscape
- 7.3.1. Analysis by Year of Establishment
- 7.3.2. Analysis by Company Size
- 7.3.3. Analysis by Location of Headquarters
8. CLINICAL TRIAL ANALYSIS
- 8.1. Chapter Overview
- 8.2. Scope and Methodology
- 8.3. In Vivo CAR-T Therapeutics: Clinical Trial Analysis
- 8.3.1. Analysis by Trial Registration Year
- 8.3.2. Analysis of Enrolled Patient Population by Trial Registration Year
- 8.3.3. Analysis by Trial Phase
- 8.3.4. Analysis of Enrolled Patient Population by Trial Phase
- 8.3.5. Analysis by Trial Registration Year and Trial Phase
- 8.3.6. Analysis by Trial Status
- 8.3.7. Analysis by Patient Gender
- 8.3.8. Analysis by Therapeutic Area
- 8.3.9. Analysis by Study Design
- 8.3.10. Most Active Industry Players: Analysis by Number of Registered Trials
- 8.3.11. Most Active Non-Industry Players: Analysis by Number of Registered Trials
- 8.3.12. Analysis by Geography
9. COMPANY PROFILES
- 9.1. Chapter Overview
- 9.2. AbbVie (Capstan Therapeutics)
- 9.3. AstraZeneca (EsoBiotec)
- 9.4. Beam Therapeutics
- 9.5. Bristol Myers Squibb Company (Orbital Therapeutics)
- 9.6. Cellectis
- 9.7. CRISPR Therapeutics
- 9.8. Eli Lilly and Company (Orna Therapeutics, Kelonia Therapeutics)
- 9.9. Gilead Sciences (Kite Pharma)
- 9.10. Intellia Therapeutics
- 9.11. Legend Biotech
- 9.12. Myeloid Therapeutics
- 9.13. Novartis
- 9.14. Poseida Therapeutics
- 9.15. Precision BioSciences
- 9.16. Pregene Biopharma
- 9.17. Sana Biotechnology
- 9.18. Umoja Biopharma
- 9.19. Vyriad
10. PARTNERSHIPS AND COLLABORATIONS
- 10.1. Chapter Overview
- 10.2. Partnership Models
- 10.3. In Vivo CAR-T Therapeutics: Partnerships and Collaborations
- 10.3.1. Analysis by Year of Partnership
- 10.3.2. Analysis by Type of Partnership
- 10.3.3. Analysis by Year and Type of Partnership
- 10.3.4. Analysis by Type of Partner
- 10.3.5. Most Popular Therapies: Analysis by Number of Partnerships
- 10.3.6. Most Active Industry Players: Analysis by Number of Partnerships
- 10.3.7. Most Active Non-Industry Players: Analysis by Number of Partnerships
- 10.3.8. Analysis by Geography
- 10.3.8.1. Intercontinental and Intracontinental Agreements
- 10.3.8.2. International and Local Agreements
11. FUNDING AND INVESTMENTS ANALYSIS
- 11.1. Chapter Overview
- 11.2. Types of Funding
- 11.3. In Vivo CAR-T Therapeutics: Funding and Investment Analysis
- 11.3.1. Analysis by Year of Funding
- 11.3.2. Analysis of Amount Invested
- 11.3.3. Analysis by Type of Funding
- 11.3.4. Analysis by Amount Invested and Type of Funding
- 11.3.5. Analysis of Amount Invested by Year and Type of Funding
- 11.3.6. Analysis by Type of Investor
- 11.3.7. Analysis by Geography
- 11.3.8. Most Active Players
- 11.3.9. Leading Investors: Analysis by Number of Funding Instances
12. PATENT ANALYSIS
- 12.1. Chapter Overview
- 12.2. Scope and Methodology
- 12.3. In Vivo CAR-T Therapeutics: Patent Analysis
- 12.3.1. Analysis by Patent Publication Year
- 12.3.2. Analysis by Patent Application Year
- 12.3.3. Analysis of Granted Patents and Patent Applications by Publication Year
- 12.3.4. Analysis by Patent Jurisdiction
- 12.3.5. Analysis by CPC Symbols
- 12.3.6. Analysis by Type of Applicant
- 12.3.7. Leading Industry Players: Analysis by Number of Patents
- 12.3.8. Leading Non-Industry Players: Analysis by Number of Patents
- 12.3.9. Leading Patent Assignees: Analysis by Number of Patents
- 12.4. Patent Benchmarking Analysis
- 12.4.1. Analysis by Patent Characteristics
- 12.5. Patent Valuation
- 12.6. Leading Patents by Number of Citations
13. CASE STUDY: CELL THERAPY MANUFACTURING
- 13.1. Chapter Overview
- 13.2. Overview of Cell Therapy Manufacturing
- 13.3. Cell Therapy Manufacturing Models
- 13.3.1. Centralized Manufacturing Model
- 13.3.2. Decentralized Manufacturing Model
- 13.4. Scalability of Cell Therapy Manufacturing Processes
- 13.4.1. Scale-Up
- 13.4.2. Scale-Out
- 13.5. Types of Cell Therapy Manufacturers
- 13.6. Key Challenges Related to Manufacturing of Cell Therapies
- 13.7. Key Considerations for Cell Therapy Manufacturing
- 13.7.1. Characterization
- 13.7.2. Cost of Goods
- 13.8. Automation of Cell Therapy Manufacturing Process
- 13.9. Cell Therapy Manufacturing Supply Chain
- 13.10. Comparison of Players Having In-house Capabilities and Contract Manufacturers
- 13.11. Regulatory Landscape
- 13.12. Future Perspectives
14. COST PRICE ANALYSIS
- 14.1. Chapter Overview
- 14.2. Factors Contributing to the High Price of Cell / Gene Therapies
- 14.3. Pricing Models for T-cell Immunotherapies
- 14.3.1. Based on Associated Costs
- 14.3.2. Based on Availability of Competing Products
- 14.3.3. Based on Patient Population
- 14.3.4. Based on Opinions of Industry Experts
- 14.4. Reimbursement related Considerations for T-cell Immunotherapies
- 14.4.1. Case Study: The National Institute for Health and Care Excellence (NICE) Appraisal of CAR-T Therapies
15. MARKET IMPACT ANALYSIS: DRIVERS, RESTRAINTS, OPPORTUNITIES AND CHALLENGES
- 15.1. Chapter Overview
- 15.2. Market Drivers
- 15.3. Market Restraints
- 15.4. Market Opportunities
- 15.5. Market Challenges
- 15.6. Conclusion
16. GLOBAL IN-VIVO CAR-T CELL THERAPY MARKET
- 16.1. Chapter Overview
- 16.2. Key Assumptions and Methodology
- 16.3. Global In-Vivo CAR-T Cell Therapy Market, Historical Trends (since 2018) and Forecasted Estimates (till 2035)
- 16.4. Scenario Analysis
- 16.4.1. Conservative Scenario
- 16.4.2. Optimistic Scenario
- 16.5. Key Market Segmentations
17. IN-VIVO CAR-T CELL THERAPY MARKET, BY TYPE OF DELIVERY PLATFORM
- 17.1. Chapter Overview
- 17.2. Key Assumptions and Methodology
- 17.3. In-Vivo CAR-T Cell Therapy Market: Distribution by Delivery Platform
- 17.3.1. In-Vivo CAR-T Cell Therapy Market for Viral Vector-Based: Forecasted Estimates (till 2035)
- 17.3.1.1. In-Vivo CAR-T Cell Therapy Market for Lentiviral Vectors: Forecasted Estimates (till 2035)
- 17.3.1.2. In-Vivo CAR-T Cell Therapy Market for Adeno-Associated Virus (AAV): Forecasted Estimates (till 2035)
- 17.3.2. In-Vivo CAR-T Cell Therapy Market for Non-Viral: Forecasted Estimates (till 2035)
- 17.3.2.1. In-Vivo CAR-T Cell Therapy Market for LNP-mRNA: Forecasted Estimates (till 2035)
- 17.3.2. In-Vivo CAR-T Cell Therapy Market for Circular RNA: Forecasted Estimates (till 2035)
- 17.3.2. In-Vivo CAR-T Cell Therapy Market for Other Non-Viral Systems: Forecasted Estimates (till 2035)
- 17.3.3. In-Vivo CAR-T Cell Therapy Market for Hybrid / Enveloped Delivery Vehicle (EDV) Platforms: Forecasted Estimates (till 2035)
- 17.3.1. In-Vivo CAR-T Cell Therapy Market for Viral Vector-Based: Forecasted Estimates (till 2035)
- 17.4. Data Triangulation and Validation
18. IN-VIVO CAR-T CELL THERAPY MARKET, BY TARGET ANTIGEN
- 18.1. Chapter Overview
- 18.2. Key Assumptions and Methodology
- 18.3. In-Vivo CAR-T Cell Therapy Market: Distribution by Target Antigen
- 18.3.1. In-Vivo CAR-T Cell Therapy Market for CD19: Forecasted Estimates (till 2035)
- 18.3.2. In-Vivo CAR-T Cell Therapy Market for CD 20: Forecasted Estimates (till 2035)
- 18.3.3. In-Vivo CAR-T Cell Therapy Market for CD22: Forecasted Estimates (till 2035)
- 18.3.4. In-Vivo CAR-T Cell Therapy Market for BCMA: Forecasted Estimates (till 2035)
- 18.3.5. In-Vivo CAR-T Cell Therapy Market for Other Targets: Forecasted Estimates (till 2035)
- 18.4. Data Triangulation and Validation
19. IN-VIVO CAR-T CELL THERAPY MARKET, BY ROUTE OF ADMINISTRATION
- 19.1. Chapter Overview
- 19.2. Key Assumptions and Methodology
- 19.3. In-Vivo CAR-T Cell Therapy Market: Distribution by Route of Administration
- 19.3.1. In-Vivo CAR-T Cell Therapy Market for Systemic (Intravenous) Delivery: Forecasted Estimates (till 2035)
- 19.3.2. In-Vivo CAR-T Cell Therapy Market for Localized (Intratumoral) Delivery: Forecasted Estimates (till 2035)
- 19.4. Data Triangulation and Validation
20. IN-VIVO CAR-T CELL THERAPY MARKET, BY THERAPEUTIC AREA
- 20.1. Chapter Overview
- 20.2. Key Assumptions and Methodology
- 20.3. In-Vivo CAR-T Cell Therapy Market: Distribution by Therapeutic Area
- 20.3.1. In-Vivo CAR-T Cell Therapy Market for Oncological Disorders (Hematologic Malignancies): Forecasted Estimates (till 2035)
- 20.3.2. In-Vivo CAR-T Cell Therapy Market for Autoimmune Disorders: Forecasted Estimates (till 2035)
- 20.3.3. In-Vivo CAR-T Cell Therapy Market for Other Indications: Forecasted Estimates (till 2035)
- 20.4. Data Triangulation and Validation
21. IN-VIVO CAR-T CELL THERAPY MARKET, BY END USER
- 21.1. Chapter Overview
- 21.2. Key Assumptions and Methodology
- 21.3. In-Vivo CAR-T Cell Therapy Market: Distribution by End User
- 21.3.1. In-Vivo CAR-T Cell Therapy Market for Hospitals: Forecasted Estimates (till 2035)
- 21.3.2. In-Vivo CAR-T Cell Therapy Market for Specialty Care Centers: Forecasted Estimates (till 2035)
- 21.3.3. In-Vivo CAR-T Cell Therapy Market for Academic and Research Institutes: Forecasted Estimates (till 2035)
- 21.4. Data Triangulation and Validation1
22. IN-VIVO CAR-T CELL THERAPY MARKET: DISTRIBUTION BY GEOGRAPHICAL REGIONS
- 22.1. Chapter Overview
- 22.2. Key Assumptions and Methodology
- 22.3. In-Vivo CAR-T Cell Therapy Market: Distribution by Key Geographical Regions
- 22.3.1. In-Vivo CAR-T Cell Therapy Market in North America: Forecasted Estimates (till 2035)
- 22.3.2. In-Vivo CAR-T Cell Therapy Market in Europe: Forecasted Estimates (till 2035)
- 22.3.3. In-Vivo CAR-T Cell Therapy Market in Asia-Pacific: Forecasted Estimates (till 2035)
- 22.3.4. In-Vivo CAR-T Cell Therapy Market in Latin America: Forecasted Estimates (till 2035)
- 22.3.5. In-Vivo CAR-T Cell Therapy Market in Middle East and North Africa: Forecasted Estimates (till 2035)
- 22.3.6. In-Vivo CAR-T Cell Therapy Market in Rest of the World: Forecasted Estimates (till 2035)
- 22.4. Data Triangulation and Validation
23. IN-VIVO CAR-T CELL THERAPY MARKET, SALES FORECAST OF DRUGS
- 23.1. Chapter Overview
- 23.2. Key Assumptions and Methodology
- 23.3. Commercialized In Vivo CAR-T Therapeutics: Sales Forecast
- 23.4. Clinical In Vivo CAR-T Therapeutics: Sales Forecast
- 23.5. Data Triangulation and Validation
24. IN-VIVO CAR-T CELL THERAPY MARKET: SALES FORECAST OF LEADING PLAYERS
- 24.1. Chapter Overview
- 24.2. Key Assumptions and Methodology
- 24.3. In Vivo CAR-T Therapeutics: Leading Players
- 24.3.1. Gilead Sciences Sales Forecast
- 24.3.2. Bristol Myers Squibb Sales Forecast
- 24.3.3. Novartis Sales Forecast
- 24.3.4. Janssen Sales Forecast
- 24.3.5. JW Therapeutics Sales Forecast
- 24.4. Data Triangulation and Validation
25. EXECUTIVE INSIGHTS
26. CONCLUDING REMARKS
27. APPENDIX I: TABULATED DATA
28. APPENDIX II: LIST OF COMPANIES AND ORGANIZATIONS
29. APPENDIX III: LIST OF FUNDING AND INVESTMENTS

