PUBLISHER: Roots Analysis | PRODUCT CODE: 2161889

PUBLISHER: Roots Analysis | PRODUCT CODE: 2161889
Connected Drug Delivery Device Market (3rd Edition) - Trends and Forecast Till 2035
CONNECTED DRUG DELIVERY DEVICE MARKET: OUTLOOK
As per the Roots Analysis report, the global connected drug delivery device market is estimated to grow from USD 5.3 billion in the current year to USD 12.7 billion by 2035, representing a CAGR of 10.2% during the forecast period.
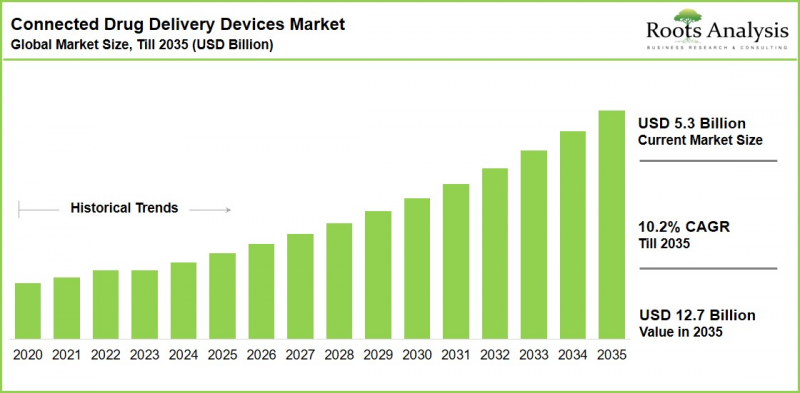
Connected Drug Delivery Device Market: Growth and Trends
Poor adherence to prescribed medication continues to be a persistent challenge across healthcare systems worldwide, contributing to disease progression, avoidable hospitalization and rising treatment costs. It is estimated that close to 66% of individuals in the US receive at least one prescription, yet nearly half do not take their medication as directed by physicians. Complex dosing schedules, limited access to medicines and inadequate patient support are among the leading causes of this non-adherence.
Connected drug delivery devices are gaining traction as pharmaceutical and healthcare stakeholders seek to improve medication adherence, treatment monitoring and patient engagement. These solutions combine established delivery platforms, including autoinjectors, pen injectors, inhalers and wearable injectors, with digital capabilities. For example, smart insulin pens capture dosing data, while add-on sensor modules can transform conventional devices into connected systems without requiring complete device redesign.
Wireless connectivity, particularly Bluetooth, enables these devices to transfer medication-use data to mobile applications, digital health platforms and electronic health records. This supports real-time monitoring, adherence reminders, personalized therapy adjustments and timely clinical intervention. As telehealth adoption expands and payers and providers place greater emphasis on outcomes-based care, connected drug delivery devices are positioned to become an increasingly important component of remote patient monitoring and digital healthcare ecosystems, supporting sustained double-digit market growth through 2035.
Growth Drivers: Factors Fueling Connected Drug Delivery Device Market Expansion
- Rising Burden of Chronic Disorders: The global prevalence of chronic conditions such as diabetes, asthma and hypertension continues to climb; an estimated 130 million people in the US alone live with at least one chronic condition. Long-term management of such conditions demands complex medication regimens and continuous monitoring, prompting device developers to introduce connected delivery and monitoring solutions that support self-administration and improve treatment outcomes. Ypsomed's FDA clearance of SmartPilot, an add-on sensor for its YpsoMate autoinjector platform, illustrates this trend.
- Accelerating Adoption of Digital Health Technologies: Rising health awareness has driven a marked increase in the use of smart healthcare devices and wearables in recent years. Platforms such as connected handheld injectors, smart wearable insulin pumps and smart inhalers now enable continuous monitoring of patient health while reducing dependence on conventional treatment settings, supporting virtual consultations and encouraging greater patient participation in managing their own care.
- Expanding Role of Patient Engagement Ecosystems: The integration of connected devices with patient engagement software and digital health platforms is extending adherence-focused workflows across the full care pathway, strengthening patient outcomes while helping payers and providers manage overall healthcare expenditure.
Market Restraints: Barriers to Connected Drug Delivery Device Market Growth
- High Development and Production Costs: The integration of advanced sensors, connectivity modules and software into drug delivery devices significantly raises development costs. Extensive R&D, rigorous testing and validation, and compliance with stringent regulatory requirements add further expense. Scaling production also requires complex electronic component supply chains, specialized assembly capacity and cybersecurity validation, creating a high barrier to entry for smaller and newer players.
- Data Privacy and Cybersecurity Exposure: Continuous internet connectivity and the integration of sensors, software and communication modules expose connected devices to data privacy risks and potential cyber threats. Compromised monitoring software or configuration settings could allow malicious manipulation of dosage data, device functionality or patient records, posing safety risks. Multi-layered cybersecurity frameworks, end-to-end encryption, secure authentication and frequent firmware updates are becoming essential, non-negotiable cost items for manufacturers.
- Regulatory and Interoperability Complexity: Connected devices sit at the intersection of medical device and software regulation, requiring manufacturers to navigate evolving regulatory frameworks across geographies while ensuring interoperability with the diverse digital health platforms and electronic health record systems used by providers.
Connected Drug Delivery Device Market: Key Insights
The report delves into the current state of the connected drug delivery device market and identifies potential growth opportunities within the industry. Some key insights include:
- Connected / smart wearable injectors currently hold the highest share among device types, a trend that is unlikely to change in the coming years, supported by rising chronic disease prevalence and continued efforts by stakeholders to integrate advanced monitoring features.
- Bluetooth-enabled devices account for the majority of the current market with respect to mode of connectivity, owing to ease of integration, universal smartphone compatibility and the absence of any need for supplementary hardware.
- The parenteral route of administration captures the largest market share, reflecting its established role in delivering biologics and high-value therapies for chronic disease management, while the inhalational route is expected to grow at a faster pace.
- Devices addressing metabolic disorders, driven primarily by the global diabetes burden, represent the leading therapeutic area, while the autoimmune disorders segment is expected to register a higher CAGR through 2035.
- North America is likely to hold the largest share of the current market, while Asia-Pacific is expected to grow at a relatively faster pace through 2035, aided by rising device approvals and expanding biopharmaceutical R&D activity in the region.
Connected Drug Delivery Device Market Segments
The market sizing and opportunity analysis featured in this report has been segmented across the following parameters:
By Type of Device
- Connected / Smart Wearable Injectors
- Connected / Smart Inhalers
- Connected / Smart Pen Injectors
- Connected / Smart Autoinjectors
- Connected / Smart Needle-free Injection Systems
By Mode of Connectivity
- Bluetooth-enabled Devices
- Near Field Communication (NFC)-enabled Devices
- Cellular-enabled Devices
- Wide Area Network (WAN)-enabled Devices
By Route of Administration
- Parenteral
- Inhalational
By Therapeutic Area
- Metabolic Disorders
- Respiratory Disorders
- Autoimmune Disorders
- Other Disorders
By Geographical Regions
- North America
- US
- Canada
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Rest of Asia-Pacific
- Middle East and North Africa
- Egypt
- Israel
- Rest of Middle East and North Africa
- Latin America and Rest of the World
- Brazil
- Argentina
- Other Countries
Connected Drug Delivery Device Market: Key Segmentation Insights
Connected / Smart Wearable Injectors Lead by Device Type
Connected / smart wearable injectors occupy the highest share among device types and are expected to remain dominant during the forecast period. This dominance reflects the growing prevalence of chronic conditions and continued investments in advanced features that enhance medication monitoring, improve patient adherence and enable real-time data sharing with healthcare providers.
Bluetooth Connectivity Dominates the Market
Bluetooth-enabled devices are likely to occupy the highest market share by mode of connectivity in 2026 and are expected to register significant growth during the forecast period. This dominance reflects the ease with which Bluetooth can be established and its ready availability on virtually all smartphones without the need for supplementary hardware.
Parenteral Route Leads the Segment and Inhalational Route to Register Higher CAGR
The parenteral segment occupies the higher share among routes of administration. This dominance is due to its established role as the preferred route for administering biologics and high-value therapies targeting chronic diseases. Meanwhile, inhalational segment is projected to grow at a higher CAGR through the forecast period. This dynamic growth is supported by the simplicity, flexibility and pain-free nature of drug administration via this route, along with its capacity for sustained, localized therapeutic action.
Metabolic Disorders Dominate Therapeutic Area Segment
The metabolic disorders segment is likely to occupy the highest market share by therapeutic area. This largest share is driven primarily by the rising global prevalence of diabetes, one of the leading causes of death worldwide. The market for devices addressing autoimmune disorders is expected to register a comparatively higher CAGR through the forecast period.
North America Leads the Regional Market
North America is projected to capture the majority share of the connected drug delivery device market in the current year. Asia-Pacific, however, is expected to grow at a relatively faster pace through 2035, propelled by a rising number of biopharmaceutical start-ups, high R&D activity for novel drug delivery solutions and increasing device approvals across the region. For instance, the MiniMed(TM) 780G System received updated Class III approval for the full kit in Australia.
Recent Developments in the Connected Drug Delivery Device Market
- West Pharmaceutical Services entered into an agreement with AbbVie to sell the manufacturing and supply rights for its SmartDose 3.5mL On-Body Delivery System, along with associated facilities, for USD 112.5 million.
- ViCentra raised USD 85 million in a Series D funding round led by Innovation Industries to support scaling of manufacturing capabilities, regulatory approvals and commercialization of its Kaleido 2 insulin patch pump.
- SHL Medical and Kindeva Drug Delivery entered into a collaboration to provide fill-finish and pre-validated final assembly services for the Molly autoinjector platform at Kindeva's facilities in Bridgeton and Maryland Heights, Missouri.
- Beta Bionics entered into a product integration agreement with Abbott to integrate its iLet bionic pancreas with Abbott's future dual glucose-ketone sensor, enhancing diabetes management through continuous glucose and ketone monitoring.
Example Players in the Connected Drug Delivery Device Market
- Bigfoot Biomedical
- BIOCORP
- Eitan Medical
- E3D Elcam Drug Delivery Device
- EoFlow
- Gerresheimer
- Insulet
- Medtronic
- Medtrum
- Nemera
- Phillips-Medisize
- Roche
- Sonceboz
- SOOIL Development
- Tandem Diabetes Care
- West Pharmaceutical Services
- Ypsomed
Expert Interview and Industry Insights
The market for connected drug delivery has a transformative future and is likely to remain progressive in the coming years. Discussions with multiple stakeholders in this domain influenced the opinions and insights presented in this study. The connected drug delivery devices market report includes transcripts of the following discussions:
- Senior Director, Global Strategic Marketing, Medical, Large Company, US
- Co-Founder and Chief Executive Officer, Small Company, US
- Chief Executive Officer, Small Company, US
- Chief Executive Officer and President, Mid-sized Company, US
- Chief Executive Officer, Small Company, Italy
- Vice President and Chief Scientist, Large Company, Israel
- Director of Global Communications, and Former Vice President of Strategic Partnerships and Business Development, Mid-sized Company, US
- Former Chief Executive Officer, Small Company, US
- Former Director of Front-end Innovation and Head of Connected Health, Large Company, US
- Former Vice President, Marketing and Alliance Management, Mid-sized Company, US
- Advisor of Strategy and Business Development, Small Company, US
CONNECTED DRUG DELIVERY DEVICE MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: An in-depth analysis of the connected drug delivery device market, focused on key segments including type of device, mode of connectivity, route of administration, therapeutic area and geographical regions.
- Competitive Landscape: A detailed assessment of device developers and distribution partners active in this space, covering parameters such as year of establishment, company size, location of headquarters and product portfolio breadth.
- Company Profiles: In-depth profiles of prominent players engaged in the development and commercialization of connected drug delivery devices, featuring information on their year of establishment, headquarters, company size, product offerings and recent initiatives.
- Partnerships and Collaborations: An analysis of partnerships inked by stakeholders in this domain, based on parameters such as year of partnership, type of partnership and type of device involved.
- Recent Developments: A detailed analysis of recent product launches, funding rounds, regulatory approvals and manufacturing agreements shaping the competitive landscape.
- Market Impact Analysis: An assessment of the key drivers, restraints, opportunities and challenges affecting market growth through 2035.
KEY QUESTIONS ANSWERED IN THIS REPORT
- Which companies are the leading players in the connected drug delivery device market?
- Which region dominates the connected drug delivery device market, and which region is likely to grow the fastest?
- What are the key trends observed in the connected drug delivery device market?
- What factors are likely to drive and restrain the evolution of this market?
- What is the current and future connected drug delivery device market size?
- What is the CAGR of the connected drug delivery device market through 2035?
- How is current and future market opportunity distributed across type of device, mode of connectivity, route of administration and therapeutic area?
- How many connected drug delivery devices are currently approved, launched or under development?
REASONS TO BUY THIS REPORT
This report provides a comprehensive analysis of the connected drug delivery device market, offering detailed revenue projections for the overall market and its specific sub-segments. This information is valuable to both established market leaders and emerging entrants.
- Offers stakeholders a comprehensive overview of the market, including key drivers, barriers, opportunities and challenges, empowering data-driven decision making to capitalize on growth prospects.
- Aids businesses in identifying future opportunities in the connected drug delivery device space and assessing whether these opportunities are worth pursuing.
- Helps in identifying customer demand by understanding the needs, preferences and behavior of the target audience, in order to tailor products or services effectively.
- Equips new entrants with the requisite market information needed to build successful business strategies.
- Enables more effective communication with stakeholders and supports the building of strong business relationships.
ADDITIONAL BENEFITS
- Complimentary Excel data packs for all analytical modules in the report.
- Up to 15% complimentary content customization.
- In-depth report walkthrough with the Roots Analysis research team.
- Complimentary report update if the report is six or more months old.
TABLE OF CONTENTS
1. PREFACE
- 1.1. Introduction
- 1.2. Market Share Insights
- 1.3. Key Market Insights
- 1.4. Report Coverage
- 1.5. Key Questions Answered
- 1.6. Chapter Outlines
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.2.1. Market Landscape and Market Trends
- 2.2.2. Market Forecast and Opportunity Analysis
- 2.2.3. Comparative Analysis
- 2.3. Database Building
- 2.3.1. Data Collection
- 2.3.2. Data Validation
- 2.3.3. Data Analysis
- 2.4. Project Methodology
- 2.4.1. Secondary Research
- 2.4.1.1. Annual Reports
- 2.4.1.2. Academic Research Papers
- 2.4.1.3. Company Websites
- 2.4.1.4. Investor Presentations
- 2.4.1.5. Regulatory Filings
- 2.4.1.6. White Papers
- 2.4.1.7. Industry Publications
- 2.4.1.8. Conferences and Seminars
- 2.4.1.9. Government Portals
- 2.4.1.10. Media and Press Releases
- 2.4.1.11. Newsletters
- 2.4.1.12. Industry Databases
- 2.4.1.13. Roots Proprietary Databases
- 2.4.1.14. Paid Databases and Sources
- 2.4.1.15. Social Media Portals
- 2.4.1.16. Other Secondary Sources
- 2.4.2. Primary Research
- 2.4.2.1. Types of Primary Research
- 2.4.2.1.1. Qualitative Research
- 2.4.2.1.2. Quantitative Research
- 2.4.2.1.3. Hybrid Approach
- 2.4.2.2. Advantages of Primary Research
- 2.4.2.3. Techniques for Primary Research
- 2.4.2.3.1. Interviews
- 2.4.2.3.2. Surveys
- 2.4.2.3.3. Focus Groups
- 2.4.2.3.4. Observational Research
- 2.4.2.3.5. Social Media Interactions
- 2.4.2.4. Key Opinion Leaders Considered in Primary Research
- 2.4.2.4.1. Company Executives (CXOs)
- 2.4.2.4.2. Board of Directors
- 2.4.2.4.3. Company Presidents and Vice Presidents
- 2.4.2.4.4. Research and Development Heads
- 2.4.2.4.5. Technical Experts
- 2.4.2.4.6. Subject Matter Experts
- 2.4.2.4.7. Scientists
- 2.4.2.4.8. Doctors and Other Healthcare Providers
- 2.4.2.5. Ethics and Integrity
- 2.4.2.5.1. Research Ethics
- 2.4.2.5.2. Data Integrity
- 2.4.2.1. Types of Primary Research
- 2.4.3. Analytical Tools and Databases
- 2.4.1. Secondary Research
- 2.5. Robust Quality Control
3. MARKET DYNAMICS
- 3.1. Chapter Overview
- 3.2. Forecast Methodology
- 3.2.1. Top-down Approach
- 3.2.2. Bottom-up Approach
- 3.2.3. Hybrid Approach
- 3.3. Market Assessment Framework
- 3.3.1. Total Addressable Market (TAM)
- 3.3.2. Serviceable Addressable Market (SAM)
- 3.3.3. Serviceable Obtainable Market (SOM)
- 3.3.4. Currently Acquired Market (CAM)
- 3.4. Forecasting Tools and Techniques
- 3.4.1. Qualitative Forecasting
- 3.4.2. Correlation
- 3.4.3. Regression
- 3.4.4. Extrapolation
- 3.4.5. Convergence
- 3.4.6. Sensitivity Analysis
- 3.4.7. Scenario Planning
- 3.4.8. Data Visualization
- 3.4.9. Time Series Analysis
- 3.4.10. Forecast Error Analysis
- 3.5. Key Considerations
- 3.5.1. Demographics
- 3.5.2. Government Regulations
- 3.5.3. Reimbursement Scenarios
- 3.5.4. Market Access
- 3.5.5. Supply Chain
- 3.5.6. Industry Consolidation
- 3.5.7. Pandemic / Unforeseen Disruptions Impact
- 3.6. Limitations
4. MACRO-ECONOMIC INDICATORS
- 4.1. Chapter Overview
- 4.2. Market Dynamics
- 4.2.1. Time Period
- 4.2.1.1. Historical Trends
- 4.2.1.2. Current and Forecasted Estimates
- 4.2.2. Currency Coverage
- 4.2.2.1. Major Currencies Affecting the Market
- 4.2.2.2. Factors Affecting Currency Fluctuations on the Industry
- 4.2.2.3. Impact of Currency Fluctuations on the Industry
- 4.2.3. Foreign Currency Exchange Rate
- 4.2.3.1. Impact of Foreign Exchange Rate Volatility on the Market
- 4.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 4.2.4. Recession
- 4.2.4.1. Assessment of Current Economic Conditions and Potential Impact on the Market
- 4.2.4.2. Historical Analysis of Past Recessions and Lessons Learnt
- 4.2.5. Inflation
- 4.2.5.1. Measurement and Analysis of Inflationary Pressures in the Economy
- 4.2.5.2. Potential Impact of Inflation on the Market Evolution
- 4.2.6. Interest Rates
- 4.2.6.1. Interest Rates and Their Impact on the Market
- 4.2.6.2. Strategies for Managing Interest Rate Risk
- 4.2.7. Commodity Flow Analysis
- 4.2.7.1. Type of Commodity
- 4.2.7.2. Origins and Destinations
- 4.2.7.3. Values and Weights
- 4.2.7.4. Modes of Transportation
- 4.2.8. Global Trade Dynamics
- 4.2.8.1. Import Scenario
- 4.2.8.2. Export Scenario
- 4.2.8.3. Trade Policies
- 4.2.8.4. Strategies for Mitigating the Risks Associated with Trade Barriers
- 4.2.8.5. Impact of Trade Barriers on the Market
- 4.2.9. War Impact Analysis
- 4.2.9.1. Russian-Ukraine War
- 4.2.9.2. Israel-Hamas War
- 4.2.10. COVID Impact / Related Factors
- 4.2.10.1. Global Economic Impact
- 4.2.10.2. Industry-specific Impact
- 4.2.10.3. Government Response and Stimulus Measures
- 4.2.10.4. Future Outlook and Adaptation Strategies
- 4.2.11. Other Indicators
- 4.2.11.1. Fiscal Policy
- 4.2.11.2. Consumer Spending
- 4.2.11.3. Gross Domestic Product
- 4.2.11.4. Employment
- 4.2.11.5. Taxes
- 4.2.11.6. Stock Market Performance
- 4.2.11.7. Cross Border Dynamics
- 4.2.1. Time Period
- 4.3. Conclusion
5. EXECUTIVE SUMMARY
6. INTRODUCTION
- 6.1. Chapter Overview
- 6.2. Medication Adherence
- 6.2.1. Digital Tools for Improving Medication Adherence
- 6.3. Overview of Connected / Smart Drug Delivery Devices
- 6.4. Key Design Features and Development Process
- 6.5. Classification of Connected / Smart Drug Delivery Devices
- 6.5.1. Type of Device
- 6.5.1.1. Connected Inhalers
- 6.5.1.2. Connected Handheld Injectors
- 6.5.1.3. Smart Pills
- 6.5.1.4. Smart Implantable Devices
- 6.5.2. Type of Technology
- 6.5.1. Type of Device
- 6.6. Regulatory Guidelines for Connected / Smart Drug Delivery Devices
- 6.7. Advantages and Limitations of Connected / Smart Drug Delivery Devices
- 6.8. Impact of COVID-19 on Connected / Smart Drug Delivery Devices Domain
- 6.9. Future Perspective
7. MARKET LANDSCAPE: CONNECTED / SMART DRUG DELIVERY DEVICES
- 7.1. Chapter Overview
- 7.2. Connected / Smart Drug Delivery Devices: Overall Market Landscape
- 7.2.1. Analysis by Stage of Development
- 7.2.2. Analysis by Launch Year
- 7.2.3. Analysis by Type of Integrated Device
- 7.2.4. Analysis by Route of Administration
- 7.2.5. Analysis by Target Indication
- 7.2.6. Analysis by Therapeutic Area
- 7.2.7. Analysis by Key Features
- 7.2.8. Analysis by Mode of Connectivity
- 7.2.9. Analysis by Availability of Companion Mobile Application
- 7.2.10. Analysis by Availability of Data Storage / Cloud Platform
- 7.3. Connected / Smart Drug Delivery Device Manufacturers: Overall Market Landscape
- 7.3.1. Analysis by Year of Establishment
- 7.3.2. Analysis by Company Size
- 7.3.3. Analysis by Location of Headquarters
- 7.3.4. Analysis by Year of Establishment and Location of Headquarters
- 7.3.5. Analysis by Company Size and Location of Headquarters
- 7.3.6. Most Active Players: Analysis by Number of Connected / Smart Drug Delivery Devices Manufactured
8. MARKET LANDSCAPE: ADD-ON SENSORS
- 8.1. Chapter Overview
- 8.2. Add-on Sensors: Overall Market Landscape
- 8.2.1. Analysis by Stage of Development
- 8.2.2. Analysis by Launch Year
- 8.2.3. Analysis by Compatible Device
- 8.2.4. Analysis by Route of Administration
- 8.2.5. Analysis by Target Indication
- 8.2.6. Analysis by Therapeutic Area
- 8.2.7. Analysis by Key Features
- 8.2.8. Analysis by Mode of Connectivity
- 8.2.9. Analysis by Availability of Companion Mobile Application
- 8.2.10. Analysis by Availability of Data Storage / Cloud Platform
- 8.3. Add-on Sensor Manufacturers: Overall Market Landscape
- 8.3.1. Analysis by Year of Establishment
- 8.3.2. Analysis by Company Size
- 8.3.3. Analysis by Location of Headquarters
- 8.3.4. Analysis by Year of Establishment and Location of Headquarters
- 8.3.5. Analysis by Company Size and Location of Headquarters
- 8.3.6. Most Active Players: Analysis by Number of Add-on Sensors Manufactured
9. PRODUCT COMPETITIVENESS ANALYSIS
- 9.1. Chapter Overview
- 9.2. Assumptions and Key Parameters
- 9.3. Methodology
- 9.4. Connected Drug Delivery Devices and Add-on Sensors: Product Competitiveness Analysis
- 9.4.1. Connected / Smart Drug Delivery Devices
- 9.4.1.1. Smart Handheld Injectors (Peer Group 1a)
- 9.4.1.2. Smart Wearable Injectors (Peer Group 1b)
- 9.4.1.3. Other Integrated Devices (Peer Group 1c)
- 9.4.2. Add-on Sensors (Peer Group 2)
- 9.4.1. Connected / Smart Drug Delivery Devices
10. COMPANY PROFILES: CONNECTED / SMART DRUG DELIVERY DEVICE MANUFACTURERS BASED IN NORTH AMERICA
- 10.1. Chapter Overview
- 10.2. Leading Connected / Smart Drug Delivery Device Manufacturers
- 10.2.1. Medtronic
- 10.2.1.1. Company Overview
- 10.2.1.2. Financial Information
- 10.2.1.3. Connected / Smart Drug Delivery Devices Portfolio
- 10.2.1.4. Recent Developments and Future Outlook
- 10.2.2. Insulet
- 10.2.2.1. Company Overview
- 10.2.2.2. Financial Information
- 10.2.2.3. Connected / Smart Drug Delivery Devices Portfolio
- 10.2.2.4. Recent Developments and Future Outlook
- 10.2.3. Tandem Diabetes Care
- 10.2.3.1. Company Overview
- 10.2.3.2. Financial Information
- 10.2.3.3. Connected / Smart Drug Delivery Devices Portfolio
- 10.2.3.4. Recent Developments and Future Outlook
- 10.2.1. Medtronic
- 10.3. Other Prominent Connected / Smart Drug Delivery Device Manufacturers
- 10.3.1. Bigfoot Biomedical
- 10.3.1.1. Company Overview
- 10.3.1.2. Connected / Smart Drug Delivery Devices Portfolio
- 10.3.2. Phillips Medisize (a subsidiary of Molex)
- 10.3.2.1. Company Overview
- 10.3.2.2. Connected / Smart Drug Delivery Devices Portfolio
- 10.3.3. West Pharmaceutical Services
- 10.3.3.1. Company Overview
- 10.3.3.2. Connected / Smart Drug Delivery Devices Portfolio
- 10.3.1. Bigfoot Biomedical
11. COMPANY PROFILES: CONNECTED / SMART DRUG DELIVERY DEVICE MANUFACTURERS BASED IN EUROPE
- 11.1. Chapter Overview
- 11.2. Leading Connected / Smart Drug Delivery Device Manufacturers
- 11.2.1. BIOCORP
- 11.2.1.1. Company Overview
- 11.2.1.2. Financial Information
- 11.2.1.3. Connected / Smart Drug Delivery Devices Portfolio
- 11.2.1.4. Recent Developments and Future Outlook
- 11.2.2. Gerresheimer
- 11.2.2.1. Company Overview
- 11.2.2.2. Financial Information
- 11.2.2.3. Connected / Smart Drug Delivery Devices Portfolio
- 11.2.2.4. Recent Developments and Future Outlook
- 11.2.3. Roche
- 11.2.3.1. Company Overview
- 11.2.3.2. Financial Information
- 11.2.3.3. Connected / Smart Drug Delivery Devices Portfolio
- 11.2.3.4. Recent Developments and Future Outlook
- 11.2.4. Ypsomed
- 11.2.4.1. Company Overview
- 11.2.4.2. Financial Information
- 11.2.4.3. Connected / Smart Drug Delivery Devices Portfolio
- 11.2.4.4. Recent Developments and Future Outlook
- 11.2.1. BIOCORP
- 11.3. Other Prominent Connected / Smart Drug Delivery Device Manufacturers
- 11.3.1. Nemera
- 11.3.1.1. Company Overview
- 11.3.1.2. Connected / Smart Drug Delivery Devices Portfolio
- 11.3.2. Sonceboz
- 11.3.2.1. Company Overview
- 11.3.2.2. Connected / Smart Drug Delivery Devices Portfolio
- 11.3.1. Nemera
12. COMPANY PROFILES: CONNECTED / SMART DRUG DELIVERY DEVICE MANUFACTURERS BASED IN ASIA-PACIFIC AND REST OF THE WORLD
- 12.1. Chapter Overview
- 12.2. Leading Connected / Smart Drug Delivery Device Manufacturers
- 12.2.1. Medtrum
- 12.2.1.1. Company Overview
- 12.2.1.2. Connected / Smart Drug Delivery Devices Portfolio
- 12.2.1.3. Recent Developments and Future Outlook
- 12.2.2. SOOIL Development
- 12.2.2.1. Company Overview
- 12.2.2.2. Connected / Smart Drug Delivery Devices Portfolio
- 12.2.2.3. Recent Developments and Future Outlook
- 12.2.3. EOFlow
- 12.2.3.1. Company Overview
- 12.2.3.2. Financial Information
- 12.2.3.3. Connected / Smart Drug Delivery Devices Portfolio
- 12.2.3.4. Recent Developments and Future Outlook
- 12.2.1. Medtrum
- 12.3. Other Prominent Connected / Smart Drug Delivery Device Manufacturers
- 12.3.1. Eitan Medical
- 12.3.1.1. Company Overview
- 12.3.1.2. Connected / Smart Drug Delivery Devices Portfolio
- 12.3.2. E3D Elcam Drug Delivery Device
- 12.3.2.1. Company Overview
- 12.3.2.2. Connected / Smart Drug Delivery Devices Portfolio
- 12.3.1. Eitan Medical
13. CLINICAL TRIAL ANALYSIS
- 13.1. Chapter Overview
- 13.2. Scope and Methodology
- 13.3. Connected / Smart Drug Delivery Devices and Add-on Sensors: Clinical Trial Analysis
- 13.3.1. Analysis by Trial Registration Year
- 13.3.2. Analysis of Enrolled Patient Population by Trial Registration Year
- 13.3.3. Analysis by Trial Status
- 10.3.4. Analysis by Trial Registration Year and Trial Status
- 13.3.5. Analysis of Number of Enrolled Patients Population by Trial Status
- 13.3.6. Analysis by Target Patient Population
- 13.3.7. Analysis by Type of Sponsor / Collaborator
- 13.3.8. Analysis by Study Design
- 10.3.8.1. Analysis by Type of Allocation
- 10.3.8.2. Analysis by Type of Intervention Model
- 10.3.8.3. Analysis by Type of Masking
- 10.3.8.4. Analysis by Trial Purpose
- 13.3.9. Leading Players: Analysis by Number of Registered Trials
- 13.3.10. Leading Connected / Smart Drug Delivery Devices and Add-on Sensors: Analysis by Number of Registered Trials
- 13.3.11. Analysis by Geography
- 13.3.11.1. Analysis of Clinical Trials by Geography
- 13.3.11.2. Analysis of Number of Registered Trials by Trial Status and Geography
- 13.3.11.3. Analysis of Number of Enrolled Patient Population by Geography
14. PARTNERSHIPS AND COLLABORATIONS
- 14.1. Chapter Overview
- 14.2. Partnership Models
- 14.3. Connected / Smart Drug Delivery Devices: Partnerships and Collaborations
- 14.3.1. Analysis by Year of Partnership
- 14.3.2. Analysis by Type of Partnership
- 14.3.3. Analysis by Year and Type of Partnership
- 14.3.4. Analysis by Class of Device
- 14.3.5. Analysis by Type of Integrated Device
- 14.3.6. Most Active Players: Analysis by Number of Partnerships
- 14.3.7. Analysis by Geography
- 14.3.7.1. Intracontinental and Intercontinental Deals
- 14.3.7.2. Local and International Deals
15. FUNDING AND INVESTMENT ANALYSIS
- 15.1. Chapter Overview
- 15.2. Funding Models
- 15.3. Connected / Smart Drug Delivery Devices: Funding and Investments
- 15.3.1. Analysis by Year of Funding
- 15.3.2. Analysis by Type of Funding
- 15.3.3. Analysis by Year and Type of Funding
- 15.3.4. Analysis of Amount Invested by Year of Funding
- 15.3.5. Analysis of Amount Invested by Type of Funding
- 15.3.6. Analysis by Geography
- 15.3.7. Most Active Players: Analysis by Number of Funding Instances
- 15.3.8. Most Active Players: Analysis by Amount Raised
16. VALUE CHAIN ANALYSIS
- 16.1. Chapter Overview
- 16.2. Connected / Smart Drug Delivery Devices: Value Chain
- 16.3. Cost Distribution across the Value Chain
- 16.3.1. Concept Development and Proof of Concept
- 16.3.2. Research and Product Development
- 16.3.3. Conduct of Clinical Trials
- 16.3.4. Regulatory Approvals
- 16.3.5. Manufacturing and Product Assembly
- 16.3.6. Application Development
- 16.3.7. Marketing and Sales
17. REGULATORY LANDSCAPE FOR CONNECTED / SMART DRUG DELIVERY DEVICES
- 17.1. Chapter Overview
- 17.2. Regulatory Approval of Combination Products in North America
- 17.2.1. Regulatory Approval of Combination Products in the US
- 17.2.1.1. Overview
- 17.2.1.2. Historical Background
- 17.2.1.3. Role of Regulatory Bodies in Product Approval
- 17.2.2. Regulatory Approval of Combination Products in Canada
- 17.2.2.1. Overview
- 17.2.2.2. Role of Regulatory Bodies in Product Approval
- 17.2.3. Regulatory Approval of Combination Products in Mexico
- 17.2.3.1. Overview
- 17.2.3.2. Role of Regulatory Bodies in Product Approval
- 17.2.1. Regulatory Approval of Combination Products in the US
- 17.3. Regulatory Approval of Combination Products in Europe
- 17.3.1. Regulatory Approval of Combination Products in EU5 Countries
- 17.3.1.1. Overview
- 17.3.1.2. Role of Regulatory Bodies in Product Approval
- 17.3.1. Regulatory Approval of Combination Products in EU5 Countries
- 17.4. Regulatory Approval of Combination Products in Asia-Pacific
- 17.4.1. Regulatory Approval of Combination Products in Japan
- 17.4.1.1. Overview
- 17.4.1.2. Role of Regulatory Bodies in Product Approval
- 17.4.2. Regulatory Approval of Combination Products in China
- 17.4.2.1. Overview
- 17.4.2.2. Role of Regulatory Bodies in Product Approval
- 17.4.3. Regulatory Approval of Combination Products in India
- 17.4.3.1. Overview
- 17.4.3.2. Role of Regulatory Bodies in Product Approval
- 17.4.4. Regulatory Approval of Combination Products in South Korea
- 17.4.4.1. Overview
- 17.4.4.2. Role of Regulatory Bodies in Product Approval
- 17.4.5. Regulatory Approval of Combination Products in Australia
- 17.4.5.1. Overview
- 17.4.5.2. Role of Regulatory Bodies in Product Approval
- 17.4.1. Regulatory Approval of Combination Products in Japan
- 17.5. Regulatory Approval of Combination Products in Middle East and North Africa
- 17.5.1. Regulatory Approval of Combination Products in Saudi Arabia
- 17.5.1.1. Overview
- 17.5.1.2. Role of Regulatory Bodies in Product Approval
- 17.5.2. Regulatory Approval of Combination Products in United Arab Emirates
- 17.5.2.1. Overview
- 17.5.2.2. Role of Regulatory Bodies in Product Approval
- 17.5.1. Regulatory Approval of Combination Products in Saudi Arabia
- 17.6. Regulatory Approval of Combination Products in Latin America
- 17.6.1. Regulatory Approval of Combination Products in Brazil
- 17.6.1.1. Overview
- 17.6.1.2. Role of Regulatory Bodies in Product Approval
- 17.6.2. Regulatory Approval of Combination Products in Argentina
- 17.6.2.1. Overview
- 17.6.2.2. Role of Regulatory Bodies in Product Approval
- 17.6.1. Regulatory Approval of Combination Products in Brazil
- 17.7. Connected Devices: Other Measures for Testing Safety, Effectiveness and Performance
- 17.8. Ensuring Security of Data Captured
- 17.9. Concluding Remarks
18. CASE STUDIES: APPLICATION OF CONNECTED DRUG DELIVERY DEVICES TO IMPROVE MEDICATION ADHERENCE
- 18.1. Chapter Overview
- 18.2. Case Study I: Diabetes
- 18.2.1. Disease Overview
- 18.2.2. Key Statistics
- 18.2.3. Economic Burden due to Non-Adherence
- 18.2.4. Evolution of Connected / Smart Drug Delivery Devices for Improving Adherence
- 18.3. Case Study II: Asthma
- 18.3.1. Disease Overview
- 18.3.2. Key Statistics
- 18.3.3. Economic Burden due to Non-Adherence
- 18.3.4. Evolution of Connected / Smart Drug Delivery Devices for Improving Adherence
19. SWOT ANALYSIS
- 19.1. Chapter Overview
- 19.2. Strengths
- 19.2.1. Ability to Minimize / Eliminate Medication Errors
- 19.2.2. Economic Advantages
- 19.2.3. Technological Advancements
- 19.3. Weaknesses
- 19.3.1. Cybersecurity
- 19.3.2. Stringent Regulatory Approvals
- 19.3.3. High Developmental Costs
- 19.4. Opportunities
- 19.4.1. Growing Prevalence of Chronic Disorders
- 19.4.2. Increasing Adoption of Digital Health Technologies
- 19.4.3. Rising Partnership and Investment Activity
- 19.5. Threats
- 19.5.1. Material Compatibility Issues
- 19.5.2. Availability of Alternative Drug Delivery Devices
- 19.5.3. Concern Related to Product Recalls in Past
- 19.6. Comparison of SWOT Factors
20. BLUE OCEAN STRATEGY
- 20.1. Overview of Blue Ocean Strategy
- 20.1.1. Red Oceans
- 20.1.2. Blue Oceans
- 20.1.3. Comparison of Red Ocean Strategy and Blue Ocean Strategy
- 20.1.4. Connected Drug Delivery Devices: Blue Ocean Strategy and Shift Tools
- 20.1.4.1. Strategy Canvas
- 20.1.4.2. Pioneer-Migrator-Settler (PMS) Map
21. GLOBAL CONNECTED DRUG DELIVERY DEVICES MARKET
- 21.1. Chapter Overview
- 21.2. Assumptions and Methodology
- 21.3. Global Connected Drug Delivery Devices Market: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 21.3.1. Scenario Analysis
- 21.3.1.1. Conservative Scenario
- 21.3.1.2. Optimistic Scenario
- 21.3.1. Scenario Analysis
- 21.4. Key Market Segmentations
22. CONNECTED DRUG DELIVERY DEVICES MARKET, BY TYPE OF DEVICE
- 22.1. Chapter Overview
- 22.2. Assumptions and Methodology
- 22.3. Connected Drug Delivery Devices Market: Distribution by Type of Device
- 22.3.1. Connected Drug Delivery Devices Market for Connected / Smart Wearable Injectors: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 22.3.2. Connected Drug Delivery Devices Market for Connected / Smart Inhalers: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 22.3.3. Connected Drug Delivery Devices Market for Connected / Smart Pen Injectors: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 22.3.4. Connected Drug Delivery Devices Market for Connected / Smart Autoinjectors: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 22.3.5. Connected Drug Delivery Devices Market for Connected / Smart Needle-free Injection Systems: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 22.4. Data Triangulation and Validation
23. CONNECTED DRUG DELIVERY DEVICES MARKET, BY MODE OF CONNECTIVITY
- 23.1. Chapter Overview
- 23.2. Assumptions and Methodology
- 23.3. Connected Drug Delivery Devices Market: Distribution by Mode of Connectivity
- 23.3.1. Connected Drug Delivery Devices Market for Bluetooth-enabled Devices: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 23.3.2. Connected Drug Delivery Devices Market for Near-field Communication-enabled Devices: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 23.3.3. Connected Drug Delivery Devices Market for Cellular-enabled Devices: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 23.3.4. Connected Drug Delivery Devices Market for Wide Area Network-enabled Devices: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 23.4. Data Triangulation and Validation
24. CONNECTED DRUG DELIVERY DEVICES MARKET, BY ROUTE OF ADMINISTRATION
- 24.1. Chapter Overview
- 24.2. Assumptions and Methodology
- 24.3. Connected Drug Delivery Devices Market: Distribution by Route of Administration
- 24.3.1. Connected Drug Delivery Devices Market for Parenteral Administration: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 24.3.2. Connected Drug Delivery Devices Market for Inhalational Administration: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 24.4. Data Triangulation and Validation
25. CONNECTED DRUG DELIVERY DEVICES MARKET, BY THERAPEUTIC AREA
- 25.1. Chapter Overview
- 25.2. Assumptions and Methodology
- 25.3. Connected Drug Delivery Devices Market: Distribution by Therapeutic Area
- 25.3.1. Connected Drug Delivery Devices Market for Metabolic Disorders: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 25.3.2. Connected Drug Delivery Devices Market for Respiratory Disorders: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 25.3.3. Connected Drug Delivery Devices Market for Autoimmune Disorders: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 25.3.4. Connected Drug Delivery Devices Market for Other Disorders: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 25.4. Data Triangulation and Validation
26. CONNECTED DRUG DELIVERY DEVICES MARKET, BY GEOGRAPHICAL REGIONS
- 26.1. Chapter Overview
- 26.2. Assumptions and Methodology
- 26.3. Connected Drug Delivery Devices Market: Distribution by Geographical Regions
- 26.3.1. Connected Drug Delivery Devices Market in North America: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.1.1. Connected Drug Delivery Devices Market in the US: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.1.2. Connected Drug Delivery Devices Market in Canada: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.2. Connected Drug Delivery Devices Market in Europe: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.2.1. Connected Drug Delivery Devices Market in the UK: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.2.2. Connected Drug Delivery Devices Market in Germany: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.2.3. Connected Drug Delivery Devices Market in France: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.2.4. Connected Drug Delivery Devices Market in Italy: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.2.5. Connected Drug Delivery Devices Market in Spain: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.2.6. Connected Drug Delivery Devices Market in Rest of Europe: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.3. Connected Drug Delivery Devices Market in Asia-Pacific: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.3.1. Connected Drug Delivery Devices Market in China: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.3.2. Connected Drug Delivery Devices Market in India: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.3.3. Connected Drug Delivery Devices Market in Japan: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.3.4. Connected Drug Delivery Devices Market in Rest of Asia-Pacific: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.4. Connected Drug Delivery Devices Market in Middle East and North Africa: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.4.1. Connected Drug Delivery Devices Market in Egypt: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.4.2. Connected Drug Delivery Devices Market in Israel: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.4.3. Connected Drug Delivery Devices Market in Saudi Arabia: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.4.4. Connected Drug Delivery Devices Market in Rest of Middle East and North Africa: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.5. Connected Drug Delivery Devices Market in Latin America and Rest of the World: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.5.1. Connected Drug Delivery Devices Market in Brazil: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.5.2. Connected Drug Delivery Devices Market in Argentina: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.5.3. Connected Drug Delivery Devices Market in Other Countries: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.3.1. Connected Drug Delivery Devices Market in North America: Historical Trends (since 2020) and Forecasted Estimates (till 2035)
- 26.4. Data Triangulation and Validation
27. CONNECTED DRUG DELIVERY DEVICES MARKET, BY LEADING PLAYERS
28. CONCLUDING REMARKS
29. EXECUTIVE INSIGHTS
30. APPENDIX 1: TABULATED DATA
31. APPENDIX 2: LIST OF COMPANIES AND ORGANIZATIONS
32. APPENDIX 3: PARTNERSHIPS AND COLLABORATIONS, 2015-2020
List of Figures
- Figure 2.1 Research Methodology: Project Methodology
- Figure 2.2 Research Methodology: Data Sources for Secondary Research
- Figure 3.1 Market Dynamics: Forecast Methodology
- Figure 3.2 Market Dynamics: Key Market Segmentation
- Figure 3.3 Market Dynamics: Robust Quality Control
- Figure 4.1 Lessons Learnt from Past Recessions
- Figure 5.1 Executive Summary: Connected / Smart Drug Delivery Devices Market Landscape
- Figure 5.2 Executive Summary: Add-on Sensors Market Landscape
- Figure 5.3 Executive Summary: Market Trends
- Figure 5.4 Executive Summary: Market Forecast and Opportunity Analysis
- Figure 6.1 Different Components of IoT Ecosystem
- Figure 6.2 Framework of Connected / Smart Drug Delivery Devices
- Figure 6.3 Key Considerations for Designing and Developing a Connected / Smart Drug Delivery Device
- Figure 6.4 Stack Model for the Development of Connected Drug Delivery Devices
- Figure 6.5 Type of Technology Used for Connected / Smart Drug Delivery Device
- Figure 6.6 Advantages of Connected / Smart Drug Delivery Devices
- Figure 7.1 Connected / Smart Drug Delivery Devices: Distribution by Stage of Development
- Figure 7.2 Connected / Smart Drug Delivery Devices: Distribution by Launch Year
- Figure 7.3 Connected / Smart Drug Delivery Devices: Distribution by Type of Integrated Device
- Figure 7.4 Connected / Smart Drug Delivery Devices: Distribution by Route of Administration
- Figure 7.5 Connected / Smart Drug Delivery Devices: Distribution by Target Indication
- Figure 7.6 Connected / Smart Drug Delivery Devices: Distribution by Therapeutic Area
- Figure 7.7 Connected / Smart Drug Delivery Devices: Distribution by Key Features
- Figure 7.8 Connected / Smart Drug Delivery Devices: Distribution by Mode of Connectivity
- Figure 7.9 Connected / Smart Drug Delivery Devices: Distribution by Availability of Companion Mobile Application
- Figure 7.10 Connected / Smart Drug Delivery Devices: Distribution by Availability of Data Storage / Cloud Platform
- Figure 7.11 Connected / Smart Drug Delivery Device Manufacturers: Distribution by Year of Establishment
- Figure 7.12 Connected / Smart Drug Delivery Device Manufacturers: Distribution by Company Size
- Figure 7.13 Connected / Smart Drug Delivery Device Manufacturers: Distribution by Location of Headquarters
- Figure 7.14 Connected / Smart Drug Delivery Device Manufacturers: Distribution by Year of Establishment and Location of Headquarters
- Figure 7.15 Connected / Smart Drug Delivery Device Manufacturers: Distribution by Company Size and Location of Headquarters
- Figure 7.16 Most Active Players: Distribution by Number of Connected / Smart Drug Delivery Devices Manufactured
- Figure 8.1 Add-on Sensors: Distribution by Stage of Development
- Figure 8.2 Add-on Sensors: Distribution by Launch Year
- Figure 8.3 Add-on Sensors: Distribution by Compatible Device
- Figure 8.4 Add-on Sensors: Distribution by Route of Administration
- Figure 8.5 Add-on Sensors: Distribution by Target Indication
- Figure 8.6 Add-on Sensors: Distribution by Therapeutic Area
- Figure 8.7 Add-on Sensors: Distribution by Key Features
- Figure 8.8 Add-on Sensors: Distribution by Mode of Connectivity
- Figure 8.9 Add-on Sensors: Distribution by Availability of Companion Mobile Application
- Figure 8.10 Add-on Sensors: Distribution by Availability of Data Storage / Cloud Platform
- Figure 8.11 Add-on Sensor Manufacturers: Distribution by Year of Establishment
- Figure 8.12 Add-on Sensor Manufacturers: Distribution by Company Size
- Figure 8.13 Add-on Sensor Manufacturers: Distribution by Location of Headquarters
- Figure 8.14 Add-on Sensor Manufacturers: Distribution by Year of Establishment and Location of Headquarters
- Figure 8.15 Add-on Sensor Manufacturers: Distribution by Company Size and Location of Headquarters
- Figure 8.16 Most Active Players: Distribution by Number of Add-on Sensors Manufactured
- Figure 9.1 Product Competitiveness Analysis: Smart Handheld Injectors (Peer Group 1a)
- Figure 9.2 Product Competitiveness Analysis: Smart Wearable Injectors (Peer Group 1b)
- Figure 9.3 Product Competitiveness Analysis: Other Integrated Devices (Peer Group 1c)
- Figure 9.4 Product Competitiveness Analysis: Add-on Sensors (Peer Group 2)
- Figure 10.1 Medtronic: Business Segment-wise Revenues and Consolidated Financial Details (USD Billion)
- Figure 10.2 Insulet: Business Segment-wise Revenues and Consolidated Financial Details (USD Millon)
- Figure 10.3 Tandem Diabetes Care: Consolidated Financial Details (USD Million)
- Figure 11.1 Gerresheimer: Business Segment-wise Revenues and Consolidated Financial Details (EUR Million)
- Figure 11.2 Roche: Business Segment-wise Revenues and Consolidated Financial Details (CHF Billion)
- Figure 11.3 Ypsomed: Business Segment-wise Revenues and Consolidated Financial Details (CHF Million)
- Figure 13.1 Clinical Trial Analysis: Cumulative Year-wise Trend, since 2021
- Figure 13.2 Clinical Trial Analysis: Year-wise Trend of Enrolled Patient Population by Trial Registration Year, since 2021
- Figure 13.3 Clinical Trial Analysis: Distribution by Trial Status
- Figure 13.4 Clinical Trial Analysis: Distribution by Trial Registration Year and Trial Status
- Figure 13.5 Clinical Trial Analysis: Distribution of Number of Enrolled Patient Population by Trial Status
- Figure 13.6 Clinical Trial Analysis: Distribution by Target Patient Population
- Figure 13.7 Clinical Trial Analysis: Distribution by Type of Sponsor / Collaborator
- Figure 13.8 Clinical Trial Analysis: Distribution by Study Design
- Figure 13.9 Clinical Trial Analysis: Distribution by Type of Allocation
- Figure 13.10 Clinical Trial Analysis: Distribution by Type of Intervention Model
- Figure 13.11 Clinical Trial Analysis: Distribution by Type of Masking
- Figure 13.12 Clinical Trial Analysis: Distribution by Trial Purpose
- Figure 13.13 Leading Players: Distribution by Number of Registered Trials
- Figure 13.14 Leading Connected / Smart Drug Delivery Devices and Add-On Sensors: Distribution by Number of Registered Trials
- Figure 13.15 Clinical Trial Analysis: Distribution of Clinical Trials by Geography
- Figure 13.16 Clinical Trial Analysis: Distribution of Number of Registered Trials by Trial Status and Geography
- Figure 13.17 Clinical Trial Analysis: Distribution of Number of Enrolled Patients Population by Geography
- Figure 14.1 Partnerships and Collaborations: Cumulative Year-wise Trend, since 2021
- Figure 14.2 Partnerships and Collaborations: Distribution by Type of Partnership
- Figure 14.3 Partnerships and Collaborations: Distribution by Year and Type of Partnership, since 2021
- Figure 14.4 Partnerships and Collaborations: Distribution by Class of Device
- Figure 14.5 Partnerships and Collaborations: Distribution by Type of Integrated Device
- Figure 14.6 Partnerships and Collaborations: Distribution by Compatible Device
- Figure 14.7 Most Active Players: Distribution by Number of Partnerships
- Figure 14.8 Partnerships and Collaborations: Intracontinental and Intercontinental Deals
- Figure 14.9 Partnerships and Collaborations: Local and International Deals
- Figure 15.1 Funding and Investments: Cumulative Year-wise Trend, since 2021
- Figure 15.2 Funding and Investments: Distribution by Amount Invested, since 2021 (USD Million)
- Figure 15.3 Funding and Investments: Distribution of Funding Instances by Type of Funding
- Figure 15.4 Funding and Investments: Distribution of Amount Invested by Type of Funding (USD Million)
- Figure 15.5 Funding and Investments: Distribution of Funding Instances by Year and Type of Funding, since 2021
- Figure 15.6 Funding and Investments: Distribution of Funding Instances by Geography
- Figure 15.7 Most Active Players: Distribution by Number of Funding Instances
- Figure 15.8 Most Active Players: Distribution by Amount Raised (USD Million)
- Figure 15.9 Summary of Funding and Investments, since 2021 (USD Million)
- Figure 16.1 Connected / Smart Drug Delivery Devices: Value Chain
- Figure 16.2 Cost Distribution Across Value Chain
- Figure 16.3 Costs Associated with Concept Development and Proof of Concept
- Figure 16.4 Costs Associated with Research and Product Development
- Figure 16.5 Costs Associated with Clinical Trials
- Figure 16.6 Costs Associated with Regulatory Approvals
- Figure 16.7 Costs Associated with Manufacturing and Product Assembly
- Figure 16.8 Costs Associated with Application Development
- Figure 16.9 Costs Associated with Marketing and Sales
- Figure 17.1 Global Regulations related to Smart Inhalers, Smart Injectors and Smart Wearable Injectors
- Figure 17.2 USFDA: Approval Pathway for Combination Products
- Figure 17.3 Health Canada: Approval Pathway for Combination Products
- Figure 17.4 NMPA: Approval Pathway for Combination Products
- Figure 17.5 Connected / Smart Drug Delivery Devices: Major Steps for Managing Privacy
- Figure 18.1 Diabetes: Evolution of Drug Delivery / Connected Devices
- Figure 18.2 Impact of Drug Delivery / Connected Devices in Improving Drug Adherence in Diabetic Patients: Highlights on Twitter
- Figure 18.3 Asthma: Evolution of Drug Delivery / Connected Devices
- Figure 18.4 Impact of Drug Delivery / Connected Devices in Improving Drug Adherence in Asthmatic Patients: Highlights on Twitter
- Figure 19.1 Connected Drug Delivery Devices Market: SWOT Analysis
- Figure 19.2 Comparison of SWOT Factors: Harvey Ball Analysis
- Figure 20.1 Blue Ocean Strategy: Strategy Canvas
- Figure 20.2 Blue Ocean Strategy: Pioneer-Migrator (PMS) Map
- Figure 21.1 Global Connected Drug Delivery Devices Market: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 21.2 Global Connected Drug Delivery Devices Market, till 2035: Conservative Scenario (Million Units Sold, USD Million)
- Figure 21.3 Global Connected Drug Delivery Devices Market, till 2035: Optimistic Scenario (Million Units Sold, USD Million)
- Figure 22.1 Connected Drug Delivery Devices Market: Distribution by Type of Device (USD Million)
- Figure 22.2 Connected Drug Delivery Devices Market for Connected / Smart Wearable Injectors: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 22.3 Connected Drug Delivery Devices Market for Connected / Smart Inhalers: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 22.4 Connected Drug Delivery Devices Market for Connected / Smart Pen Injectors: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 22.5 Connected Drug Delivery Devices Market for Connected / Smart Autoinjectors: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million, Million Units Sold)
- Figure 22.6 Connected Drug Delivery Devices Market for Connected / Smart Needle-free Injection Systems: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million, Million Units Sold)
- Figure 23.1 Connected Drug Delivery Devices Market: Distribution by Mode of Connectivity (USD Million)
- Figure 23.2 Connected Drug Delivery Devices Market for Bluetooth-enabled Devices: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 23.3 Connected Drug Delivery Devices Market for Near-field Communication-enabled Devices: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 23.4 Connected Drug Delivery Devices Market for Cellular-enabled Devices: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 23.5 Connected Drug Delivery Devices Market for Wide Area Network-enabled Devices: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 24.1 Connected Drug Delivery Devices Market: Distribution by Route of Administration (USD Million)
- Figure 24.2 Connected Drug Delivery Devices Market for Parenteral Administration: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 24.3 Connected Drug Delivery Devices Market for Inhalational Administration: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 25.1 Connected Drug Delivery Devices Market: Distribution by Therapeutic Area (USD Million)
- Figure 25.2 Connected Drug Delivery Devices Market for Metabolic Disorders: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 25.3 Connected Drug Delivery Devices Market for Respiratory Disorders: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 25.4 Connected Drug Delivery Devices Market for Autoimmune Disorders: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 25.5 Connected Drug Delivery Devices Market for Other Disorders: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 26.1 Connected Drug Delivery Devices Market: Distribution by Geographical Regions (USD Million)
- Figure 26.2 Connected Drug Delivery Devices Market in North America: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 26.3 Connected Drug Delivery Devices Market in the US: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.4 Connected Drug Delivery Devices Market in Canada: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.5 Connected Drug Delivery Devices Market in Europe: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 26.6 Connected Drug Delivery Devices Market in the UK: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.7 Connected Drug Delivery Devices Market in Germany: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.8 Connected Drug Delivery Devices Market in France: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.9 Connected Drug Delivery Devices Market in Italy: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.10 Connected Drug Delivery Devices Market in Spain: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.11 Connected Drug Delivery Devices Market in Rest of Europe: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.12 Connected Drug Delivery Devices Market in Asia-Pacific: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 26.13 Connected Drug Delivery Devices Market in China: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.14 Connected Drug Delivery Devices Market in India: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.15 Connected Drug Delivery Devices Market in Japan: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.16 Connected Drug Delivery Devices Market in Rest of Asia-Pacific: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.17 Connected Drug Delivery Devices Market in Middle East and North Africa: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 26.18 Connected Drug Delivery Devices Market in Egypt: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.19 Connected Drug Delivery Devices Market in Israel: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.20 Connected Drug Delivery Devices Market in Saudi Arabia: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.21 Connected Drug Delivery Devices Market in Rest of Middle East and North Africa: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.22 Connected Drug Delivery Devices Market in Latin America and Rest of the World: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (Million Units Sold, USD Million)
- Figure 26.23 Connected Drug Delivery Devices Market in Brazil: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.24 Connected Drug Delivery Devices Market in Argentina: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 26.25 Connected Drug Delivery Devices Market in Other Countries: Historical Trends (since 2020) and Forecasted Estimates (till 2035) (USD Million)
- Figure 27.1 Concluding Remarks: Connected Drug Delivery Devices Market Landscape
- Figure 27.2 Concluding Remarks: Add-on-Sensors Market Landscape
- Figure 27.3 Concluding Remarks: Partnerships and Collaborations
- Figure 27.4 Concluding Remarks: Funding and Investments
- Figure 27.5 Concluding Remarks: Market Sizing and Opportunity Analysis

