PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2109197
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2109197
Wind Turbine Tower Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
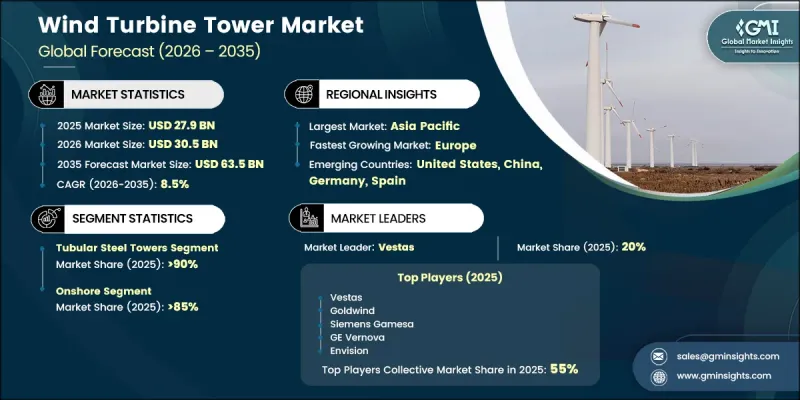
The Global Wind Turbine Tower Market was valued at USD 27.9 billion in 2025 and is estimated to grow at a CAGR of 8.5% to reach USD 63.5 billion by 2035.
The industry outlook remains positive as national renewable energy goals and global decarbonization commitments encourage significant growth in wind power installations. The market is experiencing a shift toward two major demand trends: cost-efficient standardized tower solutions for established onshore projects and advanced engineering designs for offshore wind farms and taller hub-height applications. Increasing tower heights, particularly designs ranging from 120-160 meters and beyond, are gaining attention as higher elevations provide improved wind speeds and greater energy output, especially in regions with lower wind availability. IRENA data shows that raising hub height from 80 meters to 120 meters can increase capacity factors by 5-12 percentage points in low-wind-speed locations, contributing to better energy generation efficiency and lower levelized cost of energy.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $27.9 Billion |
| Forecast Value | $63.5 Billion |
| CAGR | 8.5% |
Tubular steel towers continue to dominate the wind turbine tower market, representing more than 90% of the classified tower segment by value. This strong market position is supported by established manufacturing processes, reliable structural steel supply networks, and extensive experience with cylindrical tower designs under long-term operational stress conditions. Leading wind turbine manufacturers continue to rely heavily on tubular steel tower solutions because of their proven performance, scalability, and compatibility with modern turbine systems.
The onshore wind projects segment held 85% share in 2025. GWEC data indicates that onshore wind accounted for more than 93% of total cumulative global wind capacity at the end of 2024, highlighting the segment's advanced infrastructure base and cost-efficient manufacturing ecosystem. Within the onshore category, increasing hub heights remain a key factor influencing tower value growth. Wind projects in several developing and established markets are adopting taller tower structures, including 120-140 meter designs, which are increasing tower material requirements and creating additional revenue opportunities for manufacturers.
North America Wind Turbine Tower Market generated a significant share in 2025, supported by strong renewable energy investment activity in the United States, which ranks among the largest wind power markets globally by installed capacity. In response to increasing demand for domestically manufactured components, CS Wind's facility in Windsor, Colorado, which produces approximately 500-600 tower sets annually, has expanded its operations to support demand linked to domestic content incentives. The facility supplies major wind energy developers, including NextEra Energy and Berkshire Hathaway Energy.
Key companies operating in the wind turbine tower market include Goldwind, Vestas, CS Wind, Siemens Gamesa, Windar Renovables, GE Vernova, Envision, Enercon, and Nordex. Companies in the wind turbine tower market are adopting strategies such as expanding manufacturing facilities, increasing production capabilities, and establishing regional supply networks to serve growing wind energy demand. Market leaders are investing in lightweight materials, advanced fabrication technologies, and automated manufacturing processes to improve efficiency and reduce production costs. Strategic collaborations with turbine manufacturers and project developers help companies secure long-term contracts and strengthen customer relationships. Businesses are also focusing on developing taller tower solutions, improving logistics capabilities, and enhancing operational sustainability. Expansion into emerging wind markets, adoption of digital technologies, and continuous investment in research and development remain key approaches used by companies to strengthen their market presence and maintain a competitive advantage.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research design
- 1.2 Quality commitment
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research trail components
- 1.3.2 Scoring components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
- 1.9 Market definitions
Chapter 2 Executive Summary
- 2.1 Industry 360-degree synopsis, 2022 – 2035
- 2.2 Business trends
- 2.3 Tower type trends
- 2.4 Deployment trends
- 2.5 Tower height trends
- 2.6 End use trends
- 2.7 Regional trends
Chapter 3 Industry Insights
- 3.1 Industry ecosystem
- 3.2 Regulatory landscape
- 3.3 Industry impact forces
- 3.3.1 Growth drivers
- 3.3.2 Industry pitfalls & challenges
- 3.4 Growth potential analysis
- 3.5 Technology & Innovation Landscape
- 3.6 Price trend analysis
- 3.6.1 Historic price trend analysis by tower type
- 3.6.2 Pricing strategy by player type
- 3.7 Porter's analysis
- 3.7.1 Bargaining power of suppliers
- 3.7.2 Bargaining power of buyers
- 3.7.3 Threat of new entrants
- 3.7.4 Threat of substitutes
- 3.8 PESTEL analysis
- 3.8.1 Political factors
- 3.8.2 Economic factors
- 3.8.3 Social factors
- 3.8.4 Technological factors
- 3.8.5 Legal factors
- 3.8.6 Environmental factors
- 3.9 Emerging opportunities & trends
- 3.10 Digitalization & IoT integration
- 3.11 Investment analysis and future outlook
Chapter 4 Competitive landscape, 2026
- 4.1 Introduction
- 4.2 Company market share analysis, by region, 2025
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Middle East & Africa
- 4.2.5 Latin America
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans & funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Size and Forecast, By Tower Type, 2022 – 2035 (USD Billion)
- 5.1 Key trends
- 5.2 Tubular Steel
- 5.3 Concrete
- 5.4 Hybrid Steel-Concrete
- 5.5 Lattice
- 5.6 Others
Chapter 6 Market Size and Forecast, By Deployment, 2022 – 2035 (USD Billion)
- 6.1 Key trends
- 6.2 Onshore
- 6.3 Offshore
Chapter 7 Market Size and Forecast, By Tower Height, 2022 – 2035 (USD Billion)
- 7.1 Key trends
- 7.2 ≤80 m
- 7.3 81-120 m
- 7.4 121-160 m
- 7.5 >160 m
Chapter 8 Market Size and Forecast, By End Use, 2022 – 2035 (USD Billion)
- 8.1 Key trends
- 8.2 Residential
- 8.3 Commercial
- 8.4 Utility
Chapter 9 Market Size and Forecast, By Region, 2022 – 2035 (USD Billion)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.2.3 Mexico
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 Spain
- 9.3.3 UK
- 9.3.4 France
- 9.3.5 Italy
- 9.3.6 Sweden
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 Japan
- 9.4.3 South Korea
- 9.4.4 India
- 9.4.5 Australia
- 9.5 Middle East & Africa
- 9.5.1 South Africa
- 9.5.2 Egypt
- 9.6 Latin America
- 9.6.1 Brazil
- 9.6.2 Chile
- 9.6.3 Argentina
Chapter 10 Company Profiles
- 10.1 Anyang Machinery
- 10.2 Arcosa Wind Towers
- 10.3 Bergey Windpower
- 10.4 Broadwind
- 10.5 CS Wind Corporation
- 10.6 Cubuilt Engineers
- 10.7 Dongkuk
- 10.8 Enel Green Power
- 10.9 ENERCON
- 10.10 Faccin
- 10.11 GE Vernova
- 10.12 GRI Renewable Industries
- 10.13 Hitachi
- 10.14 KGW Schweriner Maschinen- und Anlagenbau GmbH
- 10.15 Nordex
- 10.16 Qingdao Aeolos Wind Power
- 10.17 ReGen Powertech Private Limited
- 10.18 Siemens Gamesa Renewable Energy
- 10.19 Vestas Wind Systems
- 10.20 XEMC Windpower

