PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113488

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113488
Wind Turbine Tower - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the wind turbine tower market size is expected to grow from USD 33.20 billion in 2025 to USD 37.02 billion in 2026 and is forecast to reach USD 63.9 billion by 2031 at 11.52% CAGR over 2026-2031.
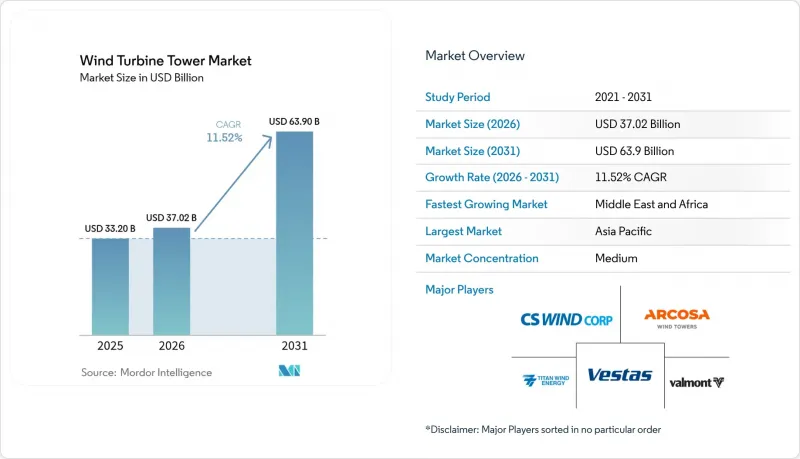
This report is Segmented by Tower Type (Tubular Steel, Concrete, Hybrid Steel-Concrete, Lattice, Guyed Pole, and Modular/Stacked Composite), Deployment (Onshore, Offshore-Fixed-Bottom, and Offshore-Floating), Tower Height (Up To 80 M, 81-120 M, 121-160 M, and Above 160 M), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa).
Global Wind Turbine Tower Market Trends and Insights
IRA-driven localization of Over 100 m steel tower capacity in the United States
Domestic-content rules embedded in the IRA have triggered USD 2 billion of tower factory announcements across the Midwest, drawing global leaders such as CS Wind and Arcosa into dual-shore production strategies that balance U.S. demand with Asian cost bases.New plants are engineered for >120 m sections, eliminating historical import dependence and raising regional competence for ultra-tall designs. Order inflows at Broadwind surged 85% in Q4 2024, demonstrating that localized supply now achieves competitive scale.
Permitting reforms enabling >160 m towers in Germany & the Nordics
Berlin's 2024 "Onshore Wind Law" cut approval timelines by 40%, unleashing a queue of extreme-height projects, including the 364 m Lusatia installation now operational. Coordinated Nordic height caps allow developers to tap steadier high-altitude winds, compelling OEMs to refine load-management software and noise envelopes on next-generation turbines.
Seaborne logistics bottlenecks for >15 m-diameter tower sections on the U.S. East Coast
Jones Act rules limit foreign vessels, creating a scarcity of heavy-lift ships needed for XXL-diameter sections. Port staging yards and crane upgrades lag demand, forcing modular at-sea assembly or floating foundation workarounds that add cost and time.
Other drivers and restraints analyzed in the detailed report include:
- Hybrid steel-concrete towers cutting LCoE for low-wind inland sites in India & China
- EU carbon border adjustment accelerating adoption of green-steel towers
- Volatility in heavy-plate steel prices distorting cost models
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hybrid steel-concrete towers captured 18.20% of 2025 installations and are forecast to grow 12.68% annually to 2031 as transportation-friendly modules allow >160 m hub heights without escorted road convoys. Concrete savings of up to 40% improve economics, especially in India and China, where local content mandates reward cement sourcing. Nordex's in-house hybrid line underpins the firm's largest-ever 179 m tower deployment, while Vestas-backed Modvion's laminated timber prototype signals a second material revolution beyond steel and concrete. The wind turbine tower market continues to lean on tubular steel for mass production, yet hybrid options are closing the cost gap as raw-plate volatility persists.
OEMs racing toward vertical integration highlight strategic value capture. GE Vernova's Missouri plant retrofit now outputs flange-ready hybrid sections, shrinking supplier lists and tightening quality control. Independent fabricators respond by upgrading circumferential welding robots and shifting toward corrosion-resistant coatings to defend their share in the wind turbine tower market.
Complete Report Scope:
- By Tower Type
- Tubular Steel Towers
- Concrete Towers
- Hybrid Steel-Concrete Towers
- Lattice Towers
- Guyed Pole Towers
- Modular/Stacked Composite Towers
- By Deployment
- Onshore
- Offshore (Fixed-Bottom)
- Offshore (Floating)
- By Tower Height (m)
- Up to 80 m
- 81 to 120 m
- 121 to 160 m
- Above 160 m
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- Denmark
- Sweden
- Norway
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Australia
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific's 42.70% share in 2025 flowed from China's giga-scale steel plate mills and India's rapid hybrid adoption. Yet the spotlight shifts to higher-margin offshore and tall-tower segments as land constraints tighten. Japan's Round 3 auction launches 1.8 GW of 15 MW class turbines, mandating corrosion-resistant towers that elevate regional average selling prices. Simultaneously, South Korea allocates CAPEX to a 6 GW floating pilot cluster off Ulsan, accelerating demand for 160 m monopiles and 200 m hybrid towers.
Europe leverages regulatory foresight to punch above its weight. Streamlined German permitting shaved 18 months from project cycles, rewarding early movers PNE and RWE. EU carbon-border charges shift procurement towards green steel, letting Vestas lock in low-carbon plate at Baltic Power and Nordlicht. Such sustainability premiums buttress European export competitiveness as the wind turbine tower market globalizes.
The Middle East & Africa grows 22.90% annually from a low base as sovereign funds in Saudi Arabia and the UAE bankroll 1-3 GW clusters integrated with green hydrogen hubs. North America's IRA-fuelled factory buildout is shrinking import dependence; CS Wind's Texas ramp-up feeds both U.S. and Latin American demand. South America eyes grid upgrades-Brazil's northeast state-run transmission plan alone frees 9 GW of interconnection-re-energizing the regional project pipeline.
- CS Wind Corporation
- Titan Wind Energy
- Valmont Industries Inc.
- Arcosa Wind Towers Inc.
- Trinity Structural Towers
- Broadwind Energy Inc.
- KGW Schweriner Maschinen- und Anlagenbau
- Dongkuk S&C
- Speco Technologies Co. Ltd
- Vestas Wind Systems A/S
- Siemens Gamesa Renewable Energy
- GE Vernova
- Goldwind
- Enercon GmbH
- Nordex SE
- Senvion SA
- Max Bogl Wind AG
- Ming Yang Smart Energy
- Envision Energy
- Sinoma Wind Towers
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 IRA-Driven Localization of Above 100 m Steel Tower Manufacturing Capacity in the United States
- 4.2.2 Permitting Reforms Enabling Above 160 m Towers in Germany & the Nordics
- 4.2.3 Hybrid Steel-Concrete Towers Cutting LCoE for Low-Wind Inland Sites in India & China
- 4.2.4 EU Carbon Border Adjustment Accelerating Adoption of Green-Steel Towers
- 4.2.5 Surging South-Korean & Japanese Offshore Targets for Over 150 m Corrosion-Resistant Towers
- 4.2.6 On-site 3D-Printed Concrete Towers Slashing Logistics Costs in California & Spain Pilots
- 4.3 Market Restraints
- 4.3.1 Seaborne Logistics Bottlenecks for Above 15 m-Diameter Tower Sections on U.S. East Coast
- 4.3.2 Volatility in Heavy-Plate Steel Prices Distorting Cost Models
- 4.3.3 Delayed Type-Certification for Hybrid Towers in Emerging Markets
- 4.3.4 Local-Content Quotas Constraining Import of Low-Cost Asian Towers
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Tower Type
- 5.1.1 Tubular Steel Towers
- 5.1.2 Concrete Towers
- 5.1.3 Hybrid Steel-Concrete Towers
- 5.1.4 Lattice Towers
- 5.1.5 Guyed Pole Towers
- 5.1.6 Modular/Stacked Composite Towers
- 5.2 By Deployment
- 5.2.1 Onshore
- 5.2.2 Offshore (Fixed-Bottom)
- 5.2.3 Offshore (Floating)
- 5.3 By Tower Height (m)
- 5.3.1 Up to 80 m
- 5.3.2 81 to 120 m
- 5.3.3 121 to 160 m
- 5.3.4 Above 160 m
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Spain
- 5.4.2.5 Italy
- 5.4.2.6 Russia
- 5.4.2.7 Denmark
- 5.4.2.8 Sweden
- 5.4.2.9 Norway
- 5.4.2.10 Rest of Europe
- 5.4.3 Asia Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 ASEAN Countries
- 5.4.3.6 Australia
- 5.4.3.7 Rest of Asia Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 South Africa
- 5.4.5.4 Egypt
- 5.4.5.5 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 CS Wind Corporation
- 6.4.2 Titan Wind Energy
- 6.4.3 Valmont Industries Inc.
- 6.4.4 Arcosa Wind Towers Inc.
- 6.4.5 Trinity Structural Towers
- 6.4.6 Broadwind Energy Inc.
- 6.4.7 KGW Schweriner Maschinen- und Anlagenbau
- 6.4.8 Dongkuk S&C
- 6.4.9 Speco Technologies Co. Ltd
- 6.4.10 Vestas Wind Systems A/S
- 6.4.11 Siemens Gamesa Renewable Energy
- 6.4.12 GE Vernova
- 6.4.13 Goldwind
- 6.4.14 Enercon GmbH
- 6.4.15 Nordex SE
- 6.4.16 Senvion SA
- 6.4.17 Max Bogl Wind AG
- 6.4.18 Ming Yang Smart Energy
- 6.4.19 Envision Energy
- 6.4.20 Sinoma Wind Towers
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

