PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2109216
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2109216
Metal Injection Molding Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
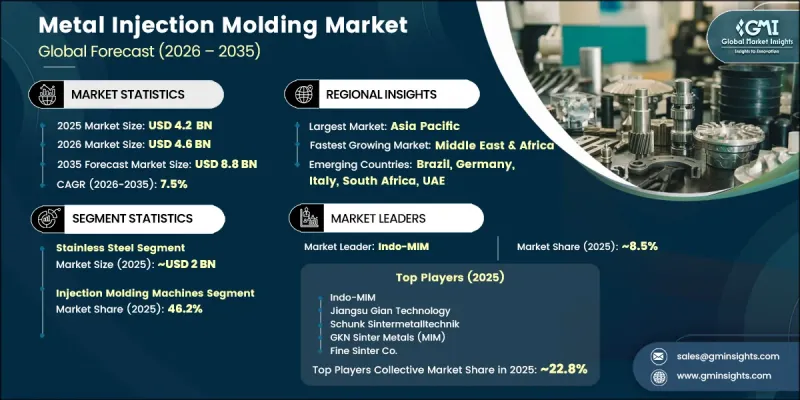
The Global Metal Injection Molding Market was valued at USD 4.2 billion in 2025 and is estimated to grow at a CAGR of 7.5% to reach USD 8.8 billion by 2035.
The global metal injection molding market is witnessing steady expansion as industries increasingly rely on precision-engineered metal components that support large-scale manufacturing while maintaining high dimensional accuracy and material efficiency. Rising production requirements across the automotive, medical device, aerospace, and consumer electronics sectors continue to create strong demand for metal injection molding technologies capable of producing complex parts in high volumes. The ongoing transition toward electric mobility, increasing adoption of advanced medical technologies, and growing digitalization of manufacturing operations are further supporting market growth. Expanding investments in next-generation communication infrastructure and advanced computing systems are also driving the need for precision metal components used throughout the electronics supply chain. At the same time, evolving vehicle platforms are creating new opportunities for metal injection molding as manufacturers require lightweight, durable, and highly accurate components that improve performance and manufacturing efficiency. Continuous technological advancements, greater manufacturing automation, and increasing emphasis on cost-effective production methods are expected to strengthen the long-term outlook for the global metal injection molding industry.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $4.2 Billion |
| Forecast Value | $8.8 Billion |
| CAGR | 7.5% |
The stainless steel segment generated USD 2 billion in 2025 and is projected to grow at a CAGR of 7.5% from 2026 to 2035. Stainless steel continues to dominate the global metal injection molding market because it offers an excellent combination of corrosion resistance, mechanical strength, durability, and long service life across a wide range of industrial applications. Within this category, 316L and 304L stainless steel grades represented approximately 26.5% of the total metal injection molding market value during the base year, reflecting their broad adoption across multiple end-use industries. In addition, the 17-4 PH precipitation-hardening grade accounted for 13.5% of the overall market value due to its ability to deliver high strength, excellent wear resistance, and dependable performance in demanding operating environments.
The injection molding machines segment held a 46.2% share in 2025. Its leadership is supported by increasing demand for advanced manufacturing systems capable of delivering consistent production quality, greater operational efficiency, and high-volume output. Growing investments in automated production facilities and precision manufacturing technologies continue to strengthen the adoption of modern injection molding equipment across multiple industrial sectors.
North America Metal Injection Molding Market accounted for a 17.2% share in 2025. Market growth is supported by strong demand from industries requiring high-precision metal components, increasing domestic manufacturing activity, and continued investments in advanced production capabilities. Ongoing efforts to strengthen regional supply chains and expand local manufacturing capacity are also contributing to higher adoption of metal injection molding technologies, reinforcing the country's leadership within the North American market.
Major companies operating in the global metal injection molding market include Indo-MIM Pvt. Ltd., ARC Group Worldwide, Schunk Sintermetalltechnik GmbH, BASF SE, Epson Atmix Corporation, GKN Sinter Metals, Jiangsu Gian Technology Co., Ltd., Fine Sinter Co., Ltd., Taisei Kogyo Co., Ltd., Porite Corporation / Porite Taiwan, MIMplus Technologies GmbH & Co. KG, Parmaco Metal Injection Moulding AG, Sintex A/S, Parmatech Corporation (ATW Companies), Advanced Powder Products (APP), Smith Metal Products, Elnik Systems LLC, Ryer Inc., DSH Technologies LLC, Taiwan Powder Technologies Co., Ltd., and Advanced Materials Technologies. Companies operating in the global metal injection molding market are strengthening their market position by expanding manufacturing capabilities, investing in advanced production technologies, and improving process automation to enhance efficiency and product consistency. Market participants are focusing on research and development to introduce innovative materials, optimize production methods, and improve component performance across diverse industrial applications. Strategic collaborations with original equipment manufacturers, expansion into high-growth regional markets, and broader product portfolios are helping companies increase their competitive advantage. Businesses are also prioritizing quality assurance, precision manufacturing, and customized component development to address evolving customer requirements.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Region
- 2.2.2 Material Type
- 2.2.3 Equipment Type
- 2.2.4 End-user Industry
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Growing demand for complex, high-precision small components across automotive & electronics
- 3.2.1.2 Rising adoption in medical & orthodontic applications (surgical instruments, implants, brackets)
- 3.2.1.3 EV powertrain transition creating new MIM component demand (lock mechanisms, transmission parts)
- 3.2.1.4 Cost advantage of MIM over CNC machining in high-volume production
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 High initial tooling & setup costs limiting viability for low-volume production
- 3.2.2.2 Part size & weight constraints (typically <100g) restricting application scope
- 3.2.2.3 Sintering shrinkage variability (15–20%) requiring precise mold compensation
- 3.2.2.4 Dependence on imported high-purity metal powders & specialty binders
- 3.2.3 Opportunities
- 3.2.3.1 Micro-MIM for miniaturized medical & wearable electronics components
- 3.2.3.2 Titanium MIM expansion in orthopedic, dental & aerospace applications
- 3.2.3.3 MIM integration with additive manufacturing (hybrid manufacturing platforms)
- 3.2.3.4 Defense & firearms modernization programs driving precision component demand
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Supply Chain Analysis
- 3.4.1 Metal Powder Supply Chain (Atomization, Grades, Key Suppliers)
- 3.4.2 Binder System Supply & Formulation Trends
- 3.4.3 Supply Chain Vulnerabilities & Risk Assessment
- 3.4.4 Nearshoring & Supply Chain Localization Trends
- 3.5 Future market trends
- 3.6 Technology and innovation landscape
- 3.6.1 Current technological trends
- 3.6.2 Emerging technologies
- 3.7 Regulatory landscape
- 3.7.1 Global Manufacturing & Quality Standards (ASTM B883, ISO 22068)
- 3.7.2 Medical Device Regulatory Requirements (FDA, CE Marking, MDR)
- 3.7.3 Aerospace & Defense Qualification Standards (AS9100, NADCAP)
- 3.7.4 Environmental & Workplace Safety Regulations (REACH, RoHS, OSHA)
- 3.8 Trade data analysis
- 3.8.1 Import/Export Volume & Value Trends by HS Code (Sintered Metal Parts) (Driven by Primary Research)
- 3.8.2 Key Trade Corridors & Tariff Impact (China-US, EU-Asia, India-Global) (Driven by Primary Research)
- 3.9 Impact of AI & generative AI on the market
- 3.9.1 AI-Driven Disruption of Existing Business Models (Automated Defect Detection, Predictive Maintenance)
- 3.9.2 GenAI Use Cases & Adoption Roadmap by Segment (Design Optimization, Simulation, Process Control)
- 3.9.3 Risks, Limitations & Regulatory Considerations
- 3.10 Pricing Analysis
- 3.10.1 Historical Price Trend Analysis (Metal Powder, Feedstock, Finished MIM Parts) (Driven by Primary Research)
- 3.10.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus) (Driven by Primary Research)
- 3.11 Porter’s analysis
- 3.12 PESTEL analysis
- 3.13 Consumer Behavior Analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates & Forecast, By Material Type, 2022 – 2035, (USD Billion) (Thousand Units)
- 5.1 Key Trends
- 5.2 Stainless Steel
- 5.2.1 Austenitic Grades (316L, 304L)
- 5.2.2 Precipitation-Hardening Grades (17-4 PH)
- 5.2.3 Ferritic Grades (430L)
- 5.3 Low Alloy Steel
- 5.3.1 MIM-2200 (Fe-Ni)
- 5.3.2 MIM-2700 (Fe-Ni-Mo)
- 5.3.3 MIM-4605 (Fe-Ni-Mo-C)
- 5.4 Soft Magnetic Materials
- 5.4.1 Iron-Silicon Alloys
- 5.4.2 Iron-Nickel Alloys
- 5.5 Titanium Alloys
- 5.5.1 Ti-6Al-4V (Grade 5)
- 5.5.2 Commercially Pure Titanium
- 5.5.3 Cobalt-Chromium Alloys
- 5.6 Others
Chapter 6 Market Estimates & Forecast, By Equipment Type, 2022 – 2035, (USD Billion) (Thousand Units)
- 6.1 Key Trends
- 6.2 Injection Molding Machines
- 6.2.1 Hydraulic Injection Molding Machines
- 6.2.2 Electric Injection Molding Machines
- 6.2.3 Hybrid Injection Molding Machines
- 6.3 Debinding Equipment
- 6.3.1 Solvent Debinding Systems
- 6.3.2 Catalytic Debinding Systems
- 6.3.3 Thermal Debinding Systems
- 6.4 Sintering Furnaces
- 6.4.1 Batch Sintering Furnaces
- 6.4.2 Continuous (Belt/Pusher) Sintering Furnaces
Chapter 7 Market Estimates & Forecast, By End-user Industry, 2022 – 2035, (USD Billion) (Thousand Units)
- 7.1 Key Trends
- 7.2 Automotive
- 7.2.1 Powertrain & Transmission Components
- 7.2.2 Lock & Latch Mechanisms
- 7.2.3 Steering & Braking System Parts
- 7.2.4 EV-Specific Components (Battery System Hardware, Motor Parts)
- 7.3 Medical & Orthodontics
- 7.3.1 Surgical Instruments & Endoscopic Components
- 7.3.2 Orthopedic & Dental Implants
- 7.3.3 Orthodontic Brackets & Attachments
- 7.3.4 Drug Delivery & Diagnostic Device Components
- 7.4 Electrical & Electronics
- 7.4.1 Smartphone & Wearable Device Hardware
- 7.4.2 Connector Housings & EMI Shielding Components
- 7.4.3 Hard Disk Drive (HDD) & Data Storage Components
- 7.4.4 Semiconductor & PCB Hardware
- 7.5 Consumer Goods
- 7.5.1 Eyewear Hinges & Frames
- 7.5.2 Luxury Goods & Apparel Hardware
- 7.5.3 Sporting Goods & Precision Tools
- 7.6 Aerospace & Defense
- 7.6.1 Structural & Actuator Components
- 7.6.2 Avionics & Sensor Housing Parts
- 7.6.3 Firearms & Ordnance Components
- 7.7 Industrial
- 7.7.1 Cutting Tools & Tooling Inserts
- 7.7.2 Valves, Fasteners & Fluid Control Components
- 7.7.3 Precision Gears & Mechanical Assemblies
- 7.8 Others (Energy, Telecom, Emerging Applications)
Chapter 8 Market Estimates & Forecast, By Region, 2022 – 2035, (USD Billion) (Thousand Units)
- 8.1 Key Trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 France
- 8.3.3 UK
- 8.3.4 Italy
- 8.3.5 Spain
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 Japan
- 8.4.3 India
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 MEA
- 8.6.1 Saudi Arabia
- 8.6.2 UAE
- 8.6.3 South Africa
Chapter 9 Company Profiles
- 9.1 Global Leaders
- 9.1.1 Indo-MIM Pvt. Ltd
- 9.1.2 ARC Group Worldwide
- 9.1.3 Schunk Sintermetalltechnik GmbH
- 9.1.4 BASF SE
- 9.1.5 Epson Atmix Corporation
- 9.1.6 GKN Sinter Metals
- 9.1.7 Jiangsu Gian Technology Co., Ltd
- 9.2 Regional Players
- 9.2.1 Fine Sinter Co., Ltd
- 9.2.2 Taisei Kogyo Co., Ltd
- 9.2.3 Porite Corporation / Porite Taiwan
- 9.2.4 MIMplus Technologies GmbH & Co. KG
- 9.2.5 Parmaco Metal Injection Molding AG
- 9.2.6 Sintex A/S
- 9.2.7 Parmatech Corporation (ATW Companies)
- 9.3 Emerging Players
- 9.3.1 Advanced Powder Products (APP)
- 9.3.2 Smith Metal Products
- 9.3.3 Elnik Systems LLC
- 9.3.4 Ryer Inc
- 9.3.5 DSH Technologies LLC
- 9.3.6 Taiwan Powder Technologies Co., Ltd
- 9.3.7 Advanced Materials Technologies

