PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2132664
PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2132664
Network Automation Market by Network Automation Type (Orchestration Automation, Provisioning Automation, Script-driven Network Automation, AI-driven Network Automation, IBN Automation, Network Security Automation) - Global Forecast to 2032
The global network automation market will grow from USD 8.69 billion in 2026 to USD 14.42 billion by 2032, at a compound annual growth rate (CAGR) of 8.8% during the forecast period. The market is being propelled by the increasing scale and heterogeneity of modern network infrastructure, where enterprises must manage data centers, branch environments, cloud resources, and distributed endpoints through increasingly complex operational frameworks. As network teams face pressure to provision services faster while maintaining configuration consistency, automation is gaining importance as a means of standardizing repetitive tasks, coordinating changes, and reducing operational dependencies.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2020-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | USD Million/Billion |
| Segments | Offering, Network Automation Type, Network Type, End User and Region |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, Latin America |
The growing adoption of software-defined networking, network orchestration, APIs, and infrastructure-as-code is further enabling organizations to integrate network operations with broader IT workflows. At the same time, the increasing deployment of cloud-native applications, edge infrastructure, and high-performance computing environments is creating demand for networks capable of responding dynamically to changing workloads. AI-assisted network operations are also expanding the scope of automation by enabling anomaly detection, predictive maintenance, automated troubleshooting, and closed-loop remediation. However, adoption can be constrained by the complexity of modernizing legacy infrastructure, integration requirements across heterogeneous network environments, implementation costs, and the availability of personnel with specialized automation skills. These factors are influencing how enterprises prioritize automation investments and transition toward more centralized, programmable, and autonomous network operations.
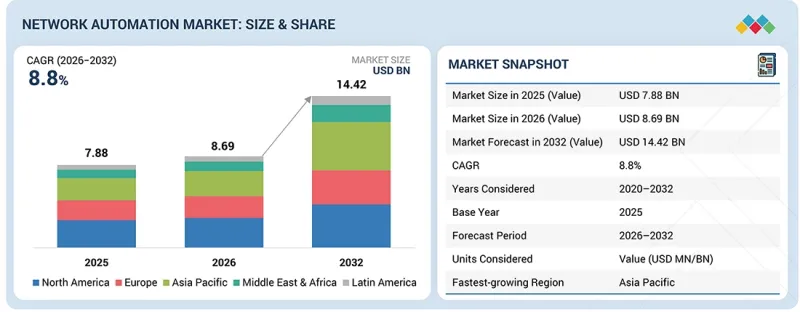
Based on offering, the software segment is expected to hold the largest market share during the forecast period.
Software is expected to account for the largest share of the network automation market as organizations increasingly adopt platforms that provide centralized control over network configuration, orchestration, monitoring, and optimization. Automation software enables network teams to create repeatable workflows, apply policies consistently, and coordinate operations across multi-vendor infrastructure without relying extensively on manual device-level intervention. The growing integration of automation platforms with cloud management, observability, IT service management, and DevOps environments is expanding their role beyond traditional configuration management. In addition, AI-enabled capabilities are allowing software platforms to support intelligent event analysis, predictive insights, and automated remediation, improving the responsiveness of network operations. The increasing adoption of programmable infrastructure and API-based network management is further supporting demand for software that can connect disparate network resources and operational systems. As enterprises seek to improve network agility while controlling operational complexity, software platforms are becoming a core component of automated network management strategies.
Based on network type, the cloud networks segment is expected to grow at the highest CAGR during the forecast period.
Cloud networks are expected to experience the fastest growth as enterprises increasingly distribute applications and workloads across public cloud, private cloud, and hybrid environments. Managing connectivity across these environments requires greater levels of orchestration to ensure that network resources remain aligned with application requirements and changing workloads. Automation enables organizations to provision cloud network resources, manage policies, configure connectivity, and coordinate changes across distributed environments with greater speed and consistency. The expansion of multi-cloud strategies is further increasing the need for centralized visibility and automated workflows that can operate across different cloud platforms and network architectures. Integration with cloud-native orchestration tools and application deployment pipelines is also enabling network operations to become more closely connected with compute and application lifecycles. As enterprises continue to adopt dynamic cloud environments, the ability to automate network provisioning and policy enforcement is expected to make cloud networking a significant growth area within the market.
Asia Pacific is expected to grow at the highest CAGR during the forecast period.
Asia Pacific is expected to register the highest growth in the network automation market as enterprises and service providers across the region accelerate infrastructure modernization and digital transformation initiatives. Increasing investments in cloud infrastructure, data centers, telecommunications networks, and distributed computing environments are creating a broader requirement for automated network management. The rapid expansion of enterprise connectivity and the growing scale of digital services are also increasing the operational burden associated with manually configuring and maintaining network infrastructure. Organizations are therefore adopting software-driven approaches to improve provisioning speed, network visibility, and resource utilization. In addition, the development of advanced data center infrastructure and the expansion of edge computing are creating new use cases for programmable and automated networks. Service providers are also increasingly focused on improving operational efficiency and accelerating the deployment of network services across large-scale infrastructure. As organizations across the region move toward cloud-centric and software-defined environments, increasing investments in network modernization are expected to support the rapid adoption of network automation solutions throughout Asia Pacific.
Breakdown of primaries
We interviewed Chief Executive Officers (CEOs), directors of innovation and technology, system integrators, and executives from several significant network automation market companies.
- By Company: Tier I: 35%, Tier II: 40%, and Tier III: 25%
- By Designation: C-Level Executives: 40%, Director Level: 25%, and Others: 35%
- By Region: North America: 25%, Europe: 35%, Asia Pacific: 30%, Rest of World: 10%
Some of the significant network automation vendors are Cisco (US), IBM (US), HPE (US), Huawei (China), Broadcom (US), Arista Networks (US), Nokia (Finland), Ericsson (Sweden), Extreme Networks (US), Fujitsu (Japan).
Research coverage:
The market report covered the network automation market across segments. We estimated the market size and growth potential for many segments based on offering, network automation type, network type, end user, and region. It contains a thorough competitive analysis of the major market participants, information about their businesses, essential observations about their product offerings, current trends, and critical market strategies.
Reasons to buy this report:
With information on the most accurate revenue estimates for the whole network automation industry and its subsegments, the research will benefit market leaders and recent newcomers. Stakeholders will benefit from this report's increased understanding of the competitive environment, which will help them better position their companies and develop go-to-market strategies. The research offers information on the main market drivers, constraints, opportunities, and challenges, as well as aids players in understanding the pulse of the industry.
The report provides insights on the following pointers:
Analysis of key drivers (Rising network complexity & scale, need for operational efficiency & cost reduction, and security & compliance requirements), restraints (High initial investment & integration challenges, and lack of skilled workforce), opportunities (Integration of AI and ML in network automation to drive autonomous networks, 5G & edge computing expansion, and cloud-native & multi-vendor interoperability), and challenges (Security risks of automated networks, and vendor lock-in & interoperability issues).
- Product Development/Innovation: Comprehensive analysis of emerging technologies, R&D initiatives, and new service and product introductions in the network automation market
- Market Development: In-depth details regarding profitable markets: the paper examines the global network automation market
- Market Diversification: Comprehensive details regarding recent advancements, investments, unexplored regions, new goods and services, and the network automation market
- Competitive Assessment: Thorough analysis of the market shares, expansion plans, platforms, and service portfolios of the top competitors in the network automation industry, such as Cisco (US), IBM (US), HPE (US), Huawei (China), Broadcom (US), Arista Networks (US), Nokia (Finland), Ericsson (Sweden), Extreme Networks (US), Fujitsu (Japan), NetBrain Technologies (US), Gluware (US), SolarWinds (US), Riverbed (US), Forward Networks (US), Palo Alto Networks (US), Aviz Networks (US), Itential (US), BackBox (US), Flock9 (Netherlands), Anuta Networks (US), Versa Networks (US), Infoblox (US), Auvik Networks (Canada), Arrcus (US), BlueCat (Canada), and Stardust Systems (US)
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN NETWORK AUTOMATION MARKET
- 2.4 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN NETWORK AUTOMATION MARKET
- 3.2 NETWORK AUTOMATION MARKET, BY OFFERING, 2026
- 3.3 NETWORK AUTOMATION MARKET, BY END USER, 2026
- 3.4 NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026
- 3.5 NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026
- 3.6 NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026
- 3.7 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY TOP 3 NETWORK TYPES & COUNTRY, 2026
- 3.8 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY TOP 3 NETWORK TYPES & COUNTRIES, 2026
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising network complexity & scale
- 4.2.1.2 Need for operational efficiency & cost reduction
- 4.2.1.3 Security & compliance requirements
- 4.2.1.4 Expansion of AI infrastructure & high-performance data center networks
- 4.2.2 RESTRAINTS
- 4.2.2.1 High initial investment & integration challenges
- 4.2.2.2 Lack of skilled workforce
- 4.2.2.3 Data quality & automation readiness constraints
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Integration of AI and ML in network automation
- 4.2.3.2 5G rollout & edge computing expansion
- 4.2.3.3 Cloud-native & API-driven network automation
- 4.2.3.4 Expansion of closed-loop & intent-based network operations
- 4.2.4 CHALLENGES
- 4.2.4.1 Security risks of automated networks
- 4.2.4.2 Vendor lock-in & interoperability issues
- 4.2.1 DRIVERS
- 4.3 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.3.1 INTERCONNECTED MARKETS
- 4.3.2 CROSS-SECTOR OPPORTUNITIES
- 4.4 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN NETWORK AUTOMATION MARKET
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.3.1 TECHNOLOGY & INFRASTRUCTURE PROVIDERS
- 5.3.2 SOFTWARE & PLATFORM PROVIDERS
- 5.3.3 INTEGRATION & SERVICE PROVIDERS
- 5.3.4 END USERS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 INDICATIVE PRICING OF NETWORK AUTOMATION OFFERINGS, 2025
- 5.5.2 INDICATIVE PRICING OF NETWORK AUTOMATION SOFTWARE, BY NETWORK SCALE, 2025
- 5.6 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.7 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 CASE STUDY ANALYSIS
- 5.9.1 LEADING FINANCIAL FIRM AUTOMATES APPLICATION SERVICES WITH CISCO ACI AND AVI NETWORKS
- 5.9.2 HARRY REID INTERNATIONAL AIRPORT ACHIEVES SEAMLESS CONNECTIVITY AND OPERATIONAL INSIGHTS WITH HPE ARUBA NETWORKING
- 5.9.3 VODAFONE GROUP CREATES NIMBLE SERVICE INNOVATION PLATFORM WITH VMWARE NFV
- 5.9.4 IBM CIO ORGANIZATION OPTIMIZES MULTI-TENANT ENVIRONMENT WITH TURBONOMIC AUTOMATION
- 5.9.5 ARCELIK MODERNIZES MANUFACTURING WITH HIGH-PERFORMANCE NOKIA PRIVATE 5G NETWORK
- 5.9.6 FINANCIAL SERVICES COMPANY ACHIEVES CLOUD TRANSFORMATION WITH ARISTA'S CONVERGED CLOUD FABRIC
- 5.10 IMPACT OF 2025 US TARIFF - NETWORK AUTOMATION MARKET
- 5.10.1 INTRODUCTION
- 5.10.2 IMPACT OF 2025 US TARIFF ON NETWORK AUTOMATION MARKET
- 5.10.3 KEY TARIFF RATES
- 5.10.4 PRICE IMPACT ANALYSIS
- 5.10.4.1 Strategic shifts and emerging trends
- 5.10.5 IMPACT ON COUNTRIES/REGIONS
- 5.10.5.1 US
- 5.10.5.2 China
- 5.10.5.3 Europe
- 5.10.5.4 Asia Pacific (excluding China)
- 5.10.6 IMPACT ON END-USER INDUSTRIES
- 5.10.6.1 Banking, financial services, and insurance (BFSI)
- 5.10.6.2 Healthcare and life sciences
- 5.10.6.3 Retail and e-commerce
- 5.10.6.4 Telecom and technology
- 5.10.6.5 Government and public sector
- 5.10.6.6 Manufacturing and industrial
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 SOFTWARE-DEFINED NETWORKING (SDN)
- 6.1.2 NETWORK FUNCTION VIRTUALIZATION (NFV)
- 6.1.3 INTENT-BASED NETWORKING (IBN)
- 6.1.4 ARTIFICIAL INTELLIGENCE (AI) & MACHINE LEARNING (ML)
- 6.2 ADJACENT TECHNOLOGIES
- 6.2.1 CLOUD COMPUTING
- 6.2.2 5G
- 6.2.3 NETWORK MONITORING & OBSERVABILITY
- 6.3 COMPLEMENTARY TECHNOLOGIES
- 6.3.1 DIGITAL TWIN
- 6.3.2 ROBOTIC PROCESS AUTOMATION (RPA)
- 6.4 TECHNOLOGY ROADMAP
- 6.4.1 SHORT-TERM (2026-2027)
- 6.4.2 MID-TERM (2028-2029)
- 6.4.3 LONG-TERM (2030+)
- 6.5 PATENT ANALYSIS
- 6.6 IMPACT OF AI/GEN AI ON NETWORK AUTOMATION MARKET
- 6.6.1 TOP USE CASES AND MARKET POTENTIAL
- 6.6.2 CASE STUDIES OF AI IMPLEMENTATION IN NETWORK AUTOMATION MARKET
- 6.6.3 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.6.4 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN NETWORK AUTOMATION MARKET
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 KEY REGULATIONS
- 7.1.2.1 North America
- 7.1.2.1.1 US
- 7.1.2.1.2 Canada
- 7.1.2.2 Europe
- 7.1.2.3 Asia Pacific
- 7.1.2.3.1 South Korea
- 7.1.2.3.2 China
- 7.1.2.3.3 India
- 7.1.2.4 Middle East & Africa
- 7.1.2.4.1 UAE
- 7.1.2.4.2 KSA
- 7.1.2.5 Latin America
- 7.1.2.5.1 Brazil
- 7.1.2.5.2 Mexico
- 7.1.2.1 North America
- 7.1.3 INDUSTRY STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS END-USE INDUSTRIES
9 NETWORK AUTOMATION MARKET, BY OFFERING
- 9.1 INTRODUCTION
- 9.1.1 OFFERING: MARKET DRIVERS
- 9.2 SOFTWARE
- 9.2.1 ENABLING PROGRAMMABLE AND INTELLIGENT NETWORK OPERATIONS
- 9.3 SERVICES
- 9.3.1 PROFESSIONAL SERVICES
- 9.3.1.1 Enabling strategic implementation and integration of network automation
- 9.3.1.2 Advisory & consulting
- 9.3.1.3 Deployment & integration
- 9.3.1.4 Training & support
- 9.3.2 MANAGED SERVICES
- 9.3.2.1 Ensuring continuous optimization and reliable network operations
- 9.3.1 PROFESSIONAL SERVICES
10 NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE
- 10.1 INTRODUCTION
- 10.1.1 NETWORK AUTOMATION TYPE: MARKET DRIVERS
- 10.2 ORCHESTRATION AUTOMATION
- 10.2.1 COORDINATING NETWORK WORKFLOWS AND RESOURCES TO SIMPLIFY OPERATIONS ACROSS COMPLEX ENVIRONMENTS
- 10.3 PROVISIONING AUTOMATION
- 10.3.1 ACCELERATING NETWORK RESOURCE DEPLOYMENT AND CONFIGURATION TO IMPROVE OPERATIONAL CONSISTENCY
- 10.4 SCRIPT-DRIVEN NETWORK AUTOMATION
- 10.4.1 ENABLING FLEXIBLE, TASK-SPECIFIC AUTOMATION THROUGH PROGRAMMABLE NETWORK WORKFLOWS
- 10.5 AI-DRIVEN NETWORK AUTOMATION
- 10.5.1 APPLYING AI AND ANALYTICS TO ENABLE PREDICTIVE, ADAPTIVE, AND INCREASINGLY AUTONOMOUS NETWORK OPERATIONS
- 10.6 INTENT-BASED NETWORK AUTOMATION
- 10.6.1 TRANSLATING HIGH-LEVEL OPERATIONAL REQUIREMENTS INTO DYNAMIC NETWORK POLICIES
- 10.7 NETWORK SECURITY AUTOMATION
- 10.7.1 AUTOMATING SECURITY POLICIES, THREAT RESPONSE, AND NETWORK PROTECTION TO IMPROVE RESILIENCE
- 10.8 OTHER NETWORK AUTOMATION TYPES
11 NETWORK AUTOMATION MARKET, BY NETWORK TYPE
- 11.1 INTRODUCTION
- 11.1.1 NETWORK TYPE: MARKET DRIVERS
- 11.2 DATA CENTER NETWORKS
- 11.2.1 AUTOMATING DATA CENTER OPERATIONS TO SUPPORT DYNAMIC WORKLOADS AND SCALABLE INFRASTRUCTURE
- 11.3 CLOUD NETWORKS
- 11.3.1 AUTOMATING CONNECTIVITY AND RESOURCE MANAGEMENT ACROSS DYNAMIC CLOUD ENVIRONMENTS
- 11.4 WIRELESS NETWORKS
- 11.4.1 AUTOMATING WIRELESS OPERATIONS TO IMPROVE PERFORMANCE AND CONNECTIVITY AT SCALE
- 11.5 SOFTWARE-DEFINED WIDE AREA NETWORKS (SD-WAN)
- 11.5.1 DISTRIBUTED WAN OPERATIONS THROUGH CENTRALIZED POLICY AND TRAFFIC MANAGEMENT
- 11.6 CAMPUS NETWORKS
- 11.6.1 ENTERPRISE CAMPUS MANAGEMENT THROUGH AUTOMATED PROVISIONING AND POLICY CONTROL
- 11.7 OTHER NETWORK TYPES
12 NETWORK AUTOMATION MARKET, BY END USER
- 12.1 INTRODUCTION
- 12.1.1 END USER: MARKET DRIVERS
- 12.2 SERVICE PROVIDERS
- 12.2.1 AUTOMATING LARGE-SCALE NETWORK OPERATIONS TO IMPROVE SERVICE AGILITY AND RESOURCE UTILIZATION
- 12.3 ENTERPRISES
- 12.3.1 MODERNIZING DISTRIBUTED NETWORK INFRASTRUCTURE THROUGH AUTOMATION
- 12.3.2 BFSI
- 12.3.3 HEALTHCARE
- 12.3.4 RETAIL & E-COMMERCE
- 12.3.5 MANUFACTURING
- 12.3.6 GOVERNMENT & DEFENSE
- 12.3.7 ENERGY & UTILITIES
- 12.3.8 OTHER ENTERPRISES
13 NETWORK AUTOMATION MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 US
- 13.2.1.1 AI infrastructure and autonomous operations reshape enterprise networking
- 13.2.2 CANADA
- 13.2.2.1 Growing adoption of cloud-based and AI-assisted NetOps
- 13.2.1 US
- 13.3 EUROPE
- 13.3.1 UK
- 13.3.1.1 Moving network automation toward autonomous enterprise operations
- 13.3.2 GERMANY
- 13.3.2.1 Industrial complexity pushing automation deeper into network operations
- 13.3.3 FRANCE
- 13.3.3.1 Digital infrastructure expansion increasing need for coordinated network management
- 13.3.4 ITALY
- 13.3.4.1 Accelerating network automation for digital future to drive market
- 13.3.5 REST OF EUROPE
- 13.3.1 UK
- 13.4 ASIA PACIFIC
- 13.4.1 CHINA
- 13.4.1.1 Large-scale telecom operations accelerating closed-loop network automation
- 13.4.2 JAPAN
- 13.4.2.1 Automation extending from network operations to infrastructure deployment
- 13.4.3 INDIA
- 13.4.3.1 Large and diverse telecom infrastructure increasing demand for centralized automation
- 13.4.4 REST OF ASIA PACIFIC
- 13.4.1 CHINA
- 13.5 MIDDLE EAST & AFRICA
- 13.5.1 UAE
- 13.5.1.1 Strong digital infrastructure supporting advanced network automation adoption
- 13.5.2 KSA
- 13.5.2.1 Digital infrastructure investments creating demand for network orchestration
- 13.5.3 SOUTH AFRICA
- 13.5.3.1 Network reliability and operational continuity driving automation adoption
- 13.5.4 REST OF MIDDLE EAST & AFRICA
- 13.5.1 UAE
- 13.6 LATIN AMERICA
- 13.6.1 BRAZIL
- 13.6.1.1 Data center and telecom modernization supporting network automation
- 13.6.2 MEXICO
- 13.6.2.1 Backbone modernization creating foundation for automated network management
- 13.6.3 REST OF LATIN AMERICA
- 13.6.1 BRAZIL
14 COMPETITIVE LANDSCAPE
- 14.1 INTRODUCTION
- 14.2 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2023-2026
- 14.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY NETWORK AUTOMATION PLAYERS
- 14.3 REVENUE ANALYSIS, 2021-2025
- 14.4 MARKET SHARE ANALYSIS, 2025
- 14.5 BRAND/PRODUCT COMPARISON
- 14.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 14.6.1 STARS
- 14.6.2 EMERGING LEADERS
- 14.6.3 PERVASIVE PLAYERS
- 14.6.4 PARTICIPANTS
- 14.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 14.6.5.1 Company footprint
- 14.6.5.2 Region footprint
- 14.6.5.3 Offering footprint
- 14.6.5.4 Network type footprint
- 14.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 14.7.1 PROGRESSIVE COMPANIES
- 14.7.2 RESPONSIVE COMPANIES
- 14.7.3 DYNAMIC COMPANIES
- 14.7.4 STARTING BLOCKS
- 14.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 14.7.5.1 Detailed list of key startups/SMEs
- 14.7.5.2 Competitive benchmarking of key startups/SMEs
- 14.8 COMPANY VALUATION AND FINANCIAL METRICS
- 14.9 COMPETITIVE SCENARIO
- 14.9.1 PRODUCT LAUNCHES
- 14.9.2 DEALS
15 COMPANY PROFILES
- 15.1 KEY PLAYERS
- 15.1.1 CISCO
- 15.1.1.1 Business overview
- 15.1.1.2 Products/Solutions/Services offered
- 15.1.1.3 Recent developments
- 15.1.1.3.1 Product launches/enhancements
- 15.1.1.3.2 Deals
- 15.1.1.4 MnM view
- 15.1.1.4.1 Key strengths
- 15.1.1.4.2 Strategic choices
- 15.1.1.4.3 Weaknesses and competitive threats
- 15.1.2 HPE
- 15.1.2.1 Business overview
- 15.1.2.2 Products/Solutions/Services offered
- 15.1.2.3 Recent developments
- 15.1.2.3.1 Product launches/enhancements
- 15.1.2.3.2 Deals
- 15.1.2.4 MnM view
- 15.1.2.4.1 Key strengths
- 15.1.2.4.2 Strategic choices
- 15.1.2.4.3 Weaknesses and competitive threats
- 15.1.3 IBM
- 15.1.3.1 Business overview
- 15.1.3.2 Products/Solutions/Services offered
- 15.1.3.3 Recent developments
- 15.1.3.3.1 Product launches/enhancements
- 15.1.3.3.2 Deals
- 15.1.3.4 MnM view
- 15.1.3.4.1 Key strengths
- 15.1.3.4.2 Strategic choices
- 15.1.3.4.3 Weaknesses and competitive threats
- 15.1.4 HUAWEI
- 15.1.4.1 Business overview
- 15.1.4.2 Products/Solutions/Services offered
- 15.1.4.3 Recent developments
- 15.1.4.3.1 Product launches/enhancements
- 15.1.4.3.2 Deals
- 15.1.4.4 MnM view
- 15.1.4.4.1 Key strengths
- 15.1.4.4.2 Strategic choices
- 15.1.4.4.3 Weaknesses and competitive threats
- 15.1.5 NOKIA
- 15.1.5.1 Business overview
- 15.1.5.2 Products/Solutions/Services offered
- 15.1.5.3 Recent developments
- 15.1.5.3.1 Product launches/enhancements
- 15.1.5.3.2 Deals
- 15.1.5.4 MnM view
- 15.1.5.4.1 Key strengths
- 15.1.5.4.2 Strategic choices
- 15.1.5.4.3 Weaknesses and competitive threats
- 15.1.6 BROADCOM
- 15.1.6.1 Business overview
- 15.1.6.2 Products/Solutions/Services offered
- 15.1.6.3 Recent developments
- 15.1.6.3.1 Product launches/enhancements
- 15.1.6.3.2 Deals
- 15.1.7 ARISTA NETWORKS
- 15.1.7.1 Business overview
- 15.1.7.2 Products/Solutions/Services offered
- 15.1.7.3 Recent developments
- 15.1.7.3.1 Product launches/enhancements
- 15.1.7.3.2 Deals
- 15.1.8 ERICSSON
- 15.1.8.1 Business overview
- 15.1.8.2 Products/Solutions/Services offered
- 15.1.8.3 Recent developments
- 15.1.8.3.1 Product launches/enhancements
- 15.1.8.3.2 Deals
- 15.1.9 EXTREME NETWORKS
- 15.1.9.1 Business overview
- 15.1.9.2 Products/Solutions/Services offered
- 15.1.9.3 Recent developments
- 15.1.9.3.1 Product launches/enhancements
- 15.1.9.3.2 Deals
- 15.1.10 FUJITSU
- 15.1.10.1 Business overview
- 15.1.10.2 Products/Solutions/Services offered
- 15.1.10.3 Recent developments
- 15.1.10.3.1 Deals
- 15.1.1 CISCO
- 15.2 OTHER PLAYERS
- 15.2.1 NETBRAIN TECHNOLOGIES
- 15.2.2 GLUWARE
- 15.2.3 SOLARWINDS
- 15.2.4 RIVERBED
- 15.2.5 FORWARD NETWORKS
- 15.2.6 PALO ALTO NETWORKS
- 15.3 STARTUPS/SMES
- 15.3.1 AVIZ NETWORKS
- 15.3.2 ITENTIAL
- 15.3.3 BACKBOX
- 15.3.4 FLOCK9
- 15.3.5 ANUTA NETWORKS
- 15.3.6 VERSA NETWORKS
- 15.3.7 INFOBLOX
- 15.3.8 AUVIK NETWORKS
- 15.3.9 ARRCUS
- 15.3.10 BLUECAT
- 15.3.11 STARDUST SYSTEMS
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.1.1 Secondary sources
- 16.1.2 PRIMARY DATA
- 16.1.2.1 Breakup of primary profiles
- 16.1.2.2 Primary sources
- 16.1.2.3 Key industry insights
- 16.1.1 SECONDARY DATA
- 16.2 MARKET SIZE ESTIMATION
- 16.2.1 BOTTOM-UP APPROACH
- 16.2.2 TOP-DOWN APPROACH
- 16.3 MARKET BREAKUP AND DATA TRIANGULATION
- 16.4 MARKET FORECAST
- 16.5 RESEARCH ASSUMPTIONS
- 16.6 RESEARCH LIMITATIONS
17 APPENDIX
- 17.1 DISCUSSION GUIDE
- 17.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.3 CUSTOMIZATION OPTIONS
- 17.4 RELATED REPORTS
- 17.5 AUTHOR DETAILS
List of Tables
- TABLE 1 USD EXCHANGE RATES, 2021-2025
- TABLE 2 INTERCONNECTED MARKETS
- TABLE 3 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- TABLE 4 IMPACT OF PORTER'S FIVE FORCES ON NETWORK AUTOMATION MARKET
- TABLE 5 GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2021-2029
- TABLE 6 ROLE OF PLAYERS IN NETWORK AUTOMATION ECOSYSTEM
- TABLE 7 INDICATIVE PRICING OF NETWORK AUTOMATION OFFERINGS, 2025
- TABLE 8 INDICATIVE PRICING OF NETWORK AUTOMATION SOFTWARE, BY NETWORK SCALE, 2025
- TABLE 9 NETWORK AUTOMATION MARKET: LIST OF KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 11 LIST OF MAJOR PATENTS, 2022-2026
- TABLE 12 TOP USE CASES AND MARKET POTENTIAL
- TABLE 13 NETWORK AUTOMATION MARKET: CASE STUDIES RELATED TO GEN AI IMPLEMENTATION
- TABLE 14 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- TABLE 15 NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 16 EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 17 ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 18 REST OF THE WORLD: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 19 GLOBAL INDUSTRY STANDARDS IN NETWORK AUTOMATION MARKET
- TABLE 20 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE ENTERPRISES
- TABLE 21 KEY BUYING CRITERIA FOR TOP THREE ENTERPRISES
- TABLE 22 UNMET NEEDS IN NETWORK AUTOMATION MARKET, BY END-USE INDUSTRY
- TABLE 23 NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 24 NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 25 SOFTWARE: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 26 SOFTWARE: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 27 SERVICES: NETWORK AUTOMATION MARKET, BY TYPE, 2020-2025 (USD MILLION)
- TABLE 28 SERVICES: NETWORK AUTOMATION MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 29 SERVICES: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 30 SERVICES: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 31 PROFESSIONAL SERVICES: NETWORK AUTOMATION MARKET, BY TYPE, 2020-2025 (USD MILLION)
- TABLE 32 PROFESSIONAL SERVICES: NETWORK AUTOMATION MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 33 PROFESSIONAL SERVICES: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 34 PROFESSIONAL SERVICES: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 35 ADVISORY & CONSULTING: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 36 ADVISORY & CONSULTING: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 37 DEPLOYMENT & INTEGRATION: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 38 DEPLOYMENT & INTEGRATION: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 39 TRAINING & SUPPORT: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 40 TRAINING & SUPPORT: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 41 MANAGED SERVICES: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 42 MANAGED SERVICES: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 43 NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 44 NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 45 ORCHESTRATION AUTOMATION: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 46 ORCHESTRATION AUTOMATION: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 47 PROVISIONING AUTOMATION: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 48 PROVISIONING AUTOMATION: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 49 SCRIPT-DRIVEN NETWORK AUTOMATION: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 50 SCRIPT-DRIVEN NETWORK AUTOMATION: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 51 AI-DRIVEN NETWORK AUTOMATION: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 52 AI-DRIVEN NETWORK AUTOMATION: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 53 INTENT-BASED NETWORK AUTOMATION: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 54 INTENT-BASED NETWORK AUTOMATION: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 55 NETWORK SECURITY AUTOMATION: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 56 NETWORK SECURITY AUTOMATION: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 57 OTHER NETWORK AUTOMATION TYPES: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 58 OTHER NETWORK AUTOMATION TYPES: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 59 NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 60 NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 61 DATA CENTER NETWORKS: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 62 DATA CENTER NETWORKS: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 63 CLOUD NETWORKS: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 64 CLOUD NETWORKS: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 65 WIRELESS NETWORKS: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 66 WIRELESS NETWORKS: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 67 SD-WAN: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 68 SD-WAN: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 69 CAMPUS NETWORKS: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 70 CAMPUS NETWORKS: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 71 OTHER NETWORK TYPES: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 72 OTHER NETWORK TYPES: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 73 NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 74 NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 75 SERVICE PROVIDERS: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 76 SERVICE PROVIDERS: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 77 ENTERPRISES: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 78 ENTERPRISES: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 79 NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 80 NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 81 BFSI: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 82 BFSI: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 83 HEALTHCARE: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 84 HEALTHCARE: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 85 RETAIL & E-COMMERCE: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 86 RETAIL & E-COMMERCE: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 87 MANUFACTURING: NETWORK AUTOMATION MARKET, BY REGION, / 2020-2025 (USD MILLION)
- TABLE 88 MANUFACTURING: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 89 GOVERNMENT & DEFENSE: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 90 GOVERNMENT & DEFENSE: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 91 ENERGY & UTILITIES: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 92 ENERGY & UTILITIES: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 93 OTHER ENTERPRISES: NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 94 OTHER ENTERPRISES: NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 95 NETWORK AUTOMATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 96 NETWORK AUTOMATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 97 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 98 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 99 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 100 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 101 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 102 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 103 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 104 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 105 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 106 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 107 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 108 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 109 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 110 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 111 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY COUNTRY, 2020-2025 (USD MILLION)
- TABLE 112 NORTH AMERICA: NETWORK AUTOMATION MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 113 US: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 114 US: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 115 US: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 116 US: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 117 US: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 118 US: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 119 US: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 120 US: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 121 US: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 122 US: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 123 US: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 124 US: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 125 US: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 126 US: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 127 CANADA: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 128 CANADA: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 129 CANADA: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 130 CANADA: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 131 CANADA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 132 CANADA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 133 CANADA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 134 CANADA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 135 CANADA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 136 CANADA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 137 CANADA: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 138 CANADA: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 139 CANADA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 140 CANADA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 141 EUROPE: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 142 EUROPE: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 143 EUROPE: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 144 EUROPE: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 145 EUROPE: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 146 EUROPE: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 147 EUROPE: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 148 EUROPE: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 149 EUROPE: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 150 EUROPE: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 151 EUROPE: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 152 EUROPE: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 153 EUROPE: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 154 EUROPE: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 155 EUROPE: NETWORK AUTOMATION MARKET, BY COUNTRY, 2020-2025 (USD MILLION)
- TABLE 156 EUROPE: NETWORK AUTOMATION MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 157 UK: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 158 UK: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 159 UK: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 160 UK: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 161 UK: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 162 UK: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 163 UK: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 164 UK: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 165 UK: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 166 UK: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 167 UK: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 168 UK: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 169 UK: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 170 UK: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 171 GERMANY: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 172 GERMANY: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 173 GERMANY: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 174 GERMANY: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 175 GERMANY: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 176 GERMANY: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 177 GERMANY: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 178 GERMANY: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 179 GERMANY: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 180 GERMANY: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 181 GERMANY: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 182 GERMANY: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 183 GERMANY: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 184 GERMANY: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 185 FRANCE: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 186 FRANCE: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 187 FRANCE: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 188 FRANCE: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 189 FRANCE: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 190 FRANCE: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 191 FRANCE: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 192 FRANCE: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 193 FRANCE: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 194 FRANCE: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 195 FRANCE: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 196 FRANCE: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 197 FRANCE: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 198 FRANCE: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 199 ITALY: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 200 ITALY: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 201 ITALY: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 202 ITALY: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 203 ITALY: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 204 ITALY: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 205 ITALY: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 206 ITALY: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 207 ITALY: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 208 ITALY: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 209 ITALY: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 210 ITALY: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 211 ITALY: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 212 ITALY: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 213 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 214 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 215 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 216 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 217 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 218 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 219 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 220 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 221 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 222 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 223 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 224 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 225 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 226 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 227 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY COUNTRY, 2020-2025 (USD MILLION)
- TABLE 228 ASIA PACIFIC: NETWORK AUTOMATION MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 229 CHINA: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 230 CHINA: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 231 CHINA: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 232 CHINA: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 233 CHINA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 234 CHINA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 235 CHINA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 236 CHINA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 237 CHINA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 238 CHINA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 239 CHINA: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 240 CHINA: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 241 CHINA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 242 CHINA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 243 JAPAN: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 244 JAPAN: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 245 JAPAN: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 246 JAPAN: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 247 JAPAN: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 248 JAPAN: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 249 JAPAN: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 250 JAPAN: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 251 JAPAN: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 252 JAPAN: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 253 JAPAN: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 254 JAPAN: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 255 JAPAN: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 256 JAPAN: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 257 INDIA: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 258 INDIA: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 259 INDIA: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 260 INDIA: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 261 INDIA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 262 INDIA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 263 INDIA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 264 INDIA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 265 INDIA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 266 INDIA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 267 INDIA: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 268 INDIA: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 269 INDIA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 270 INDIA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 271 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 272 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 273 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 274 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 275 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 276 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 277 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 278 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 279 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 280 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 281 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 282 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 283 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 284 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 285 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY COUNTRY, 2020-2025 (USD MILLION)
- TABLE 286 MIDDLE EAST & AFRICA: NETWORK AUTOMATION MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 287 UAE: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 288 UAE: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 289 UAE: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 290 UAE: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 291 UAE: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 292 UAE: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 293 UAE: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 294 UAE: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 295 UAE: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 296 UAE: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 297 UAE: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 298 UAE: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 299 UAE: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 300 UAE: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 301 KSA: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 302 KSA: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 303 KSA: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 304 KSA: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 305 KSA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 306 KSA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 307 KSA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 308 KSA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 309 KSA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 310 KSA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 311 KSA: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 312 KSA: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 313 KSA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 314 KSA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 315 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 316 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 317 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 318 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 319 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 320 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 321 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 322 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 323 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 324 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 325 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 326 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 327 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 328 SOUTH AFRICA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 329 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 330 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 331 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 332 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 333 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 334 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 335 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 336 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 337 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 338 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 339 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 340 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 341 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 342 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 343 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY COUNTRY, 2020-2025 (USD MILLION)
- TABLE 344 LATIN AMERICA: NETWORK AUTOMATION MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 345 BRAZIL: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 346 BRAZIL: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 347 BRAZIL: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 348 BRAZIL: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 349 BRAZIL: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 350 BRAZIL: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 351 BRAZIL: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 352 BRAZIL: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 353 BRAZIL: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 354 BRAZIL: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 355 BRAZIL: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 356 BRAZIL: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 357 BRAZIL: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 358 BRAZIL: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 359 MEXICO: NETWORK AUTOMATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 360 MEXICO: NETWORK AUTOMATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 361 MEXICO: NETWORK AUTOMATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 362 MEXICO: NETWORK AUTOMATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 363 MEXICO: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2020-2025 (USD MILLION)
- TABLE 364 MEXICO: NETWORK AUTOMATION MARKET, BY PROFESSIONAL SERVICE, 2026-2032 (USD MILLION)
- TABLE 365 MEXICO: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2020-2025 (USD MILLION)
- TABLE 366 MEXICO: NETWORK AUTOMATION MARKET, BY NETWORK AUTOMATION TYPE, 2026-2032 (USD MILLION)
- TABLE 367 MEXICO: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2020-2025 (USD MILLION)
- TABLE 368 MEXICO: NETWORK AUTOMATION MARKET, BY NETWORK TYPE, 2026-2032 (USD MILLION)
- TABLE 369 MEXICO: NETWORK AUTOMATION MARKET, BY END USER, 2020-2025 (USD MILLION)
- TABLE 370 MEXICO: NETWORK AUTOMATION MARKET, BY END USER, 2026-2032 (USD MILLION)
- TABLE 371 MEXICO: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2020-2025 (USD MILLION)
- TABLE 372 MEXICO: NETWORK AUTOMATION MARKET, BY ENTERPRISE, 2026-2032 (USD MILLION)
- TABLE 373 NETWORK AUTOMATION MARKET: DEGREE OF COMPETITION
- TABLE 374 NETWORK AUTOMATION MARKET: REGION FOOTPRINT
- TABLE 375 NETWORK AUTOMATION MARKET: OFFERING FOOTPRINT
- TABLE 376 NETWORK AUTOMATION MARKET: NETWORK TYPE FOOTPRINT
- TABLE 377 NETWORK AUTOMATION MARKET: DETAILED LIST OF KEY STARTUPS/SMES
- TABLE 378 NETWORK AUTOMATION MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 379 NETWORK AUTOMATION MARKET: PRODUCT LAUNCHES & ENHANCEMENTS, 2023-SEPTEMBER 2026
- TABLE 380 NETWORK AUTOMATION MARKET: DEALS, 2023-SEPTEMBER 2026
- TABLE 381 CISCO: COMPANY OVERVIEW
- TABLE 382 CISCO: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 383 CISCO: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 384 CISCO: DEALS
- TABLE 385 HPE: COMPANY OVERVIEW
- TABLE 386 HPE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 387 HPE: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 388 HPE: DEALS
- TABLE 389 IBM: COMPANY OVERVIEW
- TABLE 390 IBM: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 391 IBM: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 392 IBM: DEALS
- TABLE 393 HUAWEI: COMPANY OVERVIEW
- TABLE 394 HUAWEI: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 395 HUAWEI: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 396 HUAWEI: DEALS
- TABLE 397 NOKIA: COMPANY OVERVIEW
- TABLE 398 NOKIA: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 399 NOKIA: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 400 NOKIA: DEALS
- TABLE 401 BROADCOM: COMPANY OVERVIEW
- TABLE 402 BROADCOM: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 403 BROADCOM: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 404 BROADCOM: DEALS
- TABLE 405 ARISTA NETWORKS: COMPANY OVERVIEW
- TABLE 406 ARISTA NETWORKS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 407 ARISTA NETWORKS: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 408 ARISTA NETWORKS: DEALS
- TABLE 409 ERICSSON: COMPANY OVERVIEW
- TABLE 410 ERICSSON: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 411 ERICSSON: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 412 ERICSSON: DEALS
- TABLE 413 EXTREME NETWORKS: COMPANY OVERVIEW
- TABLE 414 EXTREME NETWORKS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 415 EXTREME NETWORKS: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 416 EXTREME NETWORKS: DEALS
- TABLE 417 FUJITSU: COMPANY OVERVIEW
- TABLE 418 FUJITSU: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 419 FUJITSU: DEALS
- TABLE 420 FACTOR ANALYSIS
List of Figures
- FIGURE 1 MARKET SEGMENTATION AND REGIONAL SCOPE
- FIGURE 2 MARKET SCENARIO
- FIGURE 3 NETWORK AUTOMATION MARKET, 2020-2032
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN NETWORK AUTOMATION MARKET, 2023-2026
- FIGURE 5 DISRUPTIONS INFLUENCING GROWTH OF NETWORK AUTOMATION MARKET
- FIGURE 6 ASIA PACIFIC TO REGISTER HIGHEST CAGR IN NETWORK AUTOMATION MARKET DURING FORECAST PERIOD
- FIGURE 7 INCREASING DEMAND FOR AUTOMATED NETWORK MANAGEMENT TO DRIVE MARKET
- FIGURE 8 SOFTWARE SEGMENT TO ACCOUNT FOR LARGER MARKET SHARE IN 2026
- FIGURE 9 ENTERPRISES SEGMENT TO ACCOUNT FOR LARGER MARKET SHARE IN 2026
- FIGURE 10 ORCHESTRATION AUTOMATION SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE IN 2026
- FIGURE 11 DATA CENTER NETWORKS SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE IN 2026
- FIGURE 12 MANUFACTURING SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE IN 2026
- FIGURE 13 DATA CENTER NETWORKS SEGMENT AND US TO ACCOUNT FOR LARGEST MARKET SHARES IN NORTH AMERICA IN 2026
- FIGURE 14 DATA CENTER NETWORKS SEGMENT AND CHINA TO ACCOUNT FOR LARGEST MARKET SHARES IN ASIA PACIFIC IN 2026
- FIGURE 15 NETWORK AUTOMATION MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 16 NETWORK AUTOMATION MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 17 NETWORK AUTOMATION MARKET: SUPPLY CHAIN ANALYSIS
- FIGURE 18 NETWORK AUTOMATION MARKET: ECOSYSTEM ANALYSIS
- FIGURE 19 INDICATIVE PRICING OF NETWORK AUTOMATION OFFERINGS, 2025
- FIGURE 20 TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
- FIGURE 21 INVESTMENT AND FUNDING SCENARIO
- FIGURE 22 LIST OF MAJOR PATENTS APPLIED AND GRANTED, 2017-2026
- FIGURE 23 NETWORK AUTOMATION MARKET DECISION-MAKING FACTORS
- FIGURE 24 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE ENTERPRISES
- FIGURE 25 KEY BUYING CRITERIA FOR TOP THREE ENTERPRISES
- FIGURE 26 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- FIGURE 27 SERVICES SEGMENT TO EXHIBIT HIGHER CAGR DURING FORECAST PERIOD
- FIGURE 28 PROFESSIONAL SERVICES SEGMENT TO RECORD HIGHER CAGR DURING FORECAST PERIOD
- FIGURE 29 DEPLOYMENT & INTEGRATION SERVICES SEGMENT TO LEAD MARKET DURING FORECAST PERIOD
- FIGURE 30 AI-DRIVEN NETWORK AUTOMATION SEGMENT TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 31 CLOUD NETWORKS SEGMENT TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 32 ENTERPRISES SEGMENT TO DOMINATE MARKET DURING FORECAST PERIOD
- FIGURE 33 HEALTHCARE SEGMENT TO GROW AT HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 34 NORTH AMERICA: MARKET SNAPSHOT
- FIGURE 35 ASIA PACIFIC: MARKET SNAPSHOT
- FIGURE 36 NETWORK AUTOMATION MARKET: REVENUE ANALYSIS OF KEY PLAYERS, 2021-2025
- FIGURE 37 SHARE OF LEADING COMPANIES IN NETWORK AUTOMATION MARKET, 2025
- FIGURE 38 BRAND/PRODUCT COMPARISON
- FIGURE 39 NETWORK AUTOMATION MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 40 NETWORK AUTOMATION MARKET: COMPANY FOOTPRINT
- FIGURE 41 NETWORK AUTOMATION MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 42 COMPANY VALUATION
- FIGURE 43 VALUATION AND FINANCIAL METRICS OF KEY NETWORK AUTOMATION PLAYERS
- FIGURE 44 CISCO: COMPANY SNAPSHOT
- FIGURE 45 HPE: COMPANY SNAPSHOT
- FIGURE 46 IBM: COMPANY SNAPSHOT
- FIGURE 47 HUAWEI: COMPANY SNAPSHOT
- FIGURE 48 NOKIA: COMPANY SNAPSHOT
- FIGURE 49 BROADCOM: COMPANY SNAPSHOT
- FIGURE 50 ARISTA NETWORKS: COMPANY SNAPSHOT
- FIGURE 51 ERICSSON: COMPANY SNAPSHOT
- FIGURE 52 EXTREME NETWORKS: COMPANY SNAPSHOT
- FIGURE 53 FUJITSU: COMPANY SNAPSHOT
- FIGURE 54 NETWORK AUTOMATION MARKET: RESEARCH DESIGN
- FIGURE 55 NETWORK AUTOMATION MARKET: TOP-DOWN AND BOTTOM-UP APPROACHES
- FIGURE 56 NETWORK AUTOMATION MARKET: BOTTOM-UP APPROACH
- FIGURE 57 MARKET SIZE ESTIMATION METHODOLOGY - APPROACH 1 (SUPPLY SIDE): REVENUE OF SOFTWARE AND SERVICES IN NETWORK AUTOMATION MARKET
- FIGURE 58 MARKET SIZE ESTIMATION METHODOLOGY - APPROACH 2 (BOTTOM-UP) (SUPPLY-SIDE): COLLECTIVE REVENUE OF SOFTWARE AND SERVICES IN NETWORK AUTOMATION MARKET
- FIGURE 59 MARKET SIZE ESTIMATION METHODOLOGY - APPROACH 3, BOTTOM-UP (SUPPLY-SIDE ANALYSIS): COLLECTIVE REVENUE FROM ALL SOFTWARE AND SERVICES IN NETWORK AUTOMATION MARKET
- FIGURE 60 NETWORK AUTOMATION MARKET: TOP-DOWN APPROACH
- FIGURE 61 NETWORK AUTOMATION MARKET: DATA TRIANGULATION

