PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2132776
PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2132776
Biosimilars Market by Drug Class (mAbs, GCSF, Insulin, Anticoagulant, rhGH, Teriparatide, GLP-1), Indication (Oncology, Autoimmune, Diabetes, Obesity), Competitive Landscape, Region - Global Forecast to 2036
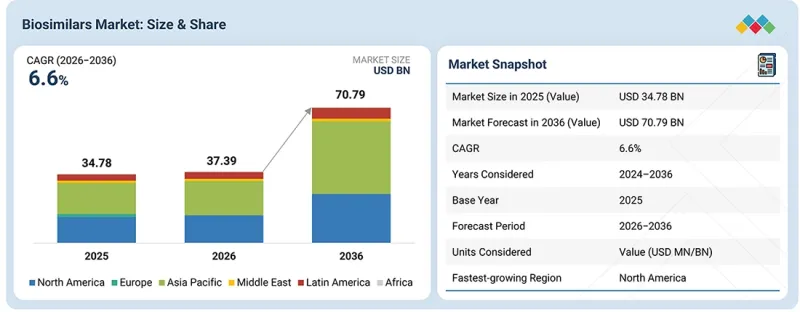
The biosimilars market is projected to reach USD 70.79 billion by 2036 from an estimated USD 37.39 billion in 2026, registering a CAGR of 6.6% during the forecast period. Market growth is primarily driven by increasing awareness and education regarding the safety, efficacy, and interchangeability of biosimilars, resulting in increased acceptance among healthcare providers and patients.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Drug Class and Indication |
| Regions covered | North America, Europe, Asia Pacific, Latin America, Middle East, and Africa |
In parallel, favorable insurance coverage and reimbursement policies across public and private healthcare systems are supporting broader adoption by improving the affordability and accessibility of biosimilar therapies. The growing need to reduce healthcare expenditure and expand patient access to cost-effective biologic treatments is further accelerating demand.
However, the market's expansion is constrained by the increasing complexity of biosimilar development and manufacturing, which requires sophisticated technologies, stringent quality controls, and substantial investment. In addition, the growing number of biosimilars competing within the same therapeutic categories is intensifying price competition and margin pressure, particularly in mature markets. These factors are expected to moderate market growth over the forecast period despite continued expansion in biosimilar utilization and market penetration.
The monoclonal antibodies segment is expected to witness the highest growth rate during the study period.
By drug class, the monoclonal antibodies (mAbs) segment is expected to register the highest CAGR during the forecast period, supported by the extensive use of biologics such as Infliximab, Rituximab, Adalimumab, Trastuzumab, Pembrolizumab, Dupilumab, Ustekinumab, Risankizumab, Daratumumab, Nivolumab, and other mAbs across oncology, autoimmune diseases, chronic inflammatory conditions, and selected infectious diseases. The growing prevalence of cancer and autoimmune disorders, combined with an expanding eligible patient population and increasing utilization of biologic therapies, is expected to strengthen demand for mAb biosimilars. In addition, the anticipated loss of patent and regulatory exclusivity for several high-value reference biologics will create opportunities for biosimilar manufacturers to enter large and established therapeutic markets.
mAbs are widely used in the management of cancer, rheumatoid arthritis, psoriasis, inflammatory bowel disease, and other chronic and potentially life-threatening conditions, with demand further supported by an aging population and the increasing burden of chronic diseases. The availability of biosimilar alternatives can reduce treatment costs, expand patient access, and encourage greater utilization of biologic therapies, particularly in cost-sensitive healthcare systems. Over the next decade, the expected loss of exclusivity of multiple high-value mAbs is likely to attract additional pharmaceutical and biotechnology companies, intensifying competition and expanding the global biosimilar landscape. The broad therapeutic applicability and substantial commercial value of mAb reference products, particularly across oncology and immunology, are therefore expected to make monoclonal antibody biosimilars a major contributor to market growth through 2036.
The US is expected to register the highest CAGR during the forecast period.
By country, the US is expected to register the highest CAGR in the global biosimilars market between 2026 and 2036, supported by the growing number of biosimilar launches, loss of exclusivity of high-value biologics, increasing payer acceptance, and continued development of the regulatory framework under the Biologics Price Competition and Innovation Act (BPCIA). The US market is entering a period of significant biosimilar expansion as additional reference biologics lose patent and regulatory exclusivity, creating opportunities across high-value therapeutic areas such as oncology, immunology, ophthalmology, and endocrinology.
The commercialization of biosimilars to major biologics, including Stelara (ustekinumab), Eylea (aflibercept), and other high-value reference products, is expected to substantially expand the addressable market during the forecast period. The US has already demonstrated strong competitive activity following the introduction of biosimilars to Humira (adalimumab) beginning in 2023, with multiple manufacturers, including Amgen, Boehringer Ingelheim, and Sandoz, entering the market. Increasing competition among manufacturers has contributed to lower prices and broader payer and formulary access, while interchangeability designations for selected biosimilars can further facilitate substitution and adoption.
In addition, growing awareness among physicians, patients, payers, and healthcare providers, together with federal initiatives aimed at improving affordability and reducing healthcare expenditure, is expected to support continued biosimilar uptake. As the number of interchangeable biosimilars increases and stakeholders gain greater experience with switching between reference biologics and biosimilars, adoption is expected to accelerate. These factors, combined with the large US biologics market, high healthcare expenditure, substantial eligible patient population, and continued influx of biosimilar competitors, are expected to position the US as one of the fastest-growing and most commercially attractive markets for biosimilars through 2036.
The primary interviews conducted for this report can be categorized as follows:
- By Respondent: Supply Side (70%) and Demand Side (30%)
- By Designation: Managers (45%), CXOs & Directors (30%), and Executives (25%)
- By Region: North America (40%), Europe (25%), Asia Pacific (20%), Latin America (10%), and Middle East & Africa (5%)
List of Key Companies Profiled in the Report:
Key players in the biosimilars market include Sandoz Group AG (Switzerland), Pfizer Inc. (US), Amgen Inc. (US), Celltrion Inc. (South Korea), Biocon Limited (India), Dr. Reddy's Laboratories Ltd. (India), Eli Lilly and Company (US), Teva Pharmaceutical Industries Ltd. (Israel), Fresenius Kabi AG (Germany), Stada Arzneimittel AG (Germany), Boehringer Ingelheim International GmbH (Germany), Samsung Bioepis Co., Ltd. (South Korea), Amneal Pharmaceuticals, Inc. (US), Bio-Thera Solutions, Ltd. (China), Aprogen Inc. (South Korea), Shanghai Henlius Biotech, Inc. (China), and Alvotech (Iceland).
Research Coverage:
This research report categorizes the biosimilars market by drug class (Monoclonal Antibodies, Granulocyte Colony-Stimulating Factor (G-CSF), Insulin, Erythropoietin, Recombinant Human Growth Hormone, Etanercept, Follitropin, Teriparatide, Interferons, Anticoagulants, Aflibercept, GLP-1 Agonist, and Other Drug Classes), indication (Oncology, Inflammatory & Autoimmune Diseases, Chronic Diseases, Blood Disorders, Growth Hormone Deficiencies, Infectious Diseases, Type II Diabetes, Obesity, and Other Indications), and region (North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa).
The scope of the report covers detailed information regarding the major factors, such as drivers, restraints, challenges, and opportunities, influencing the growth of the biosimilars market. A detailed analysis of key industry players has been conducted to provide insights into their business overviews, products, solutions, key strategies, collaborations, partnerships, and agreements.
Key Benefits of Buying the Report:
The report will help market leaders and new entrants by providing the closest approximations of revenue for the overall biosimilars market and its subsegments. It will also help stakeholders better understand the competitive landscape, gain more insights into better positioning of their businesses, and develop suitable go-to-market strategies. This report will enable stakeholders to understand the market's pulse and provide information on key drivers, restraints, opportunities, and challenges.
The report provides insights into the following pointers:
- Analysis of key drivers (Patent expiry of blockbuster biologics, Healthcare cost-containment & favorable reimbursement policies, Increasing physician & patient acceptance of biosimilars, Regulatory harmonization & faster biosimilar approval pathways), restraints (Price erosion due to intense biosimilar competition, High development & manufacturing costs, Regulatory complexity across emerging markets, Limited physician confidence in certain regions), opportunities (Next-wave patent expiries of high-value biologics, Expansion into emerging markets, Interchangeability & automatic pharmacy substitution, Government incentives for domestic biologics manufacturing), and challenges (Intensifying competition among biosimilar manufacturers, Originator lifecycle management strategies, Manufacturing capacity & supply chain complexity).
- Product Development/Innovation: Detailed insights into upcoming technologies and research & development activities in the biosimilars market.
- Market Development: Comprehensive information about lucrative markets. The report analyses the market across varied regions.
- Market Diversification: Exhaustive information about untapped geographies, recent developments, and investments in the biosimilars market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and product offerings of leading players. A detailed analysis of the key industry players has been carried out to provide insights into their key strategies, product launches/approvals, acquisitions, partnerships, agreements, collaborations, other recent developments, investments & funding activities, brand/product comparative analysis, and vendor valuation & financial metrics of the biosimilars market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 INCLUSIONS AND EXCLUSIONS
- 1.4 STUDY SCOPE
- 1.4.1 SEGMENTS CONSIDERED
- 1.4.2 YEARS CONSIDERED
- 1.4.3 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN BIOSIMILARS MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 BIOSIMILARS MARKET OVERVIEW
- 3.2 NORTH AMERICA: BIOSIMILARS MARKET, BY DRUG CLASS
- 3.3 BIOSIMILARS MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
- 3.4 BIOSIMILARS MARKET SHARE, BY INDICATION, 2026 VS. 2036 (%)
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Patent Expiry of Blockbuster Biologics
- 4.2.1.2 Healthcare Cost-Containment and Favorable Reimbursement Policies
- 4.2.1.3 Increasing Physician and Patient Acceptance of Biosimilars
- 4.2.1.4 Regulatory Harmonization and Faster Biosimilar Approval Pathways
- 4.2.2 RESTRAINTS
- 4.2.2.1 Price Erosion Due to Intense Biosimilar Competition
- 4.2.2.2 High Development and Manufacturing Costs
- 4.2.2.3 Regulatory Complexity Across Emerging Markets
- 4.2.2.4 Limited Physician Confidence in Certain Regions
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Next-Wave Patent Expiries of High-Value Biologics
- 4.2.3.2 Expansion into Emerging Markets
- 4.2.3.3 Interchangeability & Automatic Pharmacy Substitution
- 4.2.3.4 Government Incentives for Domestic Biologics Manufacturing
- 4.2.4 CHALLENGES
- 4.2.4.1 Intensifying Competition Among Biosimilar Manufacturers
- 4.2.4.2 Originator Lifecycle Management Strategies
- 4.2.4.3 Manufacturing Capacity & Supply Chain Complexity
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS & WHITE SPACES
- 4.4 INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF BUYERS
- 5.1.4 BARGAINING POWER OF SUPPLIERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL BIOSIMILARS MARKET
- 5.2.4 TRENDS IN HEALTHCARE EXPENDITURE
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 SUPPLY CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.5.1 EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE TREND OF BIOSIMILAR PRODUCTS, BY KEY PLAYER, 2023-2025
- 5.6.2 AVERAGE SELLING PRICE TREND OF BIOSIMILAR PRODUCTS, BY REGION, 2023-2025
- 5.7 KEY CONFERENCES & EVENTS
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.9 INVESTMENT/FUNDING ACTIVITY
- 5.10 CASE STUDY ANALYSIS
- 5.11 IMPACT OF 2025 US TARIFF ON BIOSIMILARS MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRY/REGION
- 5.11.4.1 North America
- 5.11.4.1.1 US
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.4.1 North America
- 5.11.5 IMPACT ON UPSTREAM MANUFACTURING INDUSTRIES
- 5.12 PIPELINE ANALYSIS
- 5.12.1 BIOSIMILAR PRODUCTS IN CLINICAL PIPELINE
- 5.13 LIST OF KEY BIOLOGICS TO GO OFF-PATENT
- 5.14 LIST OF BIOSIMILARS MANUFACTURING FACILITIES, BY KEY PLAYER
- 5.15 MANUFACTURING FACILITY EXPANSION
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGIES
- 6.1.1.1 Advanced bioprocessing & manufacturing technologies
- 6.1.1.2 Analytical & characterization techniques
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 AI & ML
- 6.1.2.2 Lab automation & robotics
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 Microbial fermentation
- 6.1.3.2 3D bioprinting & high-density cell culture
- 6.1.1 KEY TECHNOLOGIES
- 6.2 FUTURE APPLICATIONS
- 6.3 IMPACT OF AI/GEN AI ON BIOSIMILARS MARKET
- 6.3.1 TOP USE CASES AND MARKET POTENTIAL
- 6.3.1.1 Accelerated Drug Development and Reduced Costs
- 6.3.1.2 Enhanced Manufacturing and Quality Control
- 6.3.1.3 Smarter Commercialization and Regulatory Strategy
- 6.3.2 CASE STUDIES OF AI IMPLEMENTATION IN BIOSIMILARS MARKET
- 6.3.3 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.3.4 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN BIOSIMILARS MARKET
- 6.3.1 TOP USE CASES AND MARKET POTENTIAL
- 6.4 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 REGULATORY FRAMEWORK
- 7.2 REIMBURSEMENT SCENARIO ANALYSIS
- 7.2.1 INDUSTRY STANDARDS
- 7.3 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, & ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 KEY BUYING CRITERIA, BY END USER
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
9 BIOSIMILARS MARKET, BY DRUG CLASS
- 9.1 INTRODUCTION
- 9.2 MONOCLONAL ANTIBODIES
- 9.2.1 RITUXIMAB
- 9.2.1.1 Increasing cancer and autoimmune disease burden, coupled with expanding biosimilar competition, to support market growth
- 9.2.2 INFLIXIMAB
- 9.2.2.1 Loss of patent exclusivity to fuel adoption of Infliximab for treating autoimmune diseases
- 9.2.3 ADALIMUMAB
- 9.2.3.1 Cost-effectiveness and improved patient access to fuel segment growth
- 9.2.4 TRASTUZUMAB
- 9.2.4.1 Rising incidence of breast cancer to support market growth
- 9.2.5 PEMBROLIZUMAB
- 9.2.5.1 High-value oncology opportunity driven by Keytruda's patent expiry and strong biosimilar pipeline
- 9.2.6 DUPILUMAB
- 9.2.6.1 Broad indication base and blockbuster sales make dupilumab high-value next-wave biosimilar opportunity
- 9.2.7 USTEKINUMAB
- 9.2.7.1 Highly competitive biosimilars market, with multiple products commercialized across major regions
- 9.2.8 RISANKIZUMAB
- 9.2.8.1 Rapidly growing Skyrizi sales and broad inflammatory-disease footprint make risankizumab major future biosimilar opportunity
- 9.2.9 DARATUMUMAB
- 9.2.9.1 High-value oncology franchise and expanding multiple myeloma use make daratumumab major future biosimilar opportunity
- 9.2.10 NIVOLUMAB
- 9.2.10.1 Large oncology revenue base and broad tumor coverage make nivolumab important future checkpoint
- 9.2.11 OTHER MONOCLONAL ANTIBODIES
- 9.2.1 RITUXIMAB
- 9.3 GRANULOCYTE COLONY-STIMULATING FACTOR
- 9.3.1 MATURE COMMERCIALIZATION AND ESTABLISHED BIOSIMILAR ADOPTION MAKE G-CSF HIGH-VOLUME, PRICE-COMPETITIVE BIOSIMILAR SEGMENT
- 9.4 INSULIN
- 9.4.1 HIGH PREVALENCE OF DIABETES TO BOOST MARKET GROWTH
- 9.5 ERYTHROPOIETIN
- 9.5.1 RISING INCIDENCE OF BLOOD DISORDERS TO AUGMENT MARKET GROWTH
- 9.6 RECOMBINANT HUMAN GROWTH HORMONE
- 9.6.1 RISING INCIDENCE OF GROWTH DEFICIENCY DISORDERS IN ADULTS AND CHILDREN TO PROPEL MARKET GROWTH
- 9.7 ETANERCEPT
- 9.7.1 APPROVAL AND COMMERCIALIZATION OF ETANERCEPT BIOSIMILARS TO ACCELERATE MARKET EXPANSION
- 9.8 FOLLITROPIN
- 9.8.1 POPULARITY OF FOLLITROPIN IN INFERTILITY TREATMENT TO SPUR MARKET GROWTH
- 9.9 TERIPARATIDE
- 9.9.1 INCREASING INCIDENCE OF OSTEOPOROSIS TO BOOST DEMAND
- 9.10 INTERFERONS
- 9.10.1 GROWING PREVALENCE OF INFECTIOUS DISEASES TO SUPPORT MARKET GROWTH
- 9.11 ANTICOAGULANTS
- 9.11.1 RISING PREVALENCE OF CARDIOVASCULAR DISEASES TO FUEL MARKET GROWTH
- 9.12 AFLIBERCEPT
- 9.12.1 LARGE OPHTHALMOLOGY MARKET AND RAPID BIOSIMILAR UPTAKE ARE MAKING AFLIBERCEPT KEY COMMERCIAL BIOSIMILAR SEGMENT
- 9.13 GLP-1 AGONIST
- 9.13.1 HIGH PREVALENCE OF DIABETES AND OBESITY TO AID MARKET GROWTH
- 9.14 OTHER DRUG CLASSES
10 BIOSIMILARS MARKET, BY INDICATION
- 10.1 INTRODUCTION
- 10.2 ONCOLOGY
- 10.2.1 INCREASED APPROVALS AND LAUNCH OF BIOSIMILARS FOR CANCER TO DRIVE MARKET
- 10.3 INFLAMMATORY & AUTOIMMUNE DISEASES
- 10.3.1 CHANGES IN LIFESTYLES AND ENVIRONMENTAL CONDITIONS LEAD TO INCREASING INCIDENCES OF INFLAMMATORY AND AUTOIMMUNE DISEASES
- 10.4 CHRONIC DISEASES
- 10.4.1 HIGH BURDEN OF CVD WORLDWIDE TO DRIVE MARKET GROWTH
- 10.5 BLOOD DISORDERS
- 10.5.1 INCREASING INCIDENCE OF BLOOD DISORDERS TO BOOST BIOSIMILAR DEMAND
- 10.6 GROWTH HORMONE DEFICIENCY
- 10.6.1 RISING USE OF BIOSIMILARS FOR TREATMENT OF GHD
- 10.7 INFECTIOUS DISEASES
- 10.7.1 BIOSIMILARS MARKET FOR INFECTIOUS DISEASES TO GROW RAPIDLY IN ASIA PACIFIC
- 10.8 TYPE II DIABETES
- 10.8.1 RISING PREVALENCE OF DIABETES PROPELS MARKET GROWTH
- 10.9 OBESITY
- 10.9.1 DEVELOPMENT OF GLP-1 ANTAGONIST BIOSIMILARS PROPELS MARKET GROWTH
- 10.10 OTHER INDICATIONS
11 BIOSIMILARS MARKET, BY REGION
- 11.1 INTRODUCTION
- 11.2 NORTH AMERICA
- 11.2.1 US
- 11.2.1.1 US to dominate North American biosimilars market
- 11.2.2 CANADA
- 11.2.2.1 Favorable government initiatives to support market
- 11.2.1 US
- 11.3 EUROPE
- 11.3.1 GERMANY
- 11.3.1.1 Germany to dominate European biosimilars market
- 11.3.2 UK
- 11.3.2.1 Increasing adoption of biosimilars to boost market
- 11.3.3 FRANCE
- 11.3.3.1 Rising geriatric population to drive market growth
- 11.3.4 ITALY
- 11.3.4.1 Favorable government policies to propel adoption of biosimilars
- 11.3.5 SPAIN
- 11.3.5.1 Favorable patient incentives to promote biosimilar use
- 11.3.6 REST OF EUROPE
- 11.3.1 GERMANY
- 11.4 ASIA PACIFIC
- 11.4.1 CHINA
- 11.4.1.1 China to register fastest growth in Asia Pacific market
- 11.4.2 JAPAN
- 11.4.2.1 Large geriatric population to drive market growth
- 11.4.3 INDIA
- 11.4.3.1 Increasing biosimilar launches and approvals to support market growth
- 11.4.4 SOUTH KOREA
- 11.4.4.1 Favorable government initiatives to support growth
- 11.4.5 AUSTRALIA
- 11.4.5.1 Favorable regulatory changes and increasing disease incidence to propel growth
- 11.4.6 REST OF ASIA PACIFIC
- 11.4.1 CHINA
- 11.5 LATIN AMERICA
- 11.5.1 BRAZIL
- 11.5.1.1 Increased government investments in pharmaceutical R&D to drive market
- 11.5.2 MEXICO
- 11.5.2.1 Rising demand for chronic disease treatment to support market growth
- 11.5.3 REST OF LATIN AMERICA
- 11.5.1 BRAZIL
- 11.6 MIDDLE EAST
- 11.6.1 GCC COUNTRIES
- 11.6.1.1 Saudi Arabia
- 11.6.1.1.1 Centralized procurement, localization policies, and increasingly biosimilar-supportive regulatory framework to accelerate biosimilar adoption in Saudi Arabia
- 11.6.1.2 UAE
- 11.6.1.2.1 Rapid expansion of advanced healthcare infrastructure combined with payer pressure to reduce biologic treatment costs is strengthening commercial case for biosimilars in UAE
- 11.6.1.3 Rest of GCC
- 11.6.1.1 Saudi Arabia
- 11.6.2 REST OF MIDDLE EAST
- 11.6.1 GCC COUNTRIES
- 11.7 AFRICA
12 COMPETITIVE LANDSCAPE
- 12.1 OVERVIEW
- 12.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 12.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN BIOSIMILARS MARKET, 2024-2026
- 12.3 REVENUE ANALYSIS, 2023-2025
- 12.4 MARKET SHARE ANALYSIS, 2025
- 12.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 12.5.1 STARS
- 12.5.2 EMERGING LEADERS
- 12.5.3 PERVASIVE PLAYERS
- 12.5.4 PARTICIPANTS
- 12.6 COMPETITIVE BENCHMARKING OF TOP PLAYERS
- 12.6.1 COMPANY FOOTPRINT
- 12.6.2 REGION FOOTPRINT
- 12.6.3 DRUG CLASS FOOTPRINT
- 12.6.4 INDICATION FOOTPRINT
- 12.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 12.7.1 PROGRESSIVE COMPANIES
- 12.7.2 RESPONSIVE COMPANIES
- 12.7.3 DYNAMIC COMPANIES
- 12.7.4 STARTING BLOCKS
- 12.8 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 12.9 VALUATION AND FINANCIAL METRICS OF BIOSIMILAR VENDORS
- 12.9.1 FINANCIAL METRICS
- 12.9.2 COMPANY VALUATION
- 12.10 BRAND/PRODUCT COMPARISON
- 12.11 COMPETITIVE SCENARIO
- 12.11.1 PRODUCT APPROVALS
- 12.11.2 DEALS
- 12.11.3 EXPANSIONS
13 COMPANY PROFILES
- 13.1 KEY PLAYERS
- 13.1.1 SANDOZ GROUP AG
- 13.1.1.1 Products offered
- 13.1.1.2 Products in pipeline
- 13.1.1.3 Recent developments
- 13.1.1.3.1 Product launches and approvals
- 13.1.1.3.2 Deals
- 13.1.1.3.3 Expansions
- 13.1.1.3.4 Other developments
- 13.1.1.4 MnM view
- 13.1.1.4.1 Key strengths
- 13.1.1.4.2 Strategic choices
- 13.1.1.4.3 Weaknesses & competitive threats
- 13.1.2 AMGEN INC.
- 13.1.2.1 Products offered
- 13.1.2.2 Products in pipeline
- 13.1.2.3 Recent developments
- 13.1.2.3.1 Product launches and approvals
- 13.1.2.3.2 Deals
- 13.1.2.3.3 Expansions
- 13.1.2.4 MnM view
- 13.1.2.4.1 Key strengths
- 13.1.2.4.2 Strategic choices
- 13.1.2.4.3 Weaknesses & competitive threats
- 13.1.3 CELLTRION INC.
- 13.1.3.1 Products offered
- 13.1.3.2 Recent developments
- 13.1.3.2.1 Product launches and approvals
- 13.1.3.2.2 Deals
- 13.1.3.2.3 Expansions
- 13.1.3.3 MnM view
- 13.1.3.3.1 Key strengths
- 13.1.3.3.2 Strategic choices
- 13.1.3.3.3 Weaknesses & competitive threats
- 13.1.4 PFIZER INC.
- 13.1.4.1 Business overview
- 13.1.4.2 Products offered
- 13.1.4.3 Recent developments
- 13.1.4.3.1 Product approvals
- 13.1.4.3.2 Deals
- 13.1.4.4 MnM view
- 13.1.4.4.1 Key strengths
- 13.1.4.4.2 Strategic choices
- 13.1.4.4.3 Weaknesses & competitive threats
- 13.1.5 BIOCON
- 13.1.5.1 Business overview
- 13.1.5.2 Products offered
- 13.1.5.3 Recent developments
- 13.1.5.3.1 Product approvals
- 13.1.5.3.2 Deals
- 13.1.5.3.3 Other developments
- 13.1.5.4 MnM view
- 13.1.5.4.1 Key strengths
- 13.1.5.4.2 Strategic choices
- 13.1.5.4.3 Weaknesses & competitive threats
- 13.1.6 DR. REDDY'S LABORATORIES LTD.
- 13.1.6.1 Products offered
- 13.1.6.2 Recent developments
- 13.1.6.2.1 Product launches
- 13.1.6.2.2 Deals
- 13.1.6.2.3 Other developments
- 13.1.7 ELI LILLY AND COMPANY
- 13.1.7.1 Products offered
- 13.1.7.2 Recent developments
- 13.1.7.2.1 Product launches
- 13.1.7.2.2 Deals
- 13.1.7.2.3 Expansions
- 13.1.8 TEVA PHARMACEUTICAL INDUSTRIES LTD.
- 13.1.8.1 Products offered
- 13.1.8.2 Recent developments
- 13.1.8.2.1 Product launches and approvals
- 13.1.8.2.2 Deals
- 13.1.8.2.3 Other developments
- 13.1.9 FRESENIUS KABI AG
- 13.1.9.1 Products offered
- 13.1.9.2 Recent developments
- 13.1.9.2.1 Product Launches and Approvals
- 13.1.9.2.2 Deals
- 13.1.9.2.3 Other developments
- 13.1.10 STADA ARZNEIMITTEL AG
- 13.1.10.1 Products offered
- 13.1.10.2 Recent developments
- 13.1.10.2.1 Product launches/Approvals
- 13.1.10.2.2 Deals
- 13.1.10.2.3 Expansions
- 13.1.10.2.4 Other developments
- 13.1.11 BOEHRINGER INGELHEIM INTERNATIONAL GMBH
- 13.1.11.1 Products offered
- 13.1.11.2 Recent developments
- 13.1.11.2.1 Product approvals
- 13.1.11.2.2 Deals
- 13.1.11.2.3 Expansions
- 13.1.12 SAMSUNG BIOEPIS HOLDINGS CO., LTD.
- 13.1.12.1 Business overview
- 13.1.12.2 Products offered
- 13.1.12.3 Recent developments
- 13.1.12.3.1 Product Launches and Approvals
- 13.1.12.3.2 Deals
- 13.1.13 AMNEAL PHARMACEUTICALS LLC
- 13.1.13.1 Business overview
- 13.1.13.2 Products offered
- 13.1.13.3 Recent developments
- 13.1.13.3.1 Product approvals
- 13.1.13.3.2 Deals
- 13.1.13.3.3 Other developments
- 13.1.14 BIO THERA SOLUTIONS
- 13.1.14.1 Business overview
- 13.1.14.2 Products offered
- 13.1.14.3 Recent developments
- 13.1.14.3.1 Product approvals
- 13.1.14.3.2 Deals
- 13.1.15 APROGEN
- 13.1.15.1 Business overview
- 13.1.15.2 Products offered
- 13.1.15.3 Recent developments
- 13.1.15.3.1 Product approvals
- 13.1.15.4 Products in pipeline
- 13.1.16 SHANGHAI HENLIUS BIOTECH, INC.
- 13.1.16.1 Business overview
- 13.1.16.2 Products offered
- 13.1.16.3 Products in pipeline
- 13.1.16.4 Recent developments
- 13.1.16.4.1 Product approvals
- 13.1.16.4.2 Deals
- 13.1.16.4.3 Other developments
- 13.1.17 ALVOTECH
- 13.1.17.1 Business overview
- 13.1.17.2 Products offered
- 13.1.17.3 Products in pipeline
- 13.1.17.4 Recent developments
- 13.1.17.4.1 Product approvals
- 13.1.17.4.2 Deals
- 13.1.1 SANDOZ GROUP AG
- 13.2 OTHER PLAYERS
- 13.2.1 AMEGA BIOTECH
- 13.2.2 BIOCAD
- 13.2.3 PROBIOMED S.A. DE C.V.
- 13.2.4 FUJIFILM KYOWA KIRIN BIOLOGICS CO., LTD.
- 13.2.5 POLPHARMA BIOLOGICS GROUP
- 13.2.6 NEUCLONE
- 13.2.7 XENTRIA
- 13.2.8 NANOGEN PHARMACEUTICAL BIOTECHNOLOGY JSC
- 13.2.9 SYNERMORE BIOLOGICS (SUZHOU) CO., LTD.
- 13.2.10 CURATEQ BIOLOGICS PVT. LTD.
- 13.2.11 XBRANE BIOPHARMA AB
- 13.2.12 FORMYCON AG
- 13.2.13 SAM CHUN DANG PHARM. CO., LTD.
- 13.2.14 PRESTIGE BIOPHARMA
- 13.2.15 BIOEQ AG
14 RESEARCH METHODOLOGY
- 14.1 RESEARCH DATA
- 14.1.1 SECONDARY DATA
- 14.1.1.1 Key data from secondary sources
- 14.1.2 PRIMARY DATA
- 14.1.1 SECONDARY DATA
- 14.2 MARKET ESTIMATION METHODOLOGY
- 14.2.1 GLOBAL MARKET ESTIMATION
- 14.2.2 INSIGHTS OF PRIMARY EXPERTS
- 14.2.3 SEGMENTAL MARKET SIZE ESTIMATION
- 14.3 MARKET GROWTH RATE PROJECTIONS
- 14.4 MARKET BREAKDOWN AND DATA TRIANGULATION
- 14.5 RESEARCH ASSUMPTIONS
- 14.6 RESEARCH LIMITATIONS
- 14.7 RISK ANALYSIS
15 APPENDIX
- 15.1 DISCUSSION GUIDE
- 15.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 15.3 CUSTOMIZATION OPTIONS
- 15.4 RELATED REPORTS
- 15.5 AUTHOR DETAILS
List of Tables
- TABLE 1 BIOSIMILARS MARKET: INCLUSIONS AND EXCLUSIONS
- TABLE 2 BIOSIMILARS MARKET: IMPACT ANALYSIS
- TABLE 3 BIOPHARMACEUTICAL CONTRACT MANUFACTURING MARKET, BY REGION, 2023-2030 (USD MILLION)
- TABLE 4 BIOSIMILARS MARKET: PORTER'S FIVE FORCES ANALYSIS
- TABLE 5 HEALTH EXPENDITURE AND FINANCING, 2015-2024 (IN PERCENTAGE OF GDP)
- TABLE 6 BIOSIMILARS MARKET: ROLE IN ECOSYSTEM
- TABLE 7 AVERAGE SELLING PRICE TREND OF BIOSIMILAR PRODUCTS, BY KEY PLAYER, 2023-2025 (USD)
- TABLE 8 AVERAGE SELLING PRICE TREND OF BIOSIMILAR PRODUCTS, BY REGION, 2023-2025 (USD)
- TABLE 9 BIOSIMILARS MARKET: KEY CONFERENCES & EVENTS, 2026-2027
- TABLE 10 PORTFOLIO SCALE & COMMERCIALIZATION
- TABLE 11 PAYER ACCESS & MARKET PENETRATION
- TABLE 12 PRODUCT DIFFERENTIATION & INTERCHANGEABILITY
- TABLE 13 US ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 14 BIOSIMILARS MARKET: PRODUCTS IN CLINICAL PIPELINE
- TABLE 15 BIOSIMILARS MARKET: LIST OF KEY BIOLOGICS TO GO OFF-PATENT, 2026-2036
- TABLE 16 BIOSIMILARS MARKET: LIST OF BIOSIMILARS MANUFACTURING FACILITIES (IN-HOUSE) BY KEY PLAYER
- TABLE 17 BIOSIMILARS MARKET: LIST OF KEY MANUFACTURING FACILITY EXPANSION
- TABLE 18 KEY COMPANIES TECHNOLOGY/PRODUCT ROADMAP - BIOSIMILARS MARKET
- TABLE 19 CASE STUDIES OF AI IMPLEMENTATION IN BIOSIMILARS MARKET
- TABLE 20 CLIENT'S READINESS TO ADOPT GENERATIVE AI IN BIOSIMILARS MARKET
- TABLE 21 KEY SUCCESS STORIES WITH RESPECT OT REAL WORLD APPLICATION IN BIOSIMILARS MARKET
- TABLE 22 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 23 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 24 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 25 REST OF THE WORLD: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 26 BIOSIMILARS MARKET: COUNTRY/REGION-WISE REGULATORY FRAMEWORK
- TABLE 27 BIOSIMILARS MARKET: COUNTRY/REGION-WISE REIMBURSEMENT FRAMEWORK
- TABLE 28 US: REIMBURSEMENT SCENARIO FOR RECENTLY LAUNCHED BIOSIMILARS, 2025-2026
- TABLE 29 US: REIMBURSEMENT CODES FOR BIOSIMILAR PRODUCTS
- TABLE 30 EUROPE: REIMBURSEMENT SCENARIO FOR RECENTLY LAUNCHED BIOSIMILARS, 2025-2026
- TABLE 31 KEY INDUSTRY STANDARDS FOR BIOSIMILARS MARKET
- TABLE 32 INFLUENCE OF KEY STAKEHOLDERS ON BUYING PROCESS, BY DRUG CLASS (%)
- TABLE 33 KEY BUYING CRITERIA, BY END USER
- TABLE 34 UNMET NEEDS ACROSS DIFFERENT END USERS IN BIOSIMILARS MARKET
- TABLE 35 BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 36 BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 37 BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY REGION, 2024-2036 (USD MILLION)
- TABLE 38 NORTH AMERICA: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 39 EUROPE: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 40 ASIA PACIFIC: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 41 LATIN AMERICA: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 42 MIDDLE EAST: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY REGION, 2024-2036 (USD MILLION)
- TABLE 43 GCC COUNTRIES: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 44 RITUXIMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 45 NORTH AMERICA: RITUXIMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 46 EUROPE: RITUXIMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 47 ASIA PACIFIC: RITUXIMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 48 LATIN AMERICA: RITUXIMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 49 MIDDLE EAST: RITUXIMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 50 GCC COUNTRIES: RITUXIMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 51 INFLIXIMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 52 NORTH AMERICA: INFLIXIMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 53 EUROPE: INFLIXIMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 54 ASIA PACIFIC: INFLIXIMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 55 LATIN AMERICA: INFLIXIMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 56 MIDDLE EAST: INFLIXIMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 57 GCC COUNTRIES: INFLIXIMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 58 ADALIMUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 59 NORTH AMERICA: ADALIMUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 60 EUROPE: ADALIMUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 61 ASIA PACIFIC: ADALIMUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 62 LATIN AMERICA: ADALIMUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 63 MIDDLE EAST: ADALIMUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 64 GCC COUNTRIES: ADALIMUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 65 TRASTUZUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 66 NORTH AMERICA: TRASTUZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 67 EUROPE: TRASTUZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 68 ASIA PACIFIC: TRASTUZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 69 LATIN AMERICA: TRASTUZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 70 MIDDLE EAST: TRASTUZUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 71 GCC COUNTRIES: TRASTUZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 72 PEMBROLIZUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 73 NORTH AMERICA: PEMBROLIZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 74 EUROPE: PEMBROLIZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 75 ASIA PACIFIC: PEMBROLIZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 76 LATIN AMERICA: PEMBROLIZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 77 MIDDLE EAST: PEMBROLIZUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 78 GCC COUNTRIES: PEMBROLIZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 79 DUPILUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 80 NORTH AMERICA: DUPILUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 81 EUROPE: DUPILUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 82 ASIA PACIFIC: DUPILUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 83 LATIN AMERICA: DUPILUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 84 MIDDLE EAST: DUPILUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 85 GCC COUNTRIES: DUPILUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 86 USTEKINUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 87 NORTH AMERICA: USTEKINUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 88 EUROPE: USTEKINUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 89 ASIA PACIFIC: USTEKINUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 90 LATIN AMERICA: USTEKINUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 91 MIDDLE EAST: USTEKINUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 92 GCC COUNTRIES: USTEKINUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 93 RISANKIZUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 94 NORTH AMERICA: RISANKIZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 95 EUROPE: RISANKIZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 96 ASIA PACIFIC: RISANKIZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 97 LATIN AMERICA: RISANKIZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 98 MIDDLE EAST: RISANKIZUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 99 GCC COUNTRIES: RISANKIZUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 100 DARATUMUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 101 NORTH AMERICA: DARATUMUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 102 EUROPE: DARATUMUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 103 ASIA PACIFIC: DARATUMUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 104 LATIN AMERICA: DARATUMUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 105 MIDDLE EAST: DARATUMUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 106 GCC COUNTRIES: DARATUMUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 107 NIVOLUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 108 NORTH AMERICA: NIVOLUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 109 EUROPE: NIVOLUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 110 ASIA PACIFIC: NIVOLUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 111 LATIN AMERICA: NIVOLUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 112 MIDDLE EAST: NIVOLUMAB MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 113 GCC COUNTRIES: NIVOLUMAB MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 114 OTHER MONOCLONAL ANTIBODIES MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 115 NORTH AMERICA: OTHER MONOCLONAL ANTIBODIES MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 116 EUROPE: OTHER MONOCLONAL ANTIBODIES MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 117 ASIA PACIFIC: OTHER MONOCLONAL ANTIBODIES MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 118 LATIN AMERICA: OTHER MONOCLONAL ANTIBODIES MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 119 MIDDLE EAST: OTHER MONOCLONAL ANTIBODIES MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 120 GCC COUNTRIES: OTHER MONOCLONAL ANTIBODIES MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 121 LIST OF APPROVED BIOSIMILARS FOR GRANULOCYTE COLONY-STIMULATING FACTOR (G-CSF)
- TABLE 122 BIOSIMILARS MARKET FOR GRANULOCYTE COLONY-STIMULATING FACTOR, BY REGION, 2024-2036 (USD MILLION)
- TABLE 123 NORTH AMERICA: BIOSIMILARS MARKET FOR GRANULOCYTE COLONY-STIMULATING FACTOR, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 124 EUROPE: BIOSIMILARS MARKET FOR GRANULOCYTE COLONY-STIMULATING FACTOR, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 125 ASIA PACIFIC: BIOSIMILARS MARKET FOR GRANULOCYTE COLONY-STIMULATING FACTOR, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 126 LATIN AMERICA: BIOSIMILARS MARKET FOR GRANULOCYTE COLONY-STIMULATING FACTOR, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 127 MIDDLE EAST: BIOSIMILARS MARKET FOR GRANULOCYTE COLONY-STIMULATING FACTOR, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 128 GCC COUNTRIES: BIOSIMILARS MARKET FOR GRANULOCYTE COLONY-STIMULATING FACTOR, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 129 BIOSIMILARS MARKET FOR INSULIN, BY REGION, 2024-2036 (USD MILLION)
- TABLE 130 NORTH AMERICA: BIOSIMILARS MARKET FOR INSULIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 131 EUROPE: BIOSIMILARS MARKET FOR INSULIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 132 ASIA PACIFIC: BIOSIMILARS MARKET FOR INSULIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 133 LATIN AMERICA: BIOSIMILARS MARKET FOR INSULIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 134 MIDDLE EAST: BIOSIMILARS MARKET FOR INSULIN, BY REGION, 2024-2036 (USD MILLION)
- TABLE 135 GCC COUNTRIES: BIOSIMILARS MARKET FOR INSULIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 136 LIST OF KEY APPROVED BIOSIMILARS FOR ERYTHROPOIETIN
- TABLE 137 BIOSIMILARS MARKET FOR ERYTHROPOIETIN, BY REGION, 2024-2036 (USD MILLION)
- TABLE 138 NORTH AMERICA: BIOSIMILARS MARKET FOR ERYTHROPOIETIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 139 EUROPE: BIOSIMILARS MARKET FOR ERYTHROPOIETIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 140 ASIA PACIFIC: BIOSIMILARS MARKET FOR ERYTHROPOIETIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 141 LATIN AMERICA: BIOSIMILARS MARKET FOR ERYTHROPOIETIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 142 MIDDLE EAST: BIOSIMILARS MARKET FOR ERYTHROPOIETIN, BY REGION, 2024-2036 (USD MILLION)
- TABLE 143 GCC COUNTRIES: BIOSIMILARS MARKET FOR ERYTHROPOIETIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 144 BIOSIMILARS MARKET FOR RECOMBINANT HUMAN GROWTH HORMONE, BY REGION, 2024-2036 (USD MILLION)
- TABLE 145 NORTH AMERICA: BIOSIMILARS MARKET FOR RECOMBINANT HUMAN GROWTH HORMONE, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 146 EUROPE: BIOSIMILARS MARKET FOR RECOMBINANT HUMAN GROWTH HORMONE, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 147 ASIA PACIFIC: BIOSIMILARS MARKET FOR RECOMBINANT HUMAN GROWTH HORMONE, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 148 LATIN AMERICA: BIOSIMILARS MARKET FOR RECOMBINANT HUMAN GROWTH HORMONE, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 149 MIDDLE EAST: BIOSIMILARS MARKET FOR RECOMBINANT HUMAN GROWTH HORMONE, BY REGION, 2024-2036 (USD MILLION)
- TABLE 150 GCC COUNTRIES: BIOSIMILARS MARKET FOR RECOMBINANT HUMAN GROWTH HORMONE, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 151 BIOSIMILARS MARKET FOR ETANERCEPT, BY REGION, 2024-2036 (USD MILLION)
- TABLE 152 NORTH AMERICA: BIOSIMILARS MARKET FOR ETANERCEPT, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 153 EUROPE: BIOSIMILARS MARKET FOR ETANERCEPT, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 154 ASIA PACIFIC: BIOSIMILARS MARKET FOR ETANERCEPT, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 155 LATIN AMERICA: BIOSIMILARS MARKET FOR ETANERCEPT, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 156 MIDDLE EAST: BIOSIMILARS MARKET FOR ETANERCEPT, BY REGION, 2024-2036 (USD MILLION)
- TABLE 157 GCC COUNTRIES: BIOSIMILARS MARKET FOR ETANERCEPT, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 158 BIOSIMILARS MARKET FOR FOLLITROPIN, BY REGION, 2024-2036 (USD MILLION)
- TABLE 159 NORTH AMERICA: BIOSIMILARS MARKET FOR FOLLITROPIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 160 EUROPE: BIOSIMILARS MARKET FOR FOLLITROPIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 161 ASIA PACIFIC: BIOSIMILARS MARKET FOR FOLLITROPIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 162 LATIN AMERICA: BIOSIMILARS MARKET FOR FOLLITROPIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 163 MIDDLE EAST: BIOSIMILARS MARKET FOR FOLLITROPIN, BY REGION, 2024-2036 (USD MILLION)
- TABLE 164 GCC COUNTRIES: BIOSIMILARS MARKET FOR FOLLITROPIN, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 165 BIOSIMILARS MARKET FOR TERIPARATIDE, BY REGION, 2024-2036 (USD MILLION)
- TABLE 166 NORTH AMERICA: BIOSIMILARS MARKET FOR TERIPARATIDE, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 167 EUROPE: BIOSIMILARS MARKET FOR TERIPARATIDE, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 168 ASIA PACIFIC: BIOSIMILARS MARKET FOR TERIPARATIDE, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 169 LATIN AMERICA: BIOSIMILARS MARKET FOR TERIPARATIDE, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 170 MIDDLE EAST: BIOSIMILARS MARKET FOR TERIPARATIDE, BY REGION, 2024-2036 (USD MILLION)
- TABLE 171 GCC COUNTRIES: BIOSIMILARS MARKET FOR TERIPARATIDE, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 172 BIOSIMILARS MARKET FOR INTERFERONS, BY REGION, 2024-2036 (USD MILLION)
- TABLE 173 NORTH AMERICA: BIOSIMILARS MARKET FOR INTERFERONS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 174 EUROPE: BIOSIMILARS MARKET FOR INTERFERONS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 175 ASIA PACIFIC: BIOSIMILARS MARKET FOR INTERFERONS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 176 LATIN AMERICA: BIOSIMILARS MARKET FOR INTERFERONS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 177 MIDDLE EAST: BIOSIMILARS MARKET FOR INTERFERONS, BY REGION, 2024-2036 (USD MILLION)
- TABLE 178 GCC COUNTRIES: BIOSIMILARS MARKET FOR INTERFERONS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 179 BIOSIMILARS MARKET FOR ANTICOAGULANTS, BY REGION, 2024-2036 (USD MILLION)
- TABLE 180 NORTH AMERICA: BIOSIMILARS MARKET FOR ANTICOAGULANTS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 181 EUROPE: BIOSIMILARS MARKET FOR ANTICOAGULANTS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 182 ASIA PACIFIC: BIOSIMILARS MARKET FOR ANTICOAGULANTS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 183 LATIN AMERICA: BIOSIMILARS MARKET FOR ANTICOAGULANTS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 184 MIDDLE EAST: BIOSIMILARS MARKET FOR ANTICOAGULANTS, BY REGION, 2024-2036 (USD MILLION)
- TABLE 185 GCC COUNTRIES: BIOSIMILARS MARKET FOR ANTICOAGULANTS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 186 BIOSIMILARS MARKET FOR AFLIBERCEPT, BY REGION, 2024-2036 (USD MILLION)
- TABLE 187 NORTH AMERICA: BIOSIMILARS MARKET FOR AFLIBERCEPT, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 188 EUROPE: BIOSIMILARS MARKET FOR AFLIBERCEPT, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 189 ASIA PACIFIC: BIOSIMILARS MARKET FOR AFLIBERCEPT, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 190 LATIN AMERICA: BIOSIMILARS MARKET FOR AFLIBERCEPT, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 191 MIDDLE EAST: BIOSIMILARS MARKET FOR AFLIBERCEPT, BY REGION, 2024-2036 (USD MILLION)
- TABLE 192 GCC COUNTRIES: BIOSIMILARS MARKET FOR AFLIBERCEPT, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 193 BIOSIMILARS MARKET FOR GLP-1 AGONIST, BY REGION, 2024-2036 (USD MILLION)
- TABLE 194 NORTH AMERICA: BIOSIMILARS MARKET FOR GLP-1 AGONIST, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 195 EUROPE: BIOSIMILARS MARKET FOR GLP-1 AGONIST, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 196 ASIA PACIFIC: BIOSIMILARS MARKET FOR GLP-1 AGONIST, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 197 LATIN AMERICA: BIOSIMILARS MARKET FOR GLP-1 AGONIST, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 198 MIDDLE EAST: BIOSIMILARS MARKET FOR GLP-1 AGONIST, BY REGION, 2024-2036 (USD MILLION)
- TABLE 199 GCC COUNTRIES: BIOSIMILARS MARKET FOR GLP-1 AGONIST, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 200 BIOSIMILARS MARKET FOR OTHER DRUG CLASSES, BY REGION, 2024-2036 (USD MILLION)
- TABLE 201 NORTH AMERICA: BIOSIMILARS MARKET FOR OTHER DRUG CLASSES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 202 EUROPE: BIOSIMILARS MARKET FOR OTHER DRUG CLASSES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 203 ASIA PACIFIC: BIOSIMILARS MARKET FOR OTHER DRUG CLASSES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 204 LATIN AMERICA: BIOSIMILARS MARKET FOR OTHER DRUG CLASSES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 205 MIDDLE EAST: BIOSIMILARS MARKET FOR OTHER DRUG CLASSES, BY REGION, 2024-2036 (USD MILLION)
- TABLE 206 GCC COUNTRIES: BIOSIMILARS MARKET FOR OTHER DRUG CLASSES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 207 BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 208 BIOSIMILARS MARKET FOR ONCOLOGY, BY REGION, 2024-2036 (USD MILLION)
- TABLE 209 NORTH AMERICA: BIOSIMILARS MARKET FOR ONCOLOGY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 210 EUROPE: BIOSIMILARS MARKET FOR ONCOLOGY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 211 ASIA PACIFIC: BIOSIMILARS MARKET FOR ONCOLOGY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 212 LATIN AMERICA: BIOSIMILARS MARKET FOR ONCOLOGY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 213 MIDDLE EAST: BIOSIMILARS MARKET FOR ONCOLOGY, BY REGION, 2024-2036 (USD MILLION)
- TABLE 214 GCC COUNTRIES: BIOSIMILARS MARKET FOR ONCOLOGY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 215 BIOSIMILARS MARKET FOR INFLAMMATORY & AUTOIMMUNE DISEASES, BY REGION, 2024-2036 (USD MILLION)
- TABLE 216 NORTH AMERICA: BIOSIMILARS MARKET FOR INFLAMMATORY & AUTOIMMUNE DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 217 EUROPE: BIOSIMILARS MARKET FOR INFLAMMATORY & AUTOIMMUNE DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 218 ASIA PACIFIC: BIOSIMILARS MARKET FOR INFLAMMATORY & AUTOIMMUNE DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 219 LATIN AMERICA: BIOSIMILARS MARKET FOR INFLAMMATORY & AUTOIMMUNE DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 220 MIDDLE EAST: BIOSIMILARS MARKET FOR INFLAMMATORY & AUTOIMMUNE DISEASES, BY REGION, 2024-2036 (USD MILLION)
- TABLE 221 GCC COUNTRIES: BIOSIMILARS MARKET FOR INFLAMMATORY & AUTOIMMUNE DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 222 BIOSIMILARS MARKET FOR CHRONIC DISEASES, BY REGION, 2024-2036 (USD MILLION)
- TABLE 223 NORTH AMERICA: BIOSIMILARS MARKET FOR CHRONIC DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 224 EUROPE: BIOSIMILARS MARKET FOR CHRONIC DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 225 ASIA PACIFIC: BIOSIMILARS MARKET FOR CHRONIC DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 226 LATIN AMERICA: BIOSIMILARS MARKET FOR CHRONIC DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 227 MIDDLE EAST: BIOSIMILARS MARKET FOR CHRONIC DISEASES, BY REGION, 2024-2036 (USD MILLION)
- TABLE 228 GCC COUNTRIES: BIOSIMILARS MARKET FOR CHRONIC DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 229 BIOSIMILARS MARKET FOR BLOOD DISORDERS, BY REGION, 2024-2036 (USD MILLION)
- TABLE 230 NORTH AMERICA: BIOSIMILARS MARKET FOR BLOOD DISORDERS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 231 EUROPE: BIOSIMILARS MARKET FOR BLOOD DISORDERS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 232 ASIA PACIFIC: BIOSIMILARS MARKET FOR BLOOD DISORDERS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 233 LATIN AMERICA: BIOSIMILARS MARKET FOR BLOOD DISORDERS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 234 MIDDLE EAST: BIOSIMILARS MARKET FOR BLOOD DISORDERS, BY REGION, 2024-2036 (USD MILLION)
- TABLE 235 GCC COUNTRIES: BIOSIMILARS MARKET FOR BLOOD DISORDERS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 236 BIOSIMILARS MARKET FOR GROWTH HORMONE DEFICIENCY, BY REGION, 2024-2036 (USD MILLION)
- TABLE 237 NORTH AMERICA: BIOSIMILARS MARKET FOR GROWTH HORMONE DEFICIENCY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 238 EUROPE: BIOSIMILARS MARKET FOR GROWTH HORMONE DEFICIENCY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 239 ASIA PACIFIC: BIOSIMILARS MARKET FOR GROWTH HORMONE DEFICIENCY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 240 LATIN AMERICA: BIOSIMILARS MARKET FOR GROWTH HORMONE DEFICIENCY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 241 MIDDLE EAST: BIOSIMILARS MARKET FOR GROWTH HORMONE DEFICIENCY, BY REGION, 2024-2036 (USD MILLION)
- TABLE 242 GCC COUNTRIES: BIOSIMILARS MARKET FOR GROWTH HORMONE DEFICIENCY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 243 BIOSIMILARS MARKET FOR INFECTIOUS DISEASES, BY REGION, 2024-2036 (USD MILLION)
- TABLE 244 NORTH AMERICA: BIOSIMILARS MARKET FOR INFECTIOUS DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 245 EUROPE: BIOSIMILARS MARKET FOR INFECTIOUS DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 246 ASIA PACIFIC: BIOSIMILARS MARKET FOR INFECTIOUS DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 247 LATIN AMERICA: BIOSIMILARS MARKET FOR INFECTIOUS DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 248 MIDDLE EAST: BIOSIMILARS MARKET FOR INFECTIOUS DISEASES, BY REGION, 2024-2036 (USD MILLION)
- TABLE 249 GCC COUNTRIES: BIOSIMILARS MARKET FOR INFECTIOUS DISEASES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 250 BIOSIMILARS MARKET FOR TYPE II DIABETES, BY REGION, 2024-2036 (USD MILLION)
- TABLE 251 NORTH AMERICA: BIOSIMILARS MARKET FOR TYPE II DIABETES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 252 EUROPE: BIOSIMILARS MARKET FOR TYPE II DIABETES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 253 ASIA PACIFIC: BIOSIMILARS MARKET FOR TYPE II DIABETES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 254 LATIN AMERICA: BIOSIMILARS MARKET FOR TYPE II DIABETES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 255 MIDDLE EAST: BIOSIMILARS MARKET FOR TYPE II DIABETES, BY REGION, 2024-2036 (USD MILLION)
- TABLE 256 GCC COUNTRIES: BIOSIMILARS MARKET FOR TYPE II DIABETES, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 257 BIOSIMILARS MARKET FOR OBESITY, BY REGION, 2024-2036 (USD MILLION)
- TABLE 258 NORTH AMERICA: BIOSIMILARS MARKET FOR OBESITY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 259 EUROPE: BIOSIMILARS MARKET FOR OBESITY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 260 ASIA PACIFIC: BIOSIMILARS MARKET FOR OBESITY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 261 LATIN AMERICA: BIOSIMILARS MARKET FOR OBESITY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 262 MIDDLE EAST: BIOSIMILARS MARKET FOR OBESITY, BY REGION, 2024-2036 (USD MILLION)
- TABLE 263 GCC COUNTRIES: BIOSIMILARS MARKET FOR OBESITY, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 264 BIOSIMILARS MARKET FOR OTHER INDICATIONS, BY REGION, 2024-2036 (USD MILLION)
- TABLE 265 NORTH AMERICA: BIOSIMILARS MARKET FOR OTHER INDICATIONS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 266 EUROPE: BIOSIMILARS MARKET FOR OTHER INDICATIONS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 267 ASIA PACIFIC: BIOSIMILARS MARKET FOR OTHER INDICATIONS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 268 LATIN AMERICA: BIOSIMILARS MARKET FOR OTHER INDICATIONS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 269 MIDDLE EAST: BIOSIMILARS MARKET FOR OTHER INDICATIONS, BY REGION, 2024-2036 (USD MILLION)
- TABLE 270 GCC COUNTRIES: BIOSIMILARS MARKET FOR OTHER INDICATIONS, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 271 BIOSIMILARS MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 272 NORTH AMERICA: BIOSIMILARS MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 273 NORTH AMERICA: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 274 NORTH AMERICA: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 275 NORTH AMERICA: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 276 US: LIST OF APPROVED BIOSIMILARS (2023-2026)
- TABLE 277 US: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 278 US: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 279 US: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 280 CANADA: LIST OF APPROVED BIOSIMILARS (2023-2026)
- TABLE 281 CANADA: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 282 CANADA: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 283 CANADA: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 284 EUROPE: LIST OF APPROVED BIOSIMILARS (2023-2026)
- TABLE 285 EUROPE: BIOSIMILARS MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 286 EUROPE: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 287 EUROPE: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 288 EUROPE: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 289 GERMANY: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 290 GERMANY: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 291 GERMANY: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 292 UK: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 293 UK: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 294 UK: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 295 FRANCE: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 296 FRANCE: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 297 FRANCE: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 298 ITALY: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 299 ITALY: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 300 ITALY: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 301 SPAIN: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 302 SPAIN: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 303 SPAIN: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 304 REST OF EUROPE: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 305 REST OF EUROPE: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 306 REST OF EUROPE: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 307 ASIA PACIFIC: BIOSIMILARS MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 308 ASIA PACIFIC: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 309 ASIA PACIFIC: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 310 ASIA PACIFIC: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 311 CHINA: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 312 CHINA: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 313 CHINA: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 314 JAPAN: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 315 JAPAN: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 316 JAPAN: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 317 INDIA: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 318 INDIA: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 319 INDIA: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 320 SOUTH KOREA: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 321 SOUTH KOREA: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 322 SOUTH KOREA: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 323 AUSTRALIA: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 324 AUSTRALIA: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 325 AUSTRALIA: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 326 REST OF ASIA PACIFIC: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 327 REST OF ASIA PACIFIC: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 328 REST OF ASIA PACIFIC: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 329 LATIN AMERICA: BIOSIMILARS MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 330 LATIN AMERICA: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 331 LATIN AMERICA: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 332 LATIN AMERICA: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 333 BRAZIL: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 334 BRAZIL: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 335 BRAZIL: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 336 MEXICO: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 337 MEXICO: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 338 MEXICO: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 339 REST OF LATIN AMERICA: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 340 REST OF LATIN AMERICA: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 341 REST OF LATIN AMERICA: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 342 MIDDLE EAST: BIOSIMILARS MARKET, BY REGION, 2024-2036 (USD MILLION)
- TABLE 343 MIDDLE EAST: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 344 MIDDLE EAST: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 345 MIDDLE EAST: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 346 GCC COUNTRIES: BIOSIMILARS MARKET, BY COUNTRY, 2024-2036 (USD MILLION)
- TABLE 347 GCC COUNTRIES: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 348 GCC COUNTRIES: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 349 GCC COUNTRIES: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 350 SAUDI ARABIA: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 351 SAUDI ARABIA: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 352 SAUDI ARABIA: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 353 UAE: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 354 UAE: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 355 UAE: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 356 REST OF GCC: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 357 REST OF GCC: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 358 REST OF GCC: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 359 REST OF MIDDLE EAST: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 360 REST OF MIDDLE EAST: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 361 REST OF MIDDLE EAST: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 362 AFRICA: BIOSIMILARS MARKET, BY DRUG CLASS, 2024-2036 (USD MILLION)
- TABLE 363 AFRICA: BIOSIMILARS MARKET FOR MONOCLONAL ANTIBODIES, BY TYPE, 2024-2036 (USD MILLION)
- TABLE 364 AFRICA: BIOSIMILARS MARKET, BY INDICATION, 2024-2036 (USD MILLION)
- TABLE 365 STRATEGIES DEPLOYED BY KEY PLAYERS
- TABLE 366 BIOSIMILARS MARKET: DEGREE OF COMPETITION
- TABLE 367 BIOSIMILARS MARKET: REGIONAL FOOTPRINT
- TABLE 368 BIOSIMILARS MARKET: DRUG CLASS FOOTPRINT
- TABLE 369 BIOSIMILARS MARKET: INDICATION FOOTPRINT
- TABLE 370 BIOSIMILARS MARKET: DETAILED LIST OF KEY STARTUP/SME PLAYERS
- TABLE 371 BIOSIMILARS MARKET: COMPETITIVE BENCHMARKING OF KEY EMERGING PLAYERS/STARTUPS, 2025
- TABLE 372 BIOSIMILARS MARKET: PRODUCT APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 373 BIOSIMILARS MARKET: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 374 BIOSIMILARS MARKET: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 375 SANDOZ GROUP AG: COMPANY OVERVIEW
- TABLE 376 SANDOZ GROUP AG: PRODUCTS OFFERED
- TABLE 377 SANDOZ GROUP AG: PRODUCTS IN PIPELINE
- TABLE 378 SANDOZ GROUP AG: PRODUCT LAUNCHES AND APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 379 SANDOZ GROUP AG: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 380 SANDOZ GROUP AG: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 381 SANDOZ GROUP AG: OTHER DEVELOPMENTS, JANUARY 2023-AUGUST 2026
- TABLE 382 AMGEN INC.: COMPANY OVERVIEW
- TABLE 383 AMGEN INC.: PRODUCTS OFFERED
- TABLE 384 AMGEN INC.: PRODUCTS IN PIPELINE
- TABLE 385 AMGEN INC.: PRODUCT LAUNCHES AND APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 386 AMGEN INC.: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 387 AMGEN INC.: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 388 CELLTRION INC.: COMPANY OVERVIEW
- TABLE 389 CELLTRION INC.: PRODUCTS OFFERED
- TABLE 390 CELLTRION INC.: PRODUCT LAUNCHES AND APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 391 CELLTRION INC.: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 392 CELLTRION INC.: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 393 PFIZER INC.: COMPANY OVERVIEW
- TABLE 394 PFIZER INC.: PRODUCTS OFFERED
- TABLE 395 PFIZER INC.: PRODUCT APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 396 PFIZER INC.: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 397 BIOCON: COMPANY OVERVIEW
- TABLE 398 BIOCON: PRODUCTS OFFERED
- TABLE 399 BIOCON: PRODUCT APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 400 BIOCON: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 401 BIOCON: OTHER DEVELOPMENTS, JANUARY 2023-AUGUST 2026
- TABLE 402 DR. REDDY'S LABORATORIES LTD.: COMPANY OVERVIEW
- TABLE 403 DR. REDDY'S LABORATORIES LTD.: PRODUCTS OFFERED
- TABLE 404 DR. REDDY'S LABORATORIES LTD.: PRODUCT LAUNCHES, JANUARY 2023-AUGUST 2026
- TABLE 405 DR. REDDY'S LABORATORIES LTD.: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 406 DR. REDDY'S LABORATORIES LTD.: OTHER DEVELOPMENTS, JANUARY 2023-AUGUST 2026
- TABLE 407 ELI LILLY AND COMPANY: COMPANY OVERVIEW
- TABLE 408 ELI LILLY AND COMPANY: PRODUCTS OFFERED
- TABLE 409 ELI LILLY AND COMPANY: PRODUCT LAUNCHES, JANUARY 2023-AUGUST 2026
- TABLE 410 ELI LILLY AND COMPANY: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 411 ELI LILLY AND COMPANY: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 412 TEVA PHARMACEUTICAL INDUSTRIES LTD.: COMPANY OVERVIEW
- TABLE 413 TEVA PHARMACEUTICAL INDUSTRIES LTD.: PRODUCTS OFFERED
- TABLE 414 TEVA PHARMACEUTICAL INDUSTRIES LTD.: PRODUCT LAUNCHES AND APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 415 TEVA PHARMACEUTICAL INDUSTRIES LTD.: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 416 TEVA PHARMACEUTICAL INDUSTRIES LTD.: OTHER DEVELOPMENTS, JANUARY 2023-AUGUST 2026
- TABLE 417 FRESENIUS KABI AG: COMPANY OVERVIEW
- TABLE 418 FRESENIUS KABI AG.: PRODUCTS OFFERED
- TABLE 419 FRESENIUS KABI AG: PRODUCT LAUNCHES AND APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 420 FRESENIUS KABI AG: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 421 FRESENIUS KABI AG: OTHER DEVELOPMENTS, JANUARY 2023-AUGUST 2026
- TABLE 422 STADA ARZNEIMITTEL AG: COMPANY OVERVIEW
- TABLE 423 STADA ARZNEIMITTEL AG: PRODUCTS OFFERED
- TABLE 424 STADA ARZNEIMITTEL AG: PRODUCT LAUNCHES AND APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 425 STADA ARZNEIMITTEL AG: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 426 STADA ARZNEIMITTEL AG: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 427 STADA ARZNEIMITTEL AG: OTHER DEVELOPMENTS, JANUARY 2023-AUGUST 2026
- TABLE 428 BOEHRINGER INGELHEIM INTERNATIONAL GMBH: COMPANY OVERVIEW
- TABLE 429 BOEHRINGER INGELHEIM INTERNATIONAL GMBH: PRODUCTS OFFERED
- TABLE 430 BOEHRINGER INGELHEIM INTERNATIONAL GMBH: PRODUCT APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 431 BOEHRINGER INGELHEIM INTERNATIONAL GMBH: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 432 BOEHRINGER INGELHEIM INTERNATIONAL GMBH: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 433 SAMSUNG BIOEPIS HOLDINGS CO., LTD.: COMPANY OVERVIEW
- TABLE 434 SAMSUNG BIOEPIS HOLDINGS CO., LTD.: PRODUCTS OFFERED
- TABLE 435 SAMSUNG BIOEPIS HOLDINGS CO., LTD.: PRODUCT LAUNCHES AND APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 436 SAMSUNG BIOEPIS HOLDINGS CO., LTD.: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 437 AMNEAL PHARMACEUTICALS LLC: COMPANY OVERVIEW
- TABLE 438 AMNEAL PHARMACEUTICALS LLC: PRODUCTS OFFERED
- TABLE 439 AMNEAL PHARMACEUTICALS LLC: PRODUCT APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 440 AMNEAL PHARMACEUTICALS INC: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 441 AMNEAL PHARMACEUTICALS INC: OTHER DEVELOPMENTS, JANUARY 2023-AUGUST 2026
- TABLE 442 BIO THERA SOLUTIONS: COMPANY OVERVIEW
- TABLE 443 BIO THERA SOLUTIONS: PRODUCTS OFFERED
- TABLE 444 BIO THERA SOLUTIONS: PRODUCT APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 445 BIO THERA SOLUTIONS: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 446 APROGEN: COMPANY OVERVIEW
- TABLE 447 APROGEN: PRODUCTS OFFERED
- TABLE 448 APROGEN: PRODUCT DEVELOPMENTS, JANUARY 2023-AUGUST 2026
- TABLE 449 APROGEN: PRODUCTS IN PIPELINE
- TABLE 450 SHANGHAI HENLIUS BIOTECH, INC.: COMPANY OVERVIEW
- TABLE 451 SHANGHAI HENLIUS BIOTECH, INC.: PRODUCTS OFFERED
- TABLE 452 SHANGHAI HENLIUS BIOTECH, INC.: PRODUCTS IN PIPELINE
- TABLE 453 SHANGHAI HENLIUS BIOTECH, INC.: PRODUCT APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 454 SHANGHAI HENLIUS BIOTECH, INC.: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 455 SHANGHAI HENLIUS BIOTECH, INC.: OTHER DEVELOPMENTS, JANUARY 2023-AUGUST 2026
- TABLE 456 ALVOTECH: COMPANY OVERVIEW
- TABLE 457 ALVOTECH: PRODUCTS OFFERED
- TABLE 458 ALVOTECH: PRODUCTS IN PIPELINE
- TABLE 459 ALVOTECH: PRODUCT APPROVALS, JANUARY 2023-AUGUST 2026
- TABLE 460 ALVOTECH: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 461 AMEGA BIOTECH: COMPANY OVERVIEW
- TABLE 462 BIOCAD: COMPANY OVERVIEW
- TABLE 463 PROBIOMED S.A. DE C.V.: COMPANY OVERVIEW
- TABLE 464 FUJIFILM KYOWA KIRIN BIOLOGICS CO., LTD.: COMPANY OVERVIEW
- TABLE 465 POLPHARMA BIOLOGICS GROUP: COMPANY OVERVIEW
- TABLE 466 NEUCLONE: COMPANY OVERVIEW
- TABLE 467 XENTRIA: COMPANY OVERVIEW
- TABLE 468 NANOGEN PHARMACEUTICAL BIOTECHNOLOGY JSC: COMPANY OVERVIEW
- TABLE 469 SYNERMORE BIOLOGICS (SUZHOU) CO., LTD.: COMPANY OVERVIEW
- TABLE 470 CURATEQ BIOLOGICS PVT. LTD.: COMPANY OVERVIEW
- TABLE 471 XBRANE BIOPHARMA AB: COMPANY OVERVIEW
- TABLE 472 FORMYCON AG: COMPANY OVERVIEW
- TABLE 473 SAM CHUN DANG PHARM. CO., LTD.: COMPANY OVERVIEW
- TABLE 474 PRESTIGE BIOPHARMA: COMPANY OVERVIEW
- TABLE 475 BIOEQ AG: COMPANY OVERVIEW
- TABLE 476 IMPACT ANALYSIS OF SUPPLY-SIDE AND DEMAND-SIDE FACTORS
List of Figures
- FIGURE 1 BIOSIMILARS MARKET: SEGMENTS CONSIDERED
- FIGURE 2 BIOSIMILARS MARKET: YEARS CONSIDERED
- FIGURE 3 MARKET SCENARIO
- FIGURE 4 GLOBAL BIOSIMILARS MARKET, 2024-2036
- FIGURE 5 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN BIOSIMILARS MARKET, 2024-2036
- FIGURE 6 DISRUPTIONS INFLUENCING GROWTH OF BIOSIMILARS MARKET
- FIGURE 7 HIGH-GROWTH SEGMENTS IN BIOSIMILARS MARKET, 2026-2036
- FIGURE 8 MIDDLE EAST TO REGISTER HIGHEST CAGR IN BIOSIMILARS MARKET, IN TERMS OF VALUE, DURING FORECAST PERIOD
- FIGURE 9 APPROVALS OF BIOSIMILARS TO DRIVE MARKET GROWTH
- FIGURE 10 MONOCLONAL ANTIBODIES SEGMENT ACCOUNTED FOR LARGEST SHARE OF BIOSIMILARS MARKET IN NORTH AMERICA IN 2025
- FIGURE 11 MEXICO LIKELY TO BE FASTEST-GROWING MARKET IN GLOBAL BIOSIMILARS MARKET DURING FORECAST PERIOD
- FIGURE 12 ONCOLOGY SEGMENT TO DOMINATE MARKET DURING FORECAST PERIOD
- FIGURE 13 BIOSIMILARS MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 14 BIOSIMILARS MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 15 BIOSIMILARS MARKET: VALUE CHAIN ANALYSIS
- FIGURE 16 BIOSIMILARS MARKET: SUPPLY CHAIN ANALYSIS
- FIGURE 17 BIOSIMILARS MARKET: ECOSYSTEM ANALYSIS
- FIGURE 18 AVERAGE SELLING PRICE TREND OF BIOSIMILAR PRODUCTS, 2023-2025 (USD)
- FIGURE 19 AVERAGE SELLING PRICE TREND OF BIOSIMILAR PRODUCTS, BY REGION, 2023-2025 (USD)
- FIGURE 20 BIOSIMILARS MARKET: TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- FIGURE 21 VC/PRIVATE EQUITY INVESTMENT TRENDS & STARTUP LANDSCAPE
- FIGURE 22 IMPACT OF AI/GEN AI ON BIOSIMILARS MARKET
- FIGURE 23 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY DRUG CLASS
- FIGURE 24 KEY BUYING CRITERIA FOR BIOSIMILAR PRODUCTS, BY END USER
- FIGURE 25 EUROPE: BIOSIMILARS MARKET SNAPSHOT
- FIGURE 26 MIDDLE EAST: BIOSIMILARS MARKET SNAPSHOT
- FIGURE 27 REVENUE ANALYSIS OF KEY PLAYERS, 2023-2025 (USD MILLION)
- FIGURE 28 MARKET SHARE ANALYSIS OF KEY PLAYERS (2025)
- FIGURE 29 BIOSIMILARS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 30 BIOSIMILARS MARKET: COMPANY FOOTPRINT
- FIGURE 31 BIOSIMILARS MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2024
- FIGURE 32 EV/EBITDA OF KEY VENDORS
- FIGURE 33 YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDORS
- FIGURE 34 BIOSIMILARS MARKET: BRAND/PRODUCT COMPARATIVE ANALYSIS
- FIGURE 35 SANDOZ GROUP AG: COMPANY SNAPSHOT (2025)
- FIGURE 36 AMGEN INC.: COMPANY SNAPSHOT (2025)
- FIGURE 37 CELLTRION INC.: COMPANY SNAPSHOT (2025)
- FIGURE 38 PFIZER INC.: COMPANY SNAPSHOT (2025)
- FIGURE 39 BIOCON: COMPANY SNAPSHOT (2025)
- FIGURE 40 DR. REDDY'S LABORATORIES LTD.: COMPANY SNAPSHOT (2025)
- FIGURE 41 ELI LILLY AND COMPANY: COMPANY SNAPSHOT (2025)
- FIGURE 42 TEVA PHARMACEUTICAL INDUSTRIES LTD.: COMPANY SNAPSHOT (2025)
- FIGURE 43 FRESENIUS KABI AG.: COMPANY SNAPSHOT (2025)
- FIGURE 44 STADA ARZNEIMITTEL AG: COMPANY SNAPSHOT (2025)
- FIGURE 45 BOEHRINGER INGELHEIM INTERNATIONAL GMBH: COMPANY SNAPSHOT (2025)
- FIGURE 46 SAMSUNG BIOEPIS HOLDINGS CO., LTD.: COMPANY SNAPSHOT (2025)
- FIGURE 47 AMNEAL PHARMACEUTICALS LLC: COMPANY SNAPSHOT (2025)
- FIGURE 48 BIO THERA SOLUTIONS: COMPANY SNAPSHOT (2025)
- FIGURE 49 SHANGHAI HENLIUS BIOTECH, INC.: COMPANY SNAPSHOT (2025)
- FIGURE 50 ALVOTECH: COMPANY SNAPSHOT (2025)
- FIGURE 51 RESEARCH DESIGN
- FIGURE 52 BREAKDOWN OF PRIMARY INTERVIEWS: BIOSIMILARS MARKET
- FIGURE 53 BIOSIMILARS MARKET SIZE ESTIMATION (SUPPLY-SIDE ANALYSIS), 2025
- FIGURE 54 MARKET SIZE ESTIMATION: APPROACH 1 (COMPANY REVENUE ANALYSIS-BASED ESTIMATION), 2025
- FIGURE 55 ILLUSTRATIVE EXAMPLE OF SANDOZ GROUP AG (SWITZERLAND): REVENUE SHARE ANALYSIS (2025)
- FIGURE 56 MARKET SIZE VALIDATION FROM PRIMARY SOURCES
- FIGURE 57 MARKET SIZE ESTIMATION METHODOLOGY: TOP-DOWN APPROACH
- FIGURE 58 BIOSIMILARS MARKET: CAGR PROJECTIONS
- FIGURE 59 DATA TRIANGULATION METHODOLOGY

