PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2138095

PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2138095
Connected Motorcycle Market by Hardware (Embedded & Tethered/Integrated), Network Type (3G/4G, 5G), Two-wheeler Type, Propulsion Type, End User, Application (Safety & Security, Navigation, Infotainment), and Region - Global Forecast to 2033
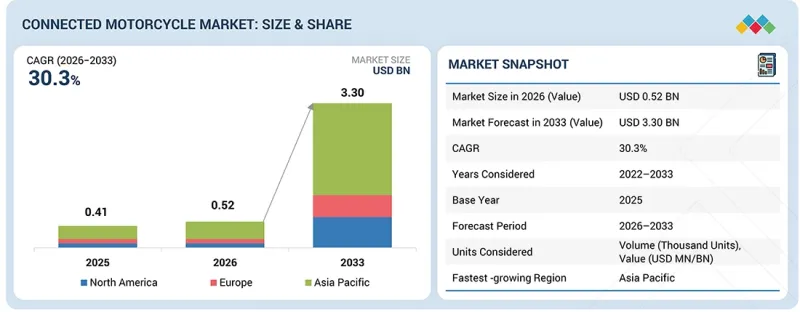
The connected motorcycle market is estimated to grow from USD 0.52 billion in 2026 to USD 3.30 billion in 2033, at a CAGR of 30.3%. The connected motorcycle market is shifting from basic smartphone-linked features toward an always connected vehicle architecture in which the motorcycle continuously exchanges operational, location, rider, and powertrain data with cloud platforms. Integration of telematics control units, eSIM connectivity, GNSS tracking, embedded connectivity, and cloud-connected motorcycles is allowing OEMs to establish persistent data channels for remote diagnostics, vehicle health monitoring, predictive maintenance, anti-theft systems, and OTA updates.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2033 |
| Base Year | 2025 |
| Forecast Period | 2026-2033 |
| Units Considered | USD billion |
| Segments | Two-wheeler Type, Hardware, Propulsion Type, Network Type, End User and Application |
| Regions covered | Asia Pacific, North America, Europe |
For electric two-wheelers, this architecture is becoming more significant as BMS connectivity, battery state of charge monitoring, range monitoring, and EV remote diagnostics create a direct data interface between the battery system, vehicle controller, rider application, and backend platform. The strategic shift is therefore moving connectivity from an optional digital feature toward an underlying data infrastructure for smart motorcycles, connected scooters, intelligent motorcycles, and connected mobility, enabling OEMs to extend vehicle functionality after sale and build recurring software and connected services around the motorcycle.
"Higher Electronic Integration Drives Connected Feature Adoption"
The 126 CC to 300 CC ICE motorcycle segment is leading connected motorcycle adoption because these motorcycles typically incorporate more advanced electronic architectures than entry-level models, including ECUs, digital instrument clusters, Bluetooth modules, GNSS, telematics, and smartphone connectivity. The segment is also widely used for urban commuting and premium daily mobility, increasing demand for motorcycle telematics, ride analytics, navigation, vehicle tracking, remote diagnostics, and anti-theft systems. The higher electronic content creates greater integration opportunities for embedded connectivity, IoT platforms, cloud-connected motorcycles, OTA updates, and vehicle health monitoring, while OEMs can add these functions without the cost burden associated with high-displacement premium motorcycles. The combination of higher electronic content, strong sales volumes, and increasing demand for digital rider services is therefore supporting the segment's leading position. For instance, Yamaha MT 15, 155 CC integrates smartphone connectivity through Yamaha's Y Connect platform, enabling ride data, maintenance information, fuel consumption, and other connected functions.
"5G adoption is accelerating as connected motorcycles require higher bandwidth, lower latency, and real-time vehicle intelligence"
The rapid integration of embedded connectivity, motorcycle telematics, and vehicle connectivity is driving 5G adoption across connected motorcycles and connected two wheelers, particularly as smart motorcycles, digital motorcycles, and connected electric motorcycles incorporate data intensive functions. Higher bandwidth and lower latency enable faster communication between the telematics control unit, cloud-connected motorcycles, and connected vehicle platforms, supporting real-time remote diagnostics, vehicle health monitoring, rider analytics, remote vehicle monitoring, navigation and infotainment, emergency assistance, and anti-theft systems. For connected electric scooters and electric two wheeler telematics, 5G also strengthens BMS connectivity, battery state of charge monitoring, range monitoring, battery connectivity, EV remote diagnostics, and EV OTA updates, making advanced cellular connectivity increasingly relevant for next generation connected mobility and the connected two wheeler market. For instance, Yamaha's Y Connect ecosystem uses an onboard Communication Control Unit to connect motorcycles with cloud-based applications, enabling riding logs, vehicle information, maintenance recommendations, location information, and, for EV models, battery level and estimated range monitoring. As such connected functions expand toward real-time remote diagnostics, battery monitoring, predictive maintenance, and OTA updates, the higher bandwidth and lower latency of 5G are supporting the transition toward more advanced connected motorcycles and connected electric two-wheelers.
"Stringent EU vehicle requirements and rapid OEM integration of telematics are accelerating connected motorcycle adoption in Europe"
Europe is a growing region for the connected motorcycle market as the region combines stringent L category vehicle safety and environmental requirements with high adoption of electronically equipped premium motorcycles. EU type approval requirements have progressively strengthened onboard diagnostics and electronic monitoring for motorcycles, creating a stronger technical foundation for vehicle health monitoring, remote diagnostics, motorcycle telematics, and connected vehicle platforms. At the same time, European OEMs such as BMW Motorrad and Ducati are integrating connectivity, GNSS tracking, navigation and infotainment, ride analytics, maintenance information, and smartphone-connected functions into production motorcycles. BMW Motorrad supports navigation, route recording, and motorcycle service information through its Connected ecosystem, while Ducati uses its connected platform for performance data, navigation, vehicle parameter management, and ride analytics.
A regional driving factor is the growing emphasis on anti-theft systems and emergency assistance. EU-funded H GEAR technology combines Galileo-based positioning, motorcycle anti-theft functionality, mobile alerts, vehicle tracking, battery status information, and eCall functionality for small and medium motorcycles. GPS tracking, remote vehicle monitoring, motorcycle IoT, and connected mobility are moving from optional features toward integrated vehicle functions in connected scooters, connected mopeds, smart motorcycles, and intelligent motorcycles. The expansion of connected electric motorcycles and connected electric scooters is further increasing demand for battery connectivity, BMS connectivity, battery state of charge monitoring, range monitoring, EV remote diagnostics, and EV OTA updates, supporting Europe's strong growth in the connected two-wheeler market.
In-depth interviews were conducted with CEOs, marketing directors, innovation and technology directors, and executives from various key organizations operating in this market.
- By Company Type: OEMs - 33%, Hardware & Software Providers - 67%
- By Designation: CXOs - 33%, Directors - 15%, Others - 52%
- By Country: Asia Pacific - 60%, North America - 15%, Europe - 25%
The dominance of technology providers is driven by the specialized technical infrastructure required to connect motorcycles, which many OEMs source from external providers rather than developing entirely in-house. Companies such as Starcom Systems, Comodule, KPIT Technologies, Ituran Global, and Novia are supplying combinations of telematics control units, embedded connectivity, GNSS tracking, cloud platforms, eSIM connectivity, vehicle data management, remote diagnostics, anti-theft systems, and connected vehicle services. Their ability to integrate hardware, cellular communication, software, and cloud interfaces into OEM vehicle architectures is reducing development time and enabling faster deployment across multiple motorcycle models and regions. Product development and strategic deals are therefore allowing these providers to expand their technology into connected motorcycles, connected scooters, fleet management, vehicle tracking, remote monitoring, and EV telematics applications, strengthening their position across the connected two-wheeler market. Ituran Global offers connected vehicle technology for two-wheelers, integrating telematics solutions that combine GNSS positioning, cellular communication, vehicle tracking, anti-theft functionality, and remote monitoring. The company's technology enables continuous transmission of vehicle location and status data to backend systems, supporting theft recovery and fleet or asset monitoring.
Research Coverage:
The report covers the Connected Motorcycle Market by Two-wheeler Type, Hardware, Propulsion Type, Network Type, End-User, Application, and Region. It covers the competitive landscape and company profiles of the major players in the Connected Motorcycle Market ecosystem.
The study also includes an in-depth competitive analysis of the key players in the market, along with their company profiles, key observations related to product and business offerings, recent developments, and key market strategies.
Key Benefits of Buying the Report:
- This report will help market leaders/new entrants in this market with information on the closest approximations of revenue numbers for the Connected Motorcycle Market ecosystem and its subsegments.
- This report will help stakeholders understand the competitive landscape and gain more insights to better position their businesses and plan suitable go-to-market strategies.
- This report will also help stakeholders understand the market's pulse and provide information on key market drivers, restraints, challenges, and opportunities.
The report provides insight on the following pointers:
- Analysis of key drivers (Growing OEM Integration of Telematics and Connected Services, Rising Adoption of Connected Electric Two-Wheelers, Expanding Connected Rider and Vehicle Applications), restraints (High Cost and Limited Willingness to Pay, Fragmentation of Connectivity Ecosystems), opportunities (Growth of Connected-Service Monetization, Expansion of Connected Diagnostics and Aftermarket Telematics), and challenges (Rising Cybersecurity Risks, Increasing Software and OTA Complexity)
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product launches in the Connected Motorcycle Market.
- Market Development: Comprehensive information about lucrative markets - the report analyses the Connected Motorcycle Market across varied regions.
- Market Diversification: Exhaustive information about new products, untapped geographies, recent developments, and investments in the Connected Motorcycle Market.
- Competitive Assessment: In-depth assessment of market ranking, growth strategies, and service offerings of leading players.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.4 YEARS CONSIDERED
- 1.5 CURRENCY CONSIDERED
- 1.6 UNIT CONSIDERED
- 1.7 STAKEHOLDERS
- 1.8 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN CONNECTED MOTORCYCLE MARKET
- 2.4 HIGH-GROWTH SEGMENTS IN CONNECTED MOTORCYCLE MARKET
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN CONNECTED MOTORCYCLE MARKET
- 3.2 CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE
- 3.3 CONNECTED MOTORCYCLE MARKET, BY HARDWARE
- 3.4 CONNECTED MOTORCYCLE MARKET, BY PROPULSION TYPE
- 3.5 CONNECTED MOTORCYCLE MARKET, BY NETWORK TYPE
- 3.6 CONNECTED MOTORCYCLE MARKET, BY END USER
- 3.7 CONNECTED MOTORCYCLE MARKET, BY APPLICATION
- 3.8 CONNECTED MOTORCYCLE MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing OEM integration of telematics and connected services
- 4.2.1.2 Rising adoption of connected electric two-wheelers
- 4.2.1.3 Expanding connected rider and vehicle applications
- 4.2.2 RESTRAINTS
- 4.2.2.1 High cost and limited willingness to pay
- 4.2.2.2 Fragmentation of connectivity ecosystems
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Growth of connected-service monetization
- 4.2.3.2 Expansion of connected diagnostics and aftermarket telematics
- 4.2.4 CHALLENGES
- 4.2.4.1 Rising cybersecurity risks
- 4.2.4.2 Increasing software and OTA complexity
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 SEAMLESS CROSS-OEM CONNECTIVITY
- 4.3.2 COMPREHENSIVE MOTORCYCLE-SPECIFIC EMERGENCY RESPONSE
5 INDUSTRY TRENDS
- 5.1 MACROECONOMIC INDICATORS
- 5.1.1 INTRODUCTION
- 5.1.2 GDP TRENDS AND FORECAST
- 5.1.3 TRENDS IN GLOBAL AUTOMOTIVE SCOOTERS AND MOTORCYCLES MARKET
- 5.1.4 TRENDS IN GLOBAL CONNECTED VEHICLE INDUSTRY
- 5.2 SUPPLY CHAIN ANALYSIS
- 5.3 ECOSYSTEM MAPPING
- 5.3.1 NETWORK PROVIDERS
- 5.3.2 SERVICE PLATFORM PROVIDERS
- 5.3.3 SOFTWARE PROVIDERS
- 5.3.4 HARDWARE PROVIDERS
- 5.3.5 OEMS
- 5.4 PRICING ANALYSIS
- 5.4.1 AVERAGE PRICING ANALYSIS BY KEY PLAYERS, 2024-2026
- 5.4.2 AVERAGE PRICING ANALYSIS, BY REGION (2024-2026)
- 5.5 TRADE ANALYSIS
- 5.5.1 IMPORT SCENARIO (HS CODE 8711)
- 5.5.2 EXPORT SCENARIO (HS CODE 8711)
- 5.6 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.7 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESSES
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 CASE STUDY ANALYSIS
- 5.9.1 CONNECTED VEHICLE PLATFORM FOR REMOTE DIAGNOSTICS AND OTA UPDATES
- 5.9.2 OTA SOFTWARE UPDATES AND FUNCTION ON DEMAND FOR TWO-WHEELERS
- 5.9.3 CONNECTED MOTORCYCLE PLATFORM FOR ADVENTURE MOTORCYCLES
- 5.9.4 CONNECTED MOTORCYCLE ECOSYSTEM FOR NAVIGATION AND VEHICLE DATA
- 5.10 IMPACT OF ISRAEL-IRAN WAR
- 5.10.1 INTRODUCTION
- 5.10.2 ENERGY MARKET DISRUPTION
- 5.10.3 FUEL PRICE VOLATILITY INCREASES VALUE PROPOSITION OF CONNECTED MOTORCYCLE FEATURES
- 5.10.4 OPERATING COST IMPACT
- 5.10.5 MARKET DEMAND SHIFT
- 5.10.6 SUPPLY CHAIN AND LOCALIZATION IMPACT
- 5.10.7 STRATEGIC MARKET OUTLOOK
- 5.11 EU-INDIA TRADE DEAL IMPACT ANALYSIS
- 5.11.1 INTRODUCTION
- 5.11.2 EU TARIFFS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 INTRODUCTION
- 6.1.2 KEY TECHNOLOGIES
- 6.1.2.1 Embedded telematics systems
- 6.1.2.2 ECU and sensor integration
- 6.1.2.3 Advanced rider assistance system (ARAS)
- 6.1.3 COMPLEMENTARY TECHNOLOGIES
- 6.1.3.1 Smartphone connectivity platforms
- 6.1.3.2 Human machine interface (HMI) systems
- 6.1.3.3 Navigation and geo-fencing modules
- 6.1.3.4 Integration of smart helmets with wearables
- 6.1.4 ADJACENT TECHNOLOGIES
- 6.1.4.1 Over-the-air (OTA) update systems
- 6.1.4.2 Battery management systems (BMS) for connected EVs
- 6.1.4.3 Predictive maintenance
- 6.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.3 PATENT ANALYSIS
- 6.4 IMPACT OF AI/GEN AI
- 6.5 FUTURE APPLICATIONS
- 6.5.1 VEHICLE DATA ENABLES PREDICTIVE MAINTENANCE AND RECURRING SERVICE REVENUE
- 6.5.2 V2X CONNECTIVITY TURNS MOTORCYCLES INTO COOPERATIVE SAFETY NODES
- 6.5.3 FLEET CONNECTIVITY CONVERTS MOTORCYCLES INTO DATA-DRIVEN COMMERCIAL ASSETS
7 KEY STAKEHOLDERS & BUYING CRITERIA
- 7.1 DECISION-MAKING PROCESS
- 7.2 KEY STAKEHOLDERS AND BUYING CRITERIA
- 7.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 7.2.2 BUYING CRITERIA
8 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 8.1 REGULATORY LANDSCAPE
- 8.1.1 LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 8.1.2 REGULATORY FRAMEWORK
- 8.1.2.1 Canada
- 8.1.2.2 US
- 8.1.2.3 European Union
- 8.1.2.3.1 General Data Protection Regulation (GDPR)
9 CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE
- 9.1 INTRODUCTION
- 9.2 MOTORCYCLE
- 9.2.1 HIGHER VEHICLE COMPLEXITY INCREASING VALUE OF EMBEDDED CONNECTIVITY IN MOTORCYCLES
- 9.3 SCOOTER/MOPED
- 9.3.1 HIGH URBAN USAGE SHIFTING SCOOTER CONNECTIVITY TOWARD PRACTICAL DIGITAL SERVICES
- 9.4 KEY PRIMARY INSIGHTS
10 CONNECTED MOTORCYCLE MARKET, BY HARDWARE
- 10.1 INTRODUCTION
- 10.2 EMBEDDED
- 10.2.1 DEDICATED CONNECTIVITY HARDWARE ENABLES ALWAYS-ON MOTORCYCLE SERVICES
- 10.3 INTEGRATED
- 10.3.1 INTEGRATED ELECTRONICS TURN CONNECTIVITY INTO CORE RIDER EXPERIENCE
- 10.4 KEY PRIMARY INSIGHTS
11 CONNECTED MOTORCYCLE MARKET, BY PROPULSION TYPE
- 11.1 INTRODUCTION
- 11.1.1 BESTSELLING CONNECTED MOTORCYCLES, BY PROPULSION, 2025
- 11.2 ICE
- 11.2.1 GREATER VEHICLE INTELLIGENCE EXTENDING CONNECTIVITY BEYOND RIDER CONVENIENCE
- 11.2.2 < 125 CC
- 11.2.2.1 Lower vehicle price limiting advanced connectivity adoption
- 11.2.3 126-300 CC
- 11.2.3.1 Growing premiumization expanding connected motorcycle functionality
- 11.2.4 > 300 CC
- 11.2.4.1 Premium vehicle architecture enabling advanced connected experiences
- 11.3 ELECTRIC
- 11.3.1 BATTERY INTELLIGENCE TURNING CONNECTIVITY INTO CORE EV OPERATING SYSTEM
- 11.3.2 < 3 KW
- 11.3.2.1 Lower power EVs prioritize essential battery and vehicle connectivity
- 11.3.3 3-7 KW
- 11.3.3.1 Increasing battery dependence driving deeper vehicle connectivity
- 11.3.4 > 7 KW
- 11.3.4.1 High-power EVs making connectivity integral to vehicle intelligence
- 11.4 KEY PRIMARY INSIGHTS
12 CONNECTED MOTORCYCLE MARKET, BY NETWORK TYPE
- 12.1 INTRODUCTION
- 12.2 3G/4G
- 12.2.1 WIDER CELLULAR COVERAGE MAKING CLOUD-CONNECTED FUNCTIONS STANDARD ACROSS MOTORCYCLES
- 12.3 5G
- 12.3.1 HIGHER BANDWIDTH AND LOWER LATENCY ENABLING SAFETY-INTENSIVE MOTORCYCLE CONNECTIVITY
- 12.4 OTHERS
- 12.4.1 DIRECT VEHICLE COMMUNICATION EXTENDING MOTORCYCLE SAFETY BEYOND LINE OF SIGHT
- 12.5 KEY PRIMARY INSIGHTS
13 CONNECTED MOTORCYCLE MARKET, BY END USER
- 13.1 INTRODUCTION
- 13.1.1 COMPANIES PROVIDING RIDE-HAILING SERVICES ON MOTORCYCLES
- 13.2 PRIVATE
- 13.2.1 RISING DEMAND FOR CONNECTED RIDING EXPERIENCES DRIVING PRIVATE MOTORCYCLE CONNECTIVITY
- 13.3 COMMERCIAL
- 13.3.1 FLEET DIGITIZATION AND RISING DELIVERY DEMAND ACCELERATING COMMERCIAL MOTORCYCLE CONNECTIVITY
- 13.4 KEY PRIMARY INSIGHTS
14 CONNECTED MOTORCYCLE MARKET, BY APPLICATION
- 14.1 INTRODUCTION
- 14.2 SAFETY & SECURITY
- 14.2.1 INCREASED EMPHASIS ON SAFETY AND SECURITY DURING COMMUTE TO DRIVE MARKET
- 14.2.2 ECALL & BCALL
- 14.2.3 GEO-FENCING
- 14.2.4 ADVANCED RIDER ASSISTANCE SYSTEMS (ARAS)
- 14.2.5 RIDER BEHAVIOR MONITORING
- 14.3 NAVIGATION
- 14.3.1 INCREASING POPULARITY OF CONNECTED FEATURES FOR NAVIGATION PURPOSES TO DRIVE DEMAND
- 14.3.2 TURN-BY-TURN NAVIGATION
- 14.3.3 REAL-TIME TRAFFIC UPDATES
- 14.3.4 TRIP PLANNING & ROUTE SHARING
- 14.3.5 PARKING ASSISTANCE & LOCATOR
- 14.4 VEHICLE HEALTH & DIAGNOSTICS
- 14.4.1 EMPHASIS ON MAINTAINING HEALTH OF TWO-WHEELERS TO DRIVE MARKET
- 14.4.2 PREDICTIVE MAINTENANCE ALERTS
- 14.4.3 BATTERY MANAGEMENT SYSTEM (FOR EVS)
- 14.4.4 REMOTE DIAGNOSTICS
- 14.5 INFOTAINMENT & COMMUNICATION
- 14.5.1 SMARTPHONE CONNECTIVITY
- 14.5.2 MUSIC/MEDIA STREAMING AND VOICE ASSISTANTS
- 14.5.3 RIDE TELEMETRY & PERFORMANCE ANALYTICS
- 14.5.4 HELMET CONNECTIVITY
- 14.6 OTHER APPLICATIONS
- 14.6.1 OTA SOFTWARE UPDATES
- 14.6.2 REMOTE FEATURE UNLOCKS/SUBSCRIPTION UPGRADES
- 14.6.3 CHARGING STATION LOCATOR
- 14.6.4 REMOTE LOCK/UNLOCK (FOR SHARED BIKES)
- 14.7 KEY PRIMARY INSIGHTS
15 CONNECTED MOTORCYCLE MARKET, BY REGION
- 15.1 INTRODUCTION
- 15.2 ASIA PACIFIC
- 15.2.1 CHINA
- 15.2.1.1 Large two-wheeler base and expanding digital ecosystem to accelerate connected motorcycle adoption
- 15.2.2 INDIA
- 15.2.2.1 Electrification and smart scooter adoption to drive market growth
- 15.2.3 JAPAN
- 15.2.3.1 Premium motorcycles, advanced rider technology, and digital integration to drive growth
- 15.2.4 SOUTH KOREA
- 15.2.4.1 Smart urban mobility and digital infrastructure to accelerate demand
- 15.2.5 PHILIPPINES
- 15.2.5.1 High two-wheeler dependence and expanding digital mobility services to support adoption
- 15.2.6 INDONESIA
- 15.2.6.1 Platform-led delivery and ride-hailing demand to accelerate market growth
- 15.2.7 VIETNAM
- 15.2.7.1 Electric scooter expansion to accelerate embedded connectivity adoption
- 15.2.8 THAILAND
- 15.2.8.1 Premium scooter demand and electric mobility development to support market growth
- 15.2.9 REST OF ASIA PACIFIC
- 15.2.9.1 Smart electric mobility expansion and premium scooter demand to strengthen adoption
- 15.2.1 CHINA
- 15.3 EUROPE
- 15.3.1 FRANCE
- 15.3.1.1 Electric mobility growth and connected vehicle regulation to strengthen telematics adoption
- 15.3.2 GERMANY
- 15.3.2.1 Premium model launches and advanced digital features to strengthen connected motorcycle adoption
- 15.3.3 ITALY
- 15.3.3.1 Strong domestic OEM innovation and premium model launches to expand market
- 15.3.4 SPAIN
- 15.3.4.1 Strong scooter demand and rising focus on connected safety technologies to drive market
- 15.3.5 UK
- 15.3.5.1 Premium motorcycle demand and digital rider technologies to strengthen market growth
- 15.3.6 REST OF EUROPE
- 15.3.6.1 Urban electrification and premium riding demand to fuel market expansion
- 15.3.1 FRANCE
- 15.4 NORTH AMERICA
- 15.4.1 US
- 15.4.1.1 Premium motorcycle demand and OEM-led telematics innovation to strengthen market growth
- 15.4.2 CANADA
- 15.4.2.1 Premium motorcycle demand and OEM connectivity innovation to drive market growth
- 15.4.3 MEXICO
- 15.4.3.1 Expanding motorcycle usage and rising adoption of digitally equipped models to drive connected motorcycle demand
- 15.4.1 US
16 COMPETITIVE LANDSCAPE
- 16.1 OVERVIEW
- 16.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN
- 16.3 MARKET SHARE ANALYSIS, 2025
- 16.4 REVENUE ANALYSIS OF KEY PLAYERS
- 16.5 COMPANY VALUATION AND FINANCIAL METRICS
- 16.5.1 COMPANY VALUATION
- 16.5.2 FINANCIAL METRICS
- 16.6 BRAND COMPARISON
- 16.7 COMPANY EVALUATION MATRIX: KEY PLAYERS (OEMS), 2025
- 16.7.1 STARS
- 16.7.2 EMERGING LEADERS
- 16.7.3 PERVASIVE PLAYERS
- 16.7.4 PARTICIPANTS
- 16.7.5 COMPANY FOOTPRINT: KEY PLAYERS (OEMS), 2025
- 16.7.5.1 Company footprint
- 16.7.5.2 Hardware footprint
- 16.7.5.3 Region footprint
- 16.8 COMPANY EVALUATION MATRIX: KEY PLAYERS (TECHNOLOGY PROVIDERS), 2025
- 16.8.1 STARS
- 16.8.2 EMERGING LEADERS
- 16.8.3 PERVASIVE PLAYERS
- 16.8.4 PARTICIPANTS
- 16.8.5 COMPANY FOOTPRINT: KEY PLAYERS (TECHNOLOGY PROVIDERS), 2025
- 16.8.5.1 Company footprint
- 16.8.5.2 Hardware footprint
- 16.8.5.3 Region footprint
- 16.9 COMPETITIVE SCENARIO
- 16.9.1 PRODUCT LAUNCHES
- 16.9.2 DEALS
- 16.9.3 EXPANSIONS
- 16.9.4 OTHER DEVELOPMENTS
17 COMPANY PROFILES
- 17.1 KEY PLAYERS: SOFTWARE PROVIDERS
- 17.1.1 STARCOM SYSTEMS LLC
- 17.1.1.1 Business overview
- 17.1.1.2 Products offered
- 17.1.1.3 MnM view
- 17.1.1.3.1 Key strengths
- 17.1.1.3.2 Strategic choices
- 17.1.1.3.3 Weaknesses and competitive threats
- 17.1.2 COMODULE OU
- 17.1.2.1 Business overview
- 17.1.2.2 Products offered
- 17.1.2.3 Recent developments
- 17.1.2.3.1 Product launches
- 17.1.2.3.2 Deals
- 17.1.2.4 MnM view
- 17.1.2.4.1 Key strengths
- 17.1.2.4.2 Strategic choices
- 17.1.2.4.3 Weaknesses and competitive threats
- 17.1.3 KPIT TECHNOLOGIES LTD.
- 17.1.3.1 Business overview
- 17.1.3.2 Products offered
- 17.1.3.3 Recent developments
- 17.1.3.3.1 Deals
- 17.1.3.3.2 Expansions
- 17.1.3.4 MnM view
- 17.1.3.4.1 Key strengths
- 17.1.3.4.2 Strategic choices
- 17.1.3.4.3 Weaknesses and competitive threats
- 17.1.4 ITURAN GLOBAL
- 17.1.4.1 Business overview
- 17.1.4.2 Products offered
- 17.1.4.2.1 Deals
- 17.1.4.3 MnM view
- 17.1.4.3.1 Key strengths
- 17.1.4.3.2 Strategic choices
- 17.1.4.3.3 Weaknesses and competitive threats
- 17.1.5 E-NOVIA S.P.A
- 17.1.5.1 Business overview
- 17.1.5.2 Products offered
- 17.1.5.3 Recent developments
- 17.1.5.3.1 Deals
- 17.1.5.4 MnM view
- 17.1.5.4.1 Key strengths
- 17.1.5.4.2 Strategic choices
- 17.1.5.4.3 Weaknesses and competitive threats
- 17.1.1 STARCOM SYSTEMS LLC
- 17.2 KEY PLAYERS (OEMS)
- 17.2.1 YAMAHA MOTOR CO., LTD.
- 17.2.1.1 Business overview
- 17.2.1.2 Products offered
- 17.2.1.3 Recent developments
- 17.2.1.3.1 Product launches
- 17.2.1.3.2 Deals
- 17.2.1.4 MnM view
- 17.2.1.4.1 Key strengths
- 17.2.1.4.2 Strategic choices
- 17.2.1.4.3 Weaknesses and competitive threats
- 17.2.2 KAWASAKI MOTORS CORP.
- 17.2.2.1 Business overview
- 17.2.2.2 Products offered
- 17.2.2.3 Recent developments
- 17.2.2.3.1 Product launches
- 17.2.2.3.2 Deals
- 17.2.2.4 MnM view
- 17.2.2.4.1 Key strengths
- 17.2.2.4.2 Strategic choices
- 17.2.2.4.3 Weaknesses and competitive threats
- 17.2.3 SUZUKI MOTOR CORPORATION
- 17.2.3.1 Business overview
- 17.2.3.2 Products offered
- 17.2.3.3 Recent developments
- 17.2.3.3.1 Product launches
- 17.2.3.3.2 Deals
- 17.2.3.3.3 Other developments
- 17.2.3.4 MnM view
- 17.2.3.4.1 Key strengths
- 17.2.3.4.2 Strategic choices
- 17.2.3.4.3 Weaknesses and competitive threats
- 17.2.4 HARLEY-DAVIDSON
- 17.2.4.1 Business overview
- 17.2.4.2 Products offered
- 17.2.4.3 Recent developments
- 17.2.4.3.1 Product launches
- 17.2.4.3.2 Deals
- 17.2.4.3.3 Other developments
- 17.2.4.4 MnM view
- 17.2.4.4.1 Key strengths
- 17.2.4.4.2 Strategic choices
- 17.2.4.4.3 Weaknesses and competitive threats
- 17.2.5 BMW GROUP
- 17.2.5.1 Business overview
- 17.2.5.2 Products offered
- 17.2.5.3 Recent developments
- 17.2.5.3.1 Product launches
- 17.2.5.3.2 Deals
- 17.2.5.3.3 Other developments
- 17.2.5.4 MnM view
- 17.2.5.4.1 Key strengths
- 17.2.5.4.2 Strategic choices
- 17.2.5.4.3 Weaknesses and competitive threats
- 17.2.1 YAMAHA MOTOR CO., LTD.
- 17.3 KEY PLAYERS: HARDWARE PROVIDERS
- 17.3.1 ROBERT BOSCH GMBH
- 17.3.1.1 Business overview
- 17.3.1.2 Products offered
- 17.3.1.3 Recent developments
- 17.3.1.3.1 Product launches
- 17.3.1.3.2 Deals
- 17.3.1.3.3 Other developments
- 17.3.1.4 MnM view
- 17.3.1.4.1 Key strengths
- 17.3.1.4.2 Strategic choices
- 17.3.1.4.3 Weaknesses and competitive threats
- 17.3.2 CONTINENTAL AG
- 17.3.2.1 Business overview
- 17.3.2.2 Products offered
- 17.3.2.3 Recent developments
- 17.3.2.3.1 Product launches
- 17.3.2.3.2 Deals
- 17.3.2.4 MnM view
- 17.3.2.4.1 Key strengths
- 17.3.2.4.2 Strategic choices
- 17.3.2.4.3 Weaknesses and competitive threats
- 17.3.3 AUTOTALKS
- 17.3.3.1 Business overview
- 17.3.3.2 Products offered
- 17.3.3.3 Recent developments
- 17.3.3.3.1 Product launches
- 17.3.3.3.2 Deals
- 17.3.3.4 MnM view
- 17.3.3.4.1 Key strengths
- 17.3.3.4.2 Strategic choices
- 17.3.3.4.3 Weaknesses and competitive threats
- 17.3.4 PANASONIC CORPORATION
- 17.3.4.1 Business overview
- 17.3.4.2 Products offered
- 17.3.4.3 Recent developments
- 17.3.4.3.1 Product launches
- 17.3.4.3.2 Deals
- 17.3.4.4 MnM view
- 17.3.4.4.1 Key strengths
- 17.3.4.4.2 Strategic choices
- 17.3.4.4.3 Weaknesses and competitive threats
- 17.3.5 SIEMENS
- 17.3.5.1 Business overview
- 17.3.5.2 Products offered
- 17.3.5.3 Recent developments
- 17.3.5.3.1 Deals
- 17.3.5.4 MnM view
- 17.3.5.4.1 Key strengths
- 17.3.5.4.2 Strategic choices
- 17.3.5.4.3 Weaknesses and competitive threats
- 17.3.1 ROBERT BOSCH GMBH
- 17.4 KEY PLAYERS: SERVICE PLATFORM PROVIDERS
- 17.4.1 IBM
- 17.4.1.1 Business overview
- 17.4.1.2 Products offered
- 17.4.1.3 Recent developments
- 17.4.1.3.1 Deals
- 17.4.1.3.2 Other developments
- 17.4.1.4 MnM view
- 17.4.1.4.1 Key strengths
- 17.4.1.4.2 Strategic choices
- 17.4.1.4.3 Weaknesses and competitive threats
- 17.4.2 AMAZON
- 17.4.2.1 Business overview
- 17.4.2.2 Products offered
- 17.4.2.3 Recent developments
- 17.4.2.3.1 Deals
- 17.4.2.4 MnM view
- 17.4.2.4.1 Key strengths
- 17.4.2.4.2 Strategic choices
- 17.4.2.4.3 Weaknesses and competitive threats
- 17.4.3 GOOGLE LLC
- 17.4.3.1 Business overview
- 17.4.3.2 Products offered
- 17.4.3.3 Recent developments
- 17.4.3.3.1 Product launches
- 17.4.3.3.2 Deals
- 17.4.3.3.3 Other Developments
- 17.4.3.4 MnM view
- 17.4.3.4.1 Key strengths
- 17.4.3.4.2 Strategic choices
- 17.4.3.4.3 Weaknesses and competitive threats
- 17.4.4 APPLE INC.
- 17.4.4.1 Business overview
- 17.4.4.2 Products offered
- 17.4.4.3 Recent developments
- 17.4.4.3.1 Deals
- 17.4.4.4 MnM view
- 17.4.4.4.1 Key strengths
- 17.4.4.4.2 Strategic choices
- 17.4.4.4.3 Weaknesses and competitive threats
- 17.4.5 DXC TECHNOLOGY COMPANY
- 17.4.5.1 Business overview
- 17.4.5.2 Products offered
- 17.4.5.3 Recent developments
- 17.4.5.3.1 Product launches
- 17.4.5.3.2 Other developments
- 17.4.5.4 MnM view
- 17.4.5.4.1 Key strengths
- 17.4.5.4.2 Strategic choices
- 17.4.5.4.3 Weaknesses and competitive threats
- 17.4.1 IBM
- 17.5 KEY PLAYERS: NETWORK PROVIDERS
- 17.5.1 VODAFONE GROUP
- 17.5.1.1 Business overview
- 17.5.1.2 Products offered
- 17.5.1.3 Recent developments
- 17.5.1.3.1 Deals
- 17.5.1.3.2 Other developments
- 17.5.1.4 MnM view
- 17.5.1.4.1 Key strengths
- 17.5.1.4.2 Strategic choices
- 17.5.1.4.3 Weaknesses and competitive threats
- 17.5.2 VERIZON
- 17.5.2.1 Business overview
- 17.5.2.2 Products offered
- 17.5.2.3 Recent developments
- 17.5.2.3.1 Deals
- 17.5.2.3.2 Other developments
- 17.5.2.4 MnM view
- 17.5.2.4.1 Key strengths
- 17.5.2.4.2 Strategic choices
- 17.5.2.4.3 Weaknesses and competitive threats
- 17.5.3 TELEFONICA S.A.
- 17.5.3.1 Business overview
- 17.5.3.2 Products offered
- 17.5.3.3 Recent developments
- 17.5.3.3.1 Deals
- 17.5.3.3.2 Expansions
- 17.5.3.3.3 Other developments
- 17.5.3.4 MnM view
- 17.5.3.4.1 Key strengths
- 17.5.3.4.2 Strategic choices
- 17.5.3.4.3 Weaknesses and competitive threats
- 17.5.4 AERIS
- 17.5.4.1 Business overview
- 17.5.4.2 Products offered
- 17.5.4.3 Recent developments
- 17.5.4.3.1 Deals
- 17.5.4.4 MnM view
- 17.5.4.4.1 Key strengths
- 17.5.4.4.2 Strategic choices
- 17.5.4.4.3 Weaknesses and competitive threats
- 17.5.5 CHINA TELECOM GLOBAL LIMITED
- 17.5.5.1 Business overview
- 17.5.5.2 Products offered
- 17.5.5.3 Recent developments
- 17.5.5.3.1 Expansions
- 17.5.5.4 MnM view
- 17.5.5.4.1 Key strengths
- 17.5.5.4.2 Strategic choices
- 17.5.5.4.3 Weaknesses and competitive threats
- 17.5.1 VODAFONE GROUP
- 17.6 OTHER KEY PLAYERS (OEMS)
- 17.6.1 HERO MOTOCORP LTD.
- 17.6.2 HONDA MOTOR CO., LTD.
- 17.6.3 TRIUMPH MOTORCYCLES
- 17.6.4 TVS MOTORS COMPANY
- 17.6.5 KEEWAY
- 17.6.6 ROYAL ENFIELD
- 17.6.7 KTM AG
- 17.6.8 DUCATI MOTOR HOLDING S.P.A
- 17.6.9 IAV
- 17.6.10 FACOMSA
- 17.6.11 HARMAN INTERNATIONAL
- 17.6.12 TOMTOM INTERNATIONAL BV
- 17.6.13 NVIDIA CORPORATION
- 17.6.14 AIRTEL INDIA
- 17.6.15 QUALCOMM TECHNOLOGIES, INC.
- 17.6.16 NXP SEMICONDUCTORS
- 17.7 OTHER KEY PLAYERS (SOFTWARE & HARDWARE PROVIDERS)
- 17.7.1 ZERO MOTORCYCLES, INC.
- 17.7.2 TORK MOTORS
- 17.7.3 TE CONNECTIVITY
- 17.7.4 EMBIEN TECHNOLOGIES INDIA PVT LTD.
- 17.7.5 CALIMOTO GMBH
- 17.7.6 NAVINFO
- 17.7.7 INDIAN MOTORCYCLE INTERNATIONAL, LLC
- 17.7.8 THE FLOOW LIMITED
- 17.7.9 TELTONIKA
- 17.7.10 PARKOFON INC. DBA SHEEVA.AI
- 17.7.11 SIBROS TECHNOLOGIES INC.
- 17.7.12 TWILIO INC.
- 17.7.13 COSMO CONNECTED
- 17.7.14 CONCIRRUS LTD.
- 17.7.15 RIDE VISION
- 17.7.16 AMODO
- 17.7.17 BLUARMOR
- 17.7.18 COBI.BIKE
- 17.7.19 SENA TECHNOLOGIES INC.
- 17.7.20 YADEA TECHNOLOGY GROUP CO., LTD.
- 17.7.21 BAJAJ AUTO LTD.
- 17.7.22 NIU INTERNATIONAL
- 17.7.23 PIAGGIO & C. SPA
- 17.7.24 KYMCO
- 17.7.25 ATHER ENERGY
- 17.7.26 OLA ELECTRIC MOBILITY LTD.
18 RESEARCH METHODOLOGY
- 18.1 RESEARCH DATA
- 18.1.1 SECONDARY DATA
- 18.1.1.1 Major secondary sources
- 18.1.1.2 Key data from secondary sources
- 18.1.2 PRIMARY DATA
- 18.1.2.1 Primary interview participants
- 18.1.2.2 Breakdown of primary interviews
- 18.1.1 SECONDARY DATA
- 18.2 MARKET SIZE ESTIMATION
- 18.2.1 BOTTOM-UP APPROACH
- 18.2.2 TOP-DOWN APPROACH
- 18.3 DATA TRIANGULATION
- 18.4 RESEARCH ASSUMPTIONS
- 18.5 RESEARCH LIMITATIONS
19 APPENDIX
- 19.1 KEY INSIGHTS FROM INDUSTRY EXPERTS
- 19.2 DISCUSSION GUIDE
- 19.3 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 19.4 CUSTOMIZATION OPTIONS
- 19.4.1 COMPANY INFORMATION
- 19.4.1.1 Profiling of additional market players (Up to 5)
- 19.4.1 COMPANY INFORMATION
- 19.5 RELATED REPORTS
- 19.6 AUTHOR DETAILS
List of Tables
- TABLE 1 CONNECTED MOTORCYCLE MARKET DEFINITION, BY HARDWARE
- TABLE 2 CONNECTED MOTORCYCLE MARKET DEFINITION, BY PROPULSION TYPE
- TABLE 3 CONNECTED MOTORCYCLE MARKET DEFINITION, BY NETWORK TYPE
- TABLE 4 CONNECTED MOTORCYCLE MARKET DEFINITION, BY END USER
- TABLE 5 CONNECTED MOTORCYCLE MARKET DEFINITION, BY APPLICATION
- TABLE 6 CURRENCY EXCHANGE RATES, 2021-2025
- TABLE 7 CONNECTED MOTORCYCLE MARKET: BUSINESS MODELS
- TABLE 8 CONNECTED MOTORCYCLE MARKET: IMPACT OF MARKET DYNAMICS
- TABLE 9 GDP PERCENTAGE CHANGE, BY KEY COUNTRIES, 2022-2031
- TABLE 10 CONNECTED MOTORCYCLE MARKET: ROLE OF KEY PLAYERS IN ECOSYSTEM
- TABLE 11 IMPORT DATA FOR HS CODE 8711-COMPLIANT PRODUCTS, BY COUNTRY, 2022-2025 (USD BILLION)
- TABLE 12 EXPORT DATA FOR HS CODE 8711-COMPLIANT PRODUCTS, BY COUNTRY, 2022-2025 (USD BILLION)
- TABLE 13 KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 14 PATENT REGISTRATIONS, 2021-2026
- TABLE 15 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR CONNECTED MOTORCYCLES, BY PROPULSION TYPE
- TABLE 16 KEY BUYING CRITERIA FOR CONNECTED MOTORCYCLES, BY PROPULSION TYPE
- TABLE 17 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 18 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 19 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 20 CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 21 CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 22 OEM INTEGRATION OF EMBEDDED CONNECTIVITY ACROSS MOTORCYCLE PLATFORMS
- TABLE 23 CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 24 CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 25 OEM INTEGRATION OF EMBEDDED CONNECTIVITY ACROSS SCOOTER AND MOPED MODELS
- TABLE 26 CONNECTED SCOOTER/MOPED MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 27 CONNECTED SCOOTER/MOPED MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 28 CONNECTED MOTORCYCLE MARKET, BY HARDWARE, 2022-2025 (THOUSAND UNITS)
- TABLE 29 CONNECTED MOTORCYCLE MARKET, BY HARDWARE, 2026-2033 (THOUSAND UNITS)
- TABLE 30 EMBEDDED: CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 31 EMBEDDED: CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 32 INTEGRATED: CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 33 INTEGRATED: CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 34 CONNECTED MOTORCYCLE MARKET, BY PROPULSION TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 35 CONNECTED MOTORCYCLE MARKET, BY PROPULSION TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 36 BESTSELLING CONNECTED MOTORCYCLES BY KEY OEMS, 2025
- TABLE 37 ICE: CONNECTED ICE MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 38 ICE: CONNECTED ICE MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 39 < 125 CC: CONNECTED ICE MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 40 < 125 CC: CONNECTED ICE MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 41 126-300 CC: CONNECTED ICE MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 42 126-300 CC: CONNECTED ICE MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 43 > 300 CC: CONNECTED ICE MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 44 > 300 CC: CONNECTED ICE MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 45 EV: CONNECTED ELECTRIC MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 46 EV: CONNECTED ELECTRIC MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 47 < 3 KW: CONNECTED ELECTRIC MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 48 < 3 KW: CONNECTED ELECTRIC MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 49 3-7 KW: CONNECTED ELECTRIC MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 50 3-7 KW: CONNECTED ELECTRIC MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 51 > 7 KW: CONNECTED ELECTRIC MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 52 > 7 KW: CONNECTED ELECTRIC MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 53 CONNECTED MOTORCYCLE MARKET, BY NETWORK TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 54 CONNECTED MOTORCYCLE MARKET, BY NETWORK TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 55 3G/4G: CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 56 3G/4G: CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 57 5G: CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 58 5G: CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 59 OTHERS: CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 60 CONNECTED MOTORCYCLE MARKET, BY END USER, 2022-2025 (THOUSAND UNITS)
- TABLE 61 CONNECTED MOTORCYCLE MARKET, BY END USER, 2026-2033 (THOUSAND UNITS)
- TABLE 62 COMPANIES PROVIDING RIDE-HAILING SERVICES ON MOTORCYCLES
- TABLE 63 PRIVATE: CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 64 PRIVATE: CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 65 COMMERCIAL: CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 66 COMMERCIAL: CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 67 CONNECTED MOTORCYCLE MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 68 CONNECTED MOTORCYCLE MARKET, BY APPLICATION, 2026-2033 (USD MILLION)
- TABLE 69 SAFETY & SECURITY: CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 70 SAFETY & SECURITY: CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 71 NAVIGATION: CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 72 NAVIGATION: CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 73 VEHICLE HEALTH & DIAGNOSTICS: CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 74 VEHICLE HEALTH & DIAGNOSTICS: CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 75 INFOTAINMENT & COMMUNICATION: CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 76 INFOTAINMENT & COMMUNICATION: CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 77 OTHER APPLICATIONS: CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 78 OTHER APPLICATIONS: CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 79 CONNECTED MOTORCYCLE MARKET, BY REGION, 2022-2025 (THOUSAND UNITS)
- TABLE 80 CONNECTED MOTORCYCLE MARKET, BY REGION, 2026-2033 (THOUSAND UNITS)
- TABLE 81 CONNECTIVITY PLANS OFFERED BY LEADING OEMS IN ASIA PACIFIC
- TABLE 82 ASIA PACIFIC: CONNECTED MOTORCYCLE MARKET, BY COUNTRY, 2022-2025 (THOUSAND UNITS)
- TABLE 83 ASIA PACIFIC: CONNECTED MOTORCYCLE MARKET, BY COUNTRY, 2026-2033 (THOUSAND UNITS)
- TABLE 84 CHINA: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 85 CHINA: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 86 INDIA: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 87 INDIA: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 88 JAPAN: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 89 JAPAN: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 90 SOUTH KOREA: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 91 SOUTH KOREA: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 92 PHILIPPINES: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 93 PHILIPPINES: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 94 INDONESIA: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 95 INDONESIA: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 96 VIETNAM: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 97 VIETNAM: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 98 THAILAND: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 99 THAILAND: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 100 REST OF ASIA PACIFIC: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 101 REST OF ASIA PACIFIC: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 102 EUROPE: CONNECTED MOTORCYCLE MARKET, BY COUNTRY, 2022-2025 (THOUSAND UNITS)
- TABLE 103 EUROPE: CONNECTED MOTORCYCLE MARKET, BY COUNTRY, 2026-2033 (THOUSAND UNITS)
- TABLE 104 FRANCE: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 105 FRANCE: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 106 GERMANY: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 107 GERMANY: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 108 ITALY: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 109 ITALY: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 110 SPAIN: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 111 SPAIN: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 112 UK: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 113 UK: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 114 REST OF EUROPE: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 115 REST OF EUROPE: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 116 NORTH AMERICA: CONNECTED MOTORCYCLE MARKET, BY COUNTRY, 2022-2025 (THOUSAND UNITS)
- TABLE 117 NORTH AMERICA: CONNECTED MOTORCYCLE MARKET, BY COUNTRY, 2026-2033 (THOUSAND UNITS)
- TABLE 118 US: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 119 US: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 120 CANADA: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 121 CANADA: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 122 MEXICO: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 123 MEXICO: CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026-2033 (THOUSAND UNITS)
- TABLE 124 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS
- TABLE 125 CONNECTED MOTORCYCLE MARKET (OEMS): DEGREE OF COMPETITION, 2025
- TABLE 126 CONNECTED MOTORCYCLE MARKET (SOLUTION PROVIDERS): DEGREE OF COMPETITION, 2025
- TABLE 127 CONNECTED MOTORCYCLE MARKET (OEMS): HARDWARE FOOTPRINT
- TABLE 128 CONNECTED MOTORCYCLE MARKET (OEMS): REGION FOOTPRINT
- TABLE 129 CONNECTED MOTORCYCLE MARKET: HARDWARE FOOTPRINT
- TABLE 130 CONNECTED MOTORCYCLE MARKET: REGION FOOTPRINT
- TABLE 131 CONNECTED MOTORCYCLE MARKET: PRODUCT LAUNCHES, 2023-2026
- TABLE 132 CONNECTED MOTORCYCLE MARKET: DEALS, 2023-2026
- TABLE 133 CONNECTED MOTORCYCLE MARKET: EXPANSIONS, 2023-2026
- TABLE 134 CONNECTED MOTORCYCLE MARKET: OTHER DEVELOPMENTS, 2023-2026
- TABLE 135 STARCOM SYSTEMS LLC: COMPANY OVERVIEW
- TABLE 136 STARCOM SYSTEMS LLC: PRODUCTS OFFERED
- TABLE 137 COMODULE OU: COMPANY OVERVIEW
- TABLE 138 COMODULE OU: PRODUCTS OFFERED
- TABLE 139 COMODULE OU: PRODUCT LAUNCHES
- TABLE 140 COMODULE OU: DEALS
- TABLE 141 KPIT TECHNOLOGIES LTD.: COMPANY OVERVIEW
- TABLE 142 KPIT TECHNOLOGIES LTD.: PRODUCTS OFFERED
- TABLE 143 KPIT TECHNOLOGIES LTD.: DEALS
- TABLE 144 KPIT TECHNOLOGIES LTD.: EXPANSIONS
- TABLE 145 ITURAN GLOBAL: COMPANY OVERVIEW
- TABLE 146 ITURAN GLOBAL: PRODUCTS OFFERED
- TABLE 147 ITURAN GLOBAL: DEALS
- TABLE 148 E-NOVIA S.P.A: COMPANY OVERVIEW
- TABLE 149 E-NOVIA S.P.A: PRODUCTS OFFERED
- TABLE 150 E-NOVIA S.P.A: DEALS
- TABLE 151 YAMAHA MOTOR CO., LTD.: COMPANY OVERVIEW
- TABLE 152 YAMAHA MOTOR CO., LTD.: PRODUCTS OFFERED
- TABLE 153 YAMAHA MOTOR CO., LTD.: PRODUCT LAUNCHES
- TABLE 154 YAMAHA MOTOR CO., LTD.: DEALS
- TABLE 155 YAMAHA MOTOR COMPANY: OTHER DEVELOPMENTS
- TABLE 156 KAWASAKI MOTORS CORP.: COMPANY OVERVIEW
- TABLE 157 KAWASAKI MOTORS CORP.: PRODUCTS OFFERED
- TABLE 158 KAWASAKI MOTORS CORP.: PRODUCT LAUNCHES
- TABLE 159 KAWASAKI MOTORS CORP.: DEALS
- TABLE 160 KAWASAKI MOTORS CORP.: OTHER DEVELOPMENTS
- TABLE 161 SUZUKI MOTOR CORPORATION: COMPANY OVERVIEW
- TABLE 162 SUZUKI MOTOR CORPORATION: PRODUCTS OFFERED
- TABLE 163 SUZUKI MOTOR CORPORATION: PRODUCT LAUNCHES
- TABLE 164 SUZUKI MOTOR CORPORATION: DEALS
- TABLE 165 SUZUKI MOTOR CORPORATION: OTHER DEVELOPMENTS
- TABLE 166 HARLEY-DAVIDSON: COMPANY OVERVIEW
- TABLE 167 HARLEY-DAVIDSON: PRODUCTS OFFERED
- TABLE 168 HARLEY-DAVIDSON: PRODUCT LAUNCHES
- TABLE 169 HARLEY-DAVIDSON: DEALS
- TABLE 170 HARLEY-DAVIDSON: OTHER DEVELOPMENTS
- TABLE 171 BMW GROUP: COMPANY OVERVIEW
- TABLE 172 BMW GROUP: PRODUCTS OFFERED
- TABLE 173 BMW GROUP: PRODUCT LAUNCHES
- TABLE 174 BMW GROUP: DEALS
- TABLE 175 BMW GROUP: OTHER DEVELOPMENTS
- TABLE 176 ROBERT BOSCH GMBH: COMPANY OVERVIEW
- TABLE 177 ROBERT BOSCH GMBH: PRODUCTS OFFERED
- TABLE 178 ROBERT BOSCH GMBH: PRODUCT LAUNCHES
- TABLE 179 ROBERT BOSCH GMBH: DEALS
- TABLE 180 ROBERT BOSCH GMBH: OTHER DEVELOPMENTS
- TABLE 181 CONTINENTAL AG: COMPANY OVERVIEW
- TABLE 182 CONTINENTAL AG: PRODUCTS OFFERED
- TABLE 183 CONTINENTAL AG: PRODUCT LAUNCHES
- TABLE 184 CONTINENTAL AG: DEALS
- TABLE 185 AUTOTALKS: COMPANY OVERVIEW
- TABLE 186 AUTOTALKS: PRODUCTS OFFERED
- TABLE 187 AUTOTALKS: PRODUCT LAUNCHES
- TABLE 188 AUTOTALKS: DEALS
- TABLE 189 PANASONIC CORPORATION: COMPANY OVERVIEW
- TABLE 190 PANASONIC CORPORATION: PRODUCTS OFFERED
- TABLE 191 PANASONIC CORPORATION: PRODUCT LAUNCHES
- TABLE 192 PANASONIC CORPORATION: DEALS
- TABLE 193 SIEMENS: COMPANY OVERVIEW
- TABLE 194 SIEMENS: PRODUCTS OFFERED
- TABLE 195 SIEMENS: DEALS
- TABLE 196 IBM: COMPANY OVERVIEW
- TABLE 197 IBM: PRODUCTS OFFERED
- TABLE 198 IBM: DEALS
- TABLE 199 IBM: OTHERS
- TABLE 200 AMAZON: COMPANY OVERVIEW
- TABLE 201 AMAZON: PRODUCTS OFFERED
- TABLE 202 AMAZON: DEALS
- TABLE 203 GOOGLE LLC: COMPANY OVERVIEW
- TABLE 204 GOOGLE LLC: PRODUCTS OFFERED
- TABLE 205 GOOGLE LLC: PRODUCT LAUNCHES
- TABLE 206 GOOGLE LLC: DEALS
- TABLE 207 GOOGLE LLC: OTHERS
- TABLE 208 APPLE INC.: COMPANY OVERVIEW
- TABLE 209 APPLE INC.: PRODUCTS OFFERED
- TABLE 210 APPLE INC.: DEALS
- TABLE 211 DXC TECHNOLOGY COMPANY: COMPANY OVERVIEW
- TABLE 212 DXC TECHNOLOGY COMPANY: PRODUCTS OFFERED
- TABLE 213 DXC TECHNOLOGY: PRODUCT LAUNCHES
- TABLE 214 DXC TECHNOLOGY: OTHER DEVELOPMENTS
- TABLE 215 VODAFONE GROUP: COMPANY OVERVIEW
- TABLE 216 VODAFONE GROUP: PRODUCTS OFFERED
- TABLE 217 VODAFONE: DEALS
- TABLE 218 VODAFONE: OTHER DEVELOPMENTS
- TABLE 219 VERIZON: COMPANY OVERVIEW
- TABLE 220 VERIZON: PRODUCTS OFFERED
- TABLE 221 VERIZON: DEALS
- TABLE 222 VERIZON: OTHER DEVELOPMENTS
- TABLE 223 TELEFONICA S.A.: COMPANY OVERVIEW
- TABLE 224 TELEFONICA S.A.: PRODUCTS OFFERED
- TABLE 225 TELEFONICA S.A.: DEALS
- TABLE 226 TELEFONICA S.A.: EXPANSIONS
- TABLE 227 TELEFONICA S.A: OTHER DEVELOPMENTS
- TABLE 228 AERIS: COMPANY OVERVIEW
- TABLE 229 AERIS: PRODUCTS OFFERED
- TABLE 230 AERIS: DEALS
- TABLE 231 CHINA TELECOM GLOBAL LIMITED: COMPANY OVERVIEW
- TABLE 232 CHINA TELECOM GLOBAL LIMITED: PRODUCTS OFFERED
- TABLE 233 CHINA TELECOM GLOBAL LIMITED: EXPANSIONS
- TABLE 234 HERO MOTOCORP LTD.: COMPANY OVERVIEW
- TABLE 235 HONDA MOTOR CO., LTD.: COMPANY OVERVIEW
- TABLE 236 TRIUMPH MOTORCYCLES: COMPANY OVERVIEW
- TABLE 237 TVS MOTORS COMPANY: COMPANY OVERVIEW
- TABLE 238 KEEWAY: COMPANY OVERVIEW
- TABLE 239 ROYAL ENFIELD: COMPANY OVERVIEW
- TABLE 240 KTM AG: COMPANY OVERVIEW
- TABLE 241 DUCATI MOTOR HOLDING S.P.A.: COMPANY OVERVIEW
- TABLE 242 IAV: COMPANY OVERVIEW
- TABLE 243 FACOMSA: COMPANY OVERVIEW
- TABLE 244 HARMAN INTERNATIONAL: COMPANY OVERVIEW
- TABLE 245 TOMTOM INTERNATIONAL BV: COMPANY OVERVIEW
- TABLE 246 NVIDIA CORPORATION: COMPANY OVERVIEW
- TABLE 247 AIRTEL INDIA: COMPANY OVERVIEW
- TABLE 248 QUALCOMM TECHNOLOGIES, INC.: COMPANY OVERVIEW
- TABLE 249 NXP SEMICONDUCTORS: COMPANY OVERVIEW
- TABLE 250 ZERO MOTORCYCLES, INC.: COMPANY OVERVIEW
- TABLE 251 TORK MOTORS: COMPANY OVERVIEW
- TABLE 252 TE CONNECTIVITY: COMPANY OVERVIEW
- TABLE 253 EMBIEN TECHNOLOGIES INDIA PVT LTD.: COMPANY OVERVIEW
- TABLE 254 CALIMOTO GMBH: COMPANY OVERVIEW
- TABLE 255 NAVINFO: COMPANY OVERVIEW
- TABLE 256 INDIAN MOTORCYCLE INTERNATIONAL, LLC: COMPANY OVERVIEW
- TABLE 257 THE FLOOW LIMITED: COMPANY OVERVIEW
- TABLE 258 TELTONIKA: COMPANY OVERVIEW
- TABLE 259 PARKOFON INC. DBA SHEEVA.AI: COMPANY OVERVIEW
- TABLE 260 SIBROS TECHNOLOGIES INC.: COMPANY OVERVIEW
- TABLE 261 TWILIO INC.: COMPANY OVERVIEW
- TABLE 262 COSMO CONNECTED: COMPANY OVERVIEW
- TABLE 263 CONCIRRUS LTD.: COMPANY OVERVIEW
- TABLE 264 RIDE VISION: COMPANY OVERVIEW
- TABLE 265 AMODO: COMPANY OVERVIEW
- TABLE 266 BLUARMOR: COMPANY OVERVIEW
- TABLE 267 COBI.BIKE: COMPANY OVERVIEW
- TABLE 268 SENA TECHNOLOGIES INC.: COMPANY OVERVIEW
- TABLE 269 YADEA TECHNOLOGY GROUP CO., LTD.: COMPANY OVERVIEW
- TABLE 270 BAJAJ AUTO LTD.: COMPANY OVERVIEW
- TABLE 271 NIU INTERNATIONAL: COMPANY OVERVIEW
- TABLE 272 PIAGGIO & C. SPA: COMPANY OVERVIEW
- TABLE 273 KYMCO: COMPANY OVERVIEW
- TABLE 274 ATHER ENERGY: COMPANY OVERVIEW
- TABLE 275 OLA ELECTRIC MOBILITY LTD.: BUSINESS OVERVIEW
List of Figures
- FIGURE 1 MARKET SCENARIO
- FIGURE 2 CONNECTED MOTORCYCLE MARKET, 2022-2033
- FIGURE 3 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN CONNECTED MOTORCYCLE MARKET, 2023-2026
- FIGURE 4 DISRUPTIONS INFLUENCING GROWTH OF CONNECTED MOTORCYCLE MARKET
- FIGURE 5 HIGH-GROWTH SEGMENTS IN CONNECTED MOTORCYCLE MARKET, 2026-2033
- FIGURE 6 ASIA PACIFIC TO REGISTER HIGHEST CAGR IN CONNECTED MOTORCYCLE MARKET DURING FORECAST PERIOD
- FIGURE 7 RISING DEMAND FOR CONNECTED TWO-WHEELERS TO DRIVE MARKET GROWTH
- FIGURE 8 SCOOTER/MOPED SEGMENT TO LEAD MARKET DURING FORECAST PERIOD
- FIGURE 9 EMBEDDED SEGMENT TO REGISTER HIGHER CAGR DURING FORECAST PERIOD
- FIGURE 10 ICE SEGMENT TO LEAD MARKET DURING FORECAST PERIOD
- FIGURE 11 3G/4G SEGMENT TO DOMINATE MARKET DURING FORECAST PERIOD
- FIGURE 12 PRIVATE SEGMENT TO LEAD MARKET DURING FORECAST PERIOD
- FIGURE 13 SAFETY & SECURITY SEGMENT TO LEAD MARKET DURING FORECAST PERIOD
- FIGURE 14 ASIA PACIFIC TO ACCOUNT FOR LARGEST MARKET SHARE IN 2026
- FIGURE 15 CONNECTED MOTORCYCLE MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 16 ELECTRIC MOPED/SCOOTERS AND MOTORCYCLE SALES, 2022-2025
- FIGURE 17 CONNECTIVITY APPLICATIONS BY KEY TWO-WHEELER OEMS
- FIGURE 18 CONNECTED MOTORCYCLE MARKET: SUPPLY CHAIN ANALYSIS
- FIGURE 19 CONNECTED MOTORCYCLE MARKET: ECOSYSTEM MAPPING
- FIGURE 20 AVERAGE ANNUAL SUBSCRIPTION PRICE OF CONNECTED MOTORCYCLE SYSTEMS OF KEY PLAYERS, 2024-2026
- FIGURE 21 AVERAGE SELLING PRICE TREND OF CONNECTED MOTORCYCLE SYSTEM, BY REGION (2024-2026)
- FIGURE 22 IMPORT DATA FOR HS CODE 8711-COMPLIANT PRODUCTS, BY COUNTRY, 2022-2025
- FIGURE 23 EXPORT DATA FOR HS CODE 8711-COMPLIANT PRODUCTS, BY COUNTRY, 2022-2025
- FIGURE 24 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESSES
- FIGURE 25 INVESTMENT AND FUNDING, 2022-2025
- FIGURE 26 DIRECT IMPACT OF ISRAEL-IRAN CONFLICT ON AUTOMOTIVE SECTOR
- FIGURE 27 INDIRECT IMPACT OF ISRAEL-IRAN CONFLICT ON AUTOMOTIVE SECTOR
- FIGURE 28 SECTORS IMPACTED BY EU-INDIA FTA DEAL
- FIGURE 29 IMPACT ON IMPORT DUTY FOR EUROPEAN VEHICLES DUE TO EU-INDIA FTA
- FIGURE 30 IMPACT ON OEMS AND SUPPLIERS IN INDIA DUE TO EU-INDIA FTA
- FIGURE 31 IMPACT ON AUTOMOTIVE COMPONENT TRADE DUE TO EU-INDIA FTA
- FIGURE 32 CONNECTED MOTORCYCLE TECHNOLOGY ROADMAP
- FIGURE 33 PATENTS PUBLISHED, 2015-2026
- FIGURE 34 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR CONNECTED MOTORCYCLES, BY PROPULSION TYPE
- FIGURE 35 KEY BUYING CRITERIA FOR CONNECTED MOTORCYCLES, BY PROPULSION TYPE
- FIGURE 36 CONNECTED MOTORCYCLE MARKET, BY TWO-WHEELER TYPE, 2026 VS. 2033
- FIGURE 37 CONNECTED MOTORCYCLE MARKET, BY HARDWARE, 2026 VS 2033
- FIGURE 38 CONNECTED MOTORCYCLE MARKET, BY PROPULSION TYPE, 2026 VS 2033
- FIGURE 39 CONNECTED MOTORCYCLE MARKET, BY NETWORK TYPE, 2026 VS 2033
- FIGURE 40 CONNECTED MOTORCYCLE MARKET, BY END USER, 2026 VS 2033
- FIGURE 41 CONNECTED MOTORCYCLE MARKET, BY APPLICATION, 2026 VS 2033
- FIGURE 42 CONNECTED MOTORCYCLE MARKET, BY REGION, 2026 VS. 2033
- FIGURE 43 ASIA PACIFIC: CONNECTED MOTORCYCLE MARKET SNAPSHOT
- FIGURE 44 EUROPE: CONNECTED MOTORCYCLE MARKET SNAPSHOT
- FIGURE 45 NORTH AMERICA: CONNECTED MOTORCYCLE MARKET SNAPSHOT
- FIGURE 46 MARKET SHARE ANALYSIS OF KEY PLAYERS (OEMS), 2025
- FIGURE 47 MARKET SHARE ANALYSIS OF KEY PLAYERS (SOLUTION PROVIDERS), 2025
- FIGURE 48 REVENUE ANALYSIS OF KEY PLAYERS (OEMS), 2021-2025
- FIGURE 49 REVENUE ANALYSIS OF KEY PLAYERS (TECHNOLOGY PROVIDERS), 2021-2025
- FIGURE 50 COMPANY VALUATION (OEMS), 2025
- FIGURE 51 COMPANY VALUATION (TECHNOLOGY PROVIDERS), 2025
- FIGURE 52 FINANCIAL METRICS (OEMS), 2025
- FIGURE 53 FINANCIAL METRICS (TECHNOLOGY PROVIDERS), 2025
- FIGURE 54 BRAND COMPARISON (OEMS)
- FIGURE 55 BRAND COMPARISON (TECHNOLOGY PROVIDERS)
- FIGURE 56 CONNECTED MOTORCYCLE MARKET: COMPANY EVALUATION MATRIX (OEMS), 2025
- FIGURE 57 CONNECTED MOTORCYCLE MARKET: COMPANY FOOTPRINT
- FIGURE 58 CONNECTED MOTORCYCLE MARKET: COMPANY EVALUATION MATRIX (TECHNOLOGY PROVIDERS), 2025
- FIGURE 59 CONNECTED MOTORCYCLE MARKET: COMPANY FOOTPRINT
- FIGURE 60 KPIT TECHNOLOGIES LTD.: COMPANY SNAPSHOT
- FIGURE 61 ITURAN GLOBAL: COMPANY SNAPSHOT
- FIGURE 62 YAMAHA MOTOR CO., LTD.: COMPANY SNAPSHOT
- FIGURE 63 KAWASAKI MOTORS CORP.: COMPANY SNAPSHOT
- FIGURE 64 SUZUKI MOTOR CORPORATION: COMPANY SNAPSHOT
- FIGURE 65 HARLEY-DAVIDSON: COMPANY SNAPSHOT
- FIGURE 66 BMW GROUP: COMPANY SNAPSHOT
- FIGURE 67 ROBERT BOSCH GMBH: COMPANY SNAPSHOT
- FIGURE 68 CONTINENTAL AG: COMPANY SNAPSHOT
- FIGURE 69 PANASONIC CORPORATION: COMPANY SNAPSHOT
- FIGURE 70 SIEMENS: COMPANY SNAPSHOT
- FIGURE 71 IBM: COMPANY SNAPSHOT
- FIGURE 72 AMAZON: COMPANY SNAPSHOT
- FIGURE 73 GOOGLE LLC: COMPANY SNAPSHOT
- FIGURE 74 APPLE INC.: COMPANY SNAPSHOT
- FIGURE 75 DXC TECHNOLOGY COMPANY: COMPANY SNAPSHOT
- FIGURE 76 VODAFONE GROUP: COMPANY SNAPSHOT
- FIGURE 77 VERIZON: COMPANY SNAPSHOT
- FIGURE 78 TELEFONICA S.A.: COMPANY SNAPSHOT
- FIGURE 79 CHINA TELECOM GLOBAL LIMITED: COMPANY SNAPSHOT
- FIGURE 80 RESEARCH DESIGN
- FIGURE 81 RESEARCH DESIGN MODEL
- FIGURE 82 MARKET SIZE ESTIMATION: HYPOTHESIS BUILDING
- FIGURE 83 BOTTOM-UP APPROACH
- FIGURE 84 TOP-DOWN APPROACH
- FIGURE 85 CONNECTED MOTORCYCLE MARKET: DATA TRIANGULATION

