PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2151262

PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2151262
Waste Heat Recovery Systems Market by Application (Preheating, Steam & Electricity Generation, Others), End-use Industry (Petroleum Refining, Metal Production, Cement, Chemical, Paper & Pulp, Other End-use Industry), & Region - Global Forecast to 2031
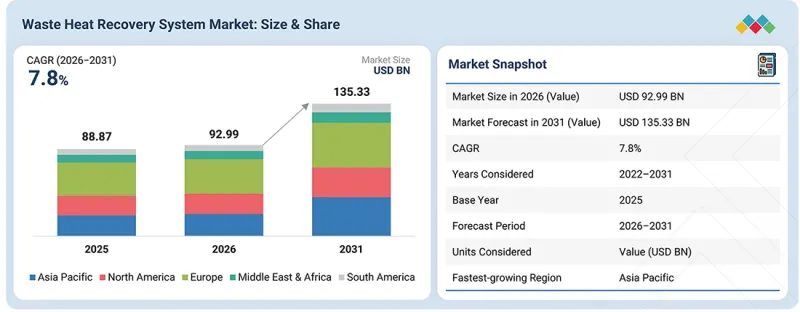
The waste heat recovery system market is projected to reach USD 135.33 billion in 2031 from USD 92.99 billion in 2026, at a CAGR of 7.8%.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) and Volume (Ton) |
| Segments | Type, End-use Industry, and Region |
| Regions covered | Type, Composition, Application, and Region |
The increasing demand is attributed to compounding global pressures from skyrocketing industrial energy tariffs and strict Scope 1 emission penalties, which force factories to treat thermal recycling as a survival necessity for protecting operational margins.
"The preheating application segment is projected to account for the second-largest market share throughout the forecast period"
The preheating application segment is projected to account for the second-largest share of the waste heat recovery systems market during the forecast period due to its wide usage in energy-intensive manufacturing activities. Preheating utilizes the energy extracted from flue gases generated by furnaces, exhaust emissions, and kiln smoke, along with other high-temperature sources, to elevate the temperature of combustion air, feed water, raw materials, and other inputs prior to their progression to subsequent stages in the production process. This recovery process enhances overall system efficiency by maximizing heat utilization and reducing energy consumption in subsequent operations. This will reduce the need for primary fuel for achieving temperature for the operation, which results in greater thermal efficiency of the process in general. Industrial facilities engaged in cement, steel production, oil refining, chemical processing, glass manufacturing, and non-ferrous metal processing have significant potential for integrating preheating technologies. These operations consistently generate high-temperature emissions, creating opportunities to capture and utilize this thermal energy. Various advanced technologies are available for preheating, enabling effective solutions for both retrofitting existing systems and designing new installations. Since it does not contribute energy back to the system that has been expended, it has a reduced reliance on supplementary devices.
"The chemicals industry is projected to capture the second-largest market share over the forecast period."
The chemicals industry is projected to secure the second-largest share of the waste heat recovery systems market during the forecast period, due to the ongoing nature and resource-intensive characteristics of chemical production processes. Chemical production facilities are able to produce large amounts of heat that can be recovered from engines, reactors, furnaces, crackers, boilers, and exhaust systems. The recovered thermal energy can be harnessed with the help of economizers, heat recovery boilers, heat exchangers, and steam generators and utilized for pre-heating of raw materials, generating steam, heating processes or generating electricity in the future. The operations of petrol products manufacturing plants can be seen as an ideal match for WHR systems, since such facilities provide constant availability of heat flow and high effectiveness of equipment. Another significant aspect of this segment is that the possibility of heat integration allows recovered thermal energy from one unit to be used in other production units, leading to lower fuel costs. In addition, some existing facilities have become highly energy-efficient recently and reduced operational costs with minimum changes to their production processes. The complex of continuously running production processes with high process temperatures, continuous production, and multiple internal heat-demand points is expected to sustain significant WHR deployment, supporting the segment's position as the second-largest end-use industry.
"Asia Pacific is projected to be the second-largest market for heat recovery systems during the forecast period."
Asia Pacific is expected to hold the second-largest share of the waste heat recovery systems market during the evaluation period due to its large manufacturing base and energy-intensive industries. Countries such as China, India, Japan, South Korea, and Southeast Asia have capable production of cement, steel, chemicals, and petroleum products, along with the production of paper that results in the realization of a large amount of heat. The continuous operation of kilns, furnaces, boilers, and processes provides enough heat for the waste heat boilers, heat exchangers, economizers, and organic Rankine cycle systems. Further increasing production in the region encourages manufacturers to enhance their fuel consumption and lower their energy losses. Moreover, the modernization of old production facilities creates possibilities for retrofitting installations, while new plants have opportunities to utilize WHR in their design. Cement and metal industries are especially essential due to the temperature profile of exhaust gases. Increasing electricity requirements result in a growing need to use waste heat to generate electricity and steam. These trends will keep the deployment of WHR systems across Asia Pacific.
The study contains insights from various industry experts, from component suppliers to OEMs. The breakdown of the primary participants is as follows:
By Company Type: Tier 1: 25%, Tier 2: 42%, and Tier 3: 33%
By Designation: C-level Executives: 20%, Directors: 30%, and Others: 50%
By Region: North America: 20%, Europe: 10%, Asia Pacific: 40%, South America: 10%, and Middle East & Africa: 20%
Notes: Other designations include sales, marketing, and product managers.
Tier 1: >USD 1 billion; Tier 2: USD 500 million-1 billion; and Tier 3: <USD 500 million
Companies Covered: Siemens Energy AG (Germany), GE Vernova Inc. (US), Mitsubishi Heavy Industries, Ltd. (Japan), ABB Ltd. (Switzerland), Shanghai Electric Group Co., Ltd. (China), Kawasaki Heavy Industries, Ltd. (Japan), Doosan Enerbility Co., Ltd. (South Korea), IHI Corporation (Japan), Wartsila Corporation (Finland), Bharat Heavy Electricals Limited (BHEL) (India), among others, are covered in the report.
The study includes an in-depth competitive analysis of these key players in the waste heat recovery system market, with their company profiles, recent developments, and key market strategies.
Research Coverage
This research report categorizes the waste heat recovery system market based on application (preheating, steam & electricity generation, other applications), end-use industry (petroleum refining, metal production, cement, chemical, paper & pulp, other end-use industries), region (North America, Europe, Asia Pacific, Middle East & Africa, and South America). The report's scope covers detailed information regarding the drivers, restraints, challenges, and opportunities influencing the growth of the waste heat recovery system market. A detailed analysis of the key industry players has been done to provide insights into their business overview, products offered, and key strategies, such as partnerships, collaborations, product launches, expansions, and acquisitions, associated with the waste heat recovery system market. This report covers a competitive analysis of upcoming startups in the waste heat recovery system ecosystem.
Reasons to Buy the Report
The report will offer market leaders/new entrants information on the closest approximations of the revenue numbers for the overall waste heat recovery system market and the subsegments. This report will help stakeholders understand the competitive landscape, gain more insights into positioning their businesses better, and plan suitable go-to-market strategies. The report will help stakeholders understand the pulse of the market and provide them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following points:
Analysis of key drivers (rising energy costs across energy-intensive industries, increasing recovery from steel furnace and reheating operations, increasing focus of cement and metals producers on emission reduction), restraints (high capital requirement for installing waste heat recovery systems, complex integration of waste heat recovery systems with existing plant infrastructure), opportunities (increasing integration of waste heat recovery systems with data center cooling infrastructure, growing deployment of industrial heat pumps for waste heat valorization, rising deployment of orc systems for low- and medium-temperature waste heat recovery), and challenges (corrosion and fouling risks in high-temperature waste heat recovery equipment, fluctuating production loads causing variations in waste heat generation).
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product & service launches in the waste heat recovery system market.
- Market Development: Comprehensive information about profitable markets - the report analyzes the waste heat recovery system market across varied regions.
Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the waste heat recovery system market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players: Siemens Energy AG (Germany), GE Vernova Inc. (US), Mitsubishi Heavy Industries, Ltd. (Japan), ABB Ltd. (Switzerland), Shanghai Electric Group Co., Ltd. (China), Kawasaki Heavy Industries, Ltd. (Japan), Doosan Enerbility Co., Ltd. (South Korea), IHI Corporation (Japan), Wartsila Corporation (Finland), Bharat Heavy Electricals Limited (BHEL) (India).
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED & REGIONAL SCOPE
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.3.5 STAKEHOLDERS
- 1.4 SUMMARY OF STRATEGIC CHANGES IN MARKET
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN WASTE HEAT RECOVERY SYSTEM MARKET
- 3.2 WASTE HEAT RECOVERY SYSTEM MARKET, BY APPLICATION AND END-USE INDUSTRY
- 3.3 WASTE HEAT RECOVERY SYSTEM MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising energy costs across energy-intensive industries
- 4.2.1.2 Increasing recovery from steel furnace and reheating operations
- 4.2.1.3 Increasing focus of cement and metals producers on emission reduction
- 4.2.2 RESTRAINTS
- 4.2.2.1 High capital requirement for installing waste heat recovery systems
- 4.2.2.2 Complex integration of waste heat recovery systems with existing plant infrastructure
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Increasing integration of waste heat recovery systems with data center cooling infrastructure
- 4.2.3.2 Growing deployment of industrial heat pumps for waste heat valorization
- 4.2.3.3 Rising deployment of ORC systems for low- and medium-temperature waste heat recovery
- 4.2.4 CHALLENGES
- 4.2.4.1 Corrosion and fouling risks in high-temperature waste heat recovery equipment
- 4.2.4.2 Fluctuating production loads cause variations in waste heat generation
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS
- 4.3.1.1 Economically viable recovery of low temperature waste heat below 150°C
- 4.3.1.2 Long-life high-temperature equipment under corrosive and fouling conditions
- 4.3.2 WHITE SPACES
- 4.3.2.1 Modular WHRS platforms designed for highly variable industrial production loads
- 4.3.2.2 Integrated waste heat to process heat systems that monetize low-grade energy
- 4.3.1 UNMET NEEDS
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC ANALYSIS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECASTS
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 CHANGES IN PRICING IN 2026
- 5.6 TRADE ANALYSIS
- 5.6.1 EXPORT DATA FOR HS CODE 841950
- 5.6.2 IMPORT DATA FOR HS CODE 841950
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 THERMAX - GREENFIELD REFINERY, MEXICO: INTEGRATED WASTE HEAT RECOVERY FOR A MEXICAN REFINERY
- 5.10.2 MITSUBISHI HEAVY INDUSTRIES - MARINE WHR-ORC SYSTEM: NEXT-GENERATION WASTE HEAT RECOVERY FOR MARINE ENGINES
- 5.10.3 ALFA LAVAL - OUTOKUMPU, FINLAND: WASTE HEAT RECOVERY FROM STAINLESS STEEL FURNACES
- 5.11 IMPACT OF 2025 US TARIFF ON WASTE HEAT RECOVERY SYSTEMS MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 PRICE IMPACT ANALYSIS
- 5.11.3 KEY IMPACT ON VARIOUS REGIONS
- 5.11.3.1 US
- 5.11.3.2 Europe
- 5.11.3.3 Asia Pacific
- 5.11.4 END-USE SECTOR IMPACT
6 STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, DIGITAL, AND AI ADOPTIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 ORGANIC RANKINE CYCLE (ORC)
- 6.1.2 WASTE HEAT RECOVERY BOILERS (WHRB)
- 6.1.3 HEAT RECOVERY STEAM GENERATORS (HRSG)
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 HEAT EXCHANGER TECHNOLOGY
- 6.2.2 THERMAL ENERGY STORAGE (TES)
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 SUPERCRITICAL CO2 (SCO2) POWER CYCLES
- 6.3.2 THERMOCHEMICAL HEAT RECOVERY
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2025-2027) | EFFICIENCY OPTIMIZATION & DIGITALIZATION PHASE
- 6.4.2 MID-TERM (2027-2030): ADVANCED HEAT RECOVERY & INTEGRATED ENERGY MANAGEMENT PHASE
- 6.4.3 LONG-TERM (2030-2035+): INTELLIGENT & NEXT-GENERATION HEAT RECOVERY ECOSYSTEM PHASE
- 6.5 PATENT ANALYSIS
- 6.5.1 INTRODUCTION
- 6.5.2 APPROACH
- 6.5.3 TOP APPLICANTS
- 6.5.4 JURISDICTION ANALYSIS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 THERMOELECTRIC DIRECT ELECTRICITY GENERATION
- 6.6.2 THERMOPHOTOVOLTAIC WASTE HEAT GENERATION
- 6.6.3 MEMBRANE LATENT HEAT RECOVERY
- 6.6.4 WASTE HEAT POWERED INDUSTRIAL COOLING
- 6.6.5 WASTE HEAT DRIVEN INDUSTRIAL DESALINATION
- 6.7 IMPACT OF AI/GEN AI ON WASTE HEAT RECOVERY SYSTEMS MARKET
- 6.7.1 TOP USE CASES AND MARKET POTENTIAL
- 6.7.2 BEST PRACTICES FOLLOWED BY MANUFACTURERS/OEMS IN WASTE HEAT RECOVERY SYSTEMS
- 6.7.3 CASE STUDIES OF AI IMPLEMENTATION IN WASTE HEAT RECOVERY SYSTEMS MARKET
- 6.7.4 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.5 CLIENTS' READINESS TO ADAPT AI-INTEGRATED WASTE HEAT RECOVERY SYSTEMS
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 CARBON IMPACT REDUCTION INITIATIVES
- 7.2.1.1 Increase use of lower carbon steel and recycled metallic content
- 7.2.1.2 Replace high-impact insulation inputs with lower-carbon alternatives
- 7.2.1.3 Reduce manufacturing emissions through renewable energy and heat reuse
- 7.2.2 ECO APPLICATIONS IN WASTE HEAT RECOVERY SYSTEMS
- 7.2.2.1 Use recovered industrial heat for panel manufacturing processes
- 7.2.2.2 Upgrade low temperature waste heat using industrial heat pumps
- 7.2.2.3 Combine waste heat recovery with thermal energy storage
- 7.2.1 CARBON IMPACT REDUCTION INITIATIVES
- 7.3 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.6 MARGIN OPPORTUNITIES, BY END USE INDUSTRY
- 8.6.1 PETROLEUM REFINING
- 8.6.2 METAL PRODUCTION
- 8.6.3 CEMENT
- 8.6.4 CHEMICAL
- 8.6.5 PAPER & PULP
9 WASTE HEAT RECOVERY SYSTEM MARKET, BY APPLICATION
- 9.1 INTRODUCTION
- 9.2 PREHEATING
- 9.2.1 PREHEATING APPLICATIONS EXPANDING THROUGH DIRECT THERMAL INTEGRATION ACROSS INDUSTRIAL PROCESSES
- 9.3 STEAM & ELECTRICITY GENERATION
- 9.3.1 STEAM GENERATION
- 9.3.2 ELECTRICITY GENERATION
- 9.3.2.1 Steam Rankine cycle
- 9.3.2.2 Organic Rankine cycle (ORC)
- 9.3.2.3 Kalina cycle
- 9.4 OTHER APPLICATIONS
10 WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY
- 10.1 INTRODUCTION
- 10.2 PETROLEUM REFINING
- 10.2.1 PETROLEUM REFINING IS EXPANDING WASTE HEAT RECOVERY ACROSS COMPLEX HIGH-TEMPERATURE PROCESS STREAMS
- 10.3 METAL PRODUCTION
- 10.3.1 ADVANCING HEAT RECOVERY THROUGH FURNACE-SPECIFIC THERMAL INTEGRATION
- 10.4 CEMENT
- 10.4.1 INCREASING WASTE HEAT RECOVERY ACROSS KILN AND CLINKER COOLING OPERATIONS
- 10.5 CHEMICAL
- 10.5.1 EXPANDING HEAT RECOVERY ACROSS REACTION AND ACID PRODUCTION PROCESSES
- 10.6 PAPER & PULP
- 10.6.1 EXPANDING HEAT RECOVERY ACROSS RECOVERY BOILERS AND DRYING SYSTEMS
- 10.7 OTHER END-USE INDUSTRIES
11 WASTE HEAT RECOVERY SYSTEMS MARKET, BY REGION
- 11.1 INTRODUCTION
- 11.2 ASIA PACIFIC
- 11.2.1 CHINA
- 11.2.1.1 Expansive industrial base increasing demand
- 11.2.2 INDIA
- 11.2.2.1 Energy-intensive industrial expansion strengthening demand
- 11.2.3 JAPAN
- 11.2.3.1 Stable industrial operations sustaining waste heat recovery demand
- 11.2.4 SOUTH KOREA
- 11.2.4.1 Refining and heavy industry base supporting WHRS demand
- 11.2.5 INDONESIA
- 11.2.5.1 Expanding processing base supporting demand
- 11.2.6 REST OF ASIA PACIFIC
- 11.2.1 CHINA
- 11.3 EUROPE
- 11.3.1 GERMANY
- 11.3.1.1 Industrial recovery strengthening demand for waste heat recovery systems
- 11.3.2 FRANCE
- 11.3.2.1 Manufacturing strength supporting demand growth
- 11.3.3 UK
- 11.3.3.1 Industrial activities increasing demand
- 11.3.4 ITALY
- 11.3.4.1 Industrial energy dependence accelerating demand
- 11.3.5 SPAIN
- 11.3.5.1 Expanding industrial output increasing opportunities for players
- 11.3.6 BELGIUM
- 11.3.6.1 Belgium's concentrated heavy industry is strengthening demand for waste heat recovery systems
- 11.3.7 SWEDEN
- 11.3.7.1 Export-oriented industrial base supporting demand for waste heat recovery systems
- 11.3.8 RUSSIA
- 11.3.8.1 Large industrial base strengthening demand for waste heat recovery systems
- 11.3.9 POLAND
- 11.3.9.1 Expanding energy-intensive industries increasing demand
- 11.3.10 REST OF EUROPE
- 11.3.1 GERMANY
- 11.4 NORTH AMERICA
- 11.4.1 US
- 11.4.1.1 Industrial expansion increasing demand
- 11.4.2 CANADA
- 11.4.2.1 Canada's Refining and Manufacturing Activity Supports Waste Heat Recovery Demand
- 11.4.3 MEXICO
- 11.4.3.1 Industrial expansion increasing demand
- 11.4.1 US
- 11.5 MIDDLE EAST & AFRICA
- 11.5.1 GCC COUNTRIES
- 11.5.1.1 Saudi Arabia
- 11.5.1.1.1 Expanding industrial base accelerating demand
- 11.5.1.2 UAE
- 11.5.1.2.1 Expanding non-oil industries strengthening demand
- 11.5.1.3 Rest of GCC countries
- 11.5.1.1 Saudi Arabia
- 11.5.2 SOUTH AFRICA
- 11.5.2.1 Industrial production growth increasing demand
- 11.5.3 REST OF MIDDLE EAST & AFRICA
- 11.5.1 GCC COUNTRIES
- 11.6 SOUTH AMERICA
- 11.6.1 BRAZIL
- 11.6.1.1 Expanding industrial output increasing demand
- 11.6.2 ARGENTINA
- 11.6.2.1 Expanding industrial production increasing demand
- 11.6.3 REST OF SOUTH AMERICA
- 11.6.1 BRAZIL
12 COMPETITIVE LANDSCAPE
- 12.1 OVERVIEW
- 12.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 12.3 REVENUE ANALYSIS, 2021-2025
- 12.4 MARKET SHARE ANALYSIS, 2025
- 12.5 BRAND COMPARISON
- 12.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 12.6.1 STARS
- 12.6.2 EMERGING LEADERS
- 12.6.3 PERVASIVE PLAYERS
- 12.6.4 PARTICIPANTS
- 12.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2026
- 12.6.5.1 Company footprint
- 12.6.5.2 Region footprint
- 12.6.5.3 Application footprint
- 12.6.5.4 End-use industry footprint
- 12.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2026
- 12.7.1 PROGRESSIVE COMPANIES
- 12.7.2 RESPONSIVE COMPANIES
- 12.7.3 DYNAMIC COMPANIES
- 12.7.4 STARTING BLOCKS
- 12.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 12.7.5.1 List of key startups/SMEs
- 12.7.5.2 Competitive benchmarking of key startups/SMEs
- 12.8 COMPANY VALUATION
- 12.9 FINANCIAL METRICS
- 12.10 COMPETITIVE SCENARIO
- 12.10.1 PRODUCT LAUNCHES
- 12.10.2 DEALS
- 12.10.3 EXPANSIONS
13 COMPANY PROFILES
- 13.1 KEY PLAYERS
- 13.1.1 SIEMENS ENERGY AG
- 13.1.1.1 Business overview
- 13.1.1.2 Products offered
- 13.1.1.3 Recent developments
- 13.1.1.3.1 Expansions
- 13.1.1.4 MnM view
- 13.1.1.4.1 Right to win
- 13.1.1.4.2 Strategic choices
- 13.1.1.4.3 Weakness and competitive threats
- 13.1.2 GE VERNOVA INC.
- 13.1.2.1 Business overview
- 13.1.2.2 Products offered
- 13.1.2.3 MnM view
- 13.1.2.3.1 Right to win
- 13.1.2.3.2 Strategic choices
- 13.1.2.3.3 Weakness and competitive threats
- 13.1.3 MITSUBISHI HEAVY INDUSTRIES, LTD.
- 13.1.3.1 Business overview
- 13.1.3.2 Products offered
- 13.1.3.3 Recent developments
- 13.1.3.3.1 Product launches
- 13.1.3.3.2 Deals
- 13.1.3.4 MnM view
- 13.1.3.4.1 Right to win
- 13.1.3.4.2 Strategic choices
- 13.1.3.4.3 Weakness and competitive threats
- 13.1.4 ABB LTD
- 13.1.4.1 Business overview
- 13.1.4.2 Products offered
- 13.1.4.3 Recent developments
- 13.1.4.3.1 Expansions
- 13.1.4.4 MnM view
- 13.1.4.4.1 Right to win
- 13.1.4.4.2 Strategic choices
- 13.1.4.4.3 Weakness and competitive threats
- 13.1.5 SHANGHAI ELECTRIC GROUP CO., LTD.
- 13.1.5.1 Business overview
- 13.1.5.2 Products offered
- 13.1.5.3 Recent developments
- 13.1.5.3.1 Deals
- 13.1.5.3.2 Expansions
- 13.1.5.4 MnM view
- 13.1.5.4.1 Right to win
- 13.1.5.4.2 Strategic choices
- 13.1.5.4.3 Weakness and competitive threats
- 13.1.6 KAWASAKI HEAVY INDUSTRIES, LTD.
- 13.1.6.1 Business overview
- 13.1.6.2 Products offered
- 13.1.6.3 Recent developments
- 13.1.6.3.1 Product launches
- 13.1.6.3.2 Deals
- 13.1.6.4 MnM view
- 13.1.7 DOOSAN ENERBILITY CO., LTD.
- 13.1.7.1 Business overview
- 13.1.7.2 Products offered
- 13.1.7.3 Recent developments
- 13.1.7.3.1 Deals
- 13.1.7.3.2 Expansions
- 13.1.7.4 MnM view
- 13.1.8 IHI CORPORATION
- 13.1.8.1 Business overview
- 13.1.8.2 Products offered
- 13.1.8.3 Recent developments
- 13.1.8.3.1 Deals
- 13.1.8.4 MnM view
- 13.1.9 WARTSILA CORPORATION
- 13.1.9.1 Business overview
- 13.1.9.2 Products offered
- 13.1.9.3 Recent developments
- 13.1.9.3.1 Deals
- 13.1.9.3.2 Expansions
- 13.1.9.4 MnM view
- 13.1.10 THERMAX LIMITED
- 13.1.10.1 Business overview
- 13.1.10.2 Products offered
- 13.1.10.3 Recent developments
- 13.1.10.3.1 Product launches
- 13.1.10.3.2 Deals
- 13.1.10.4 MnM view
- 13.1.1 SIEMENS ENERGY AG
- 13.2 OTHER PLAYERS
- 13.2.1 BHARAT HEAVY ELECTRICALS LIMITED (BHEL)
- 13.2.2 BABCOCK & WILCOX ENTERPRISES, INC.
- 13.2.3 ORMAT TECHNOLOGIES, INC.
- 13.2.4 ISGEC HEAVY ENGINEERING LTD.
- 13.2.5 FORBES MARSHALL PVT. LTD.
- 13.2.6 CAIN INDUSTRIES, INC.
- 13.2.7 DONGFANG ELECTRIC CORPORATION LTD.
- 13.2.8 HARBIN ELECTRIC COMPANY LIMITED
- 13.2.9 XIZI CLEAN ENERGY EQUIPMENT MANUFACTURING CO., LTD.
- 13.2.10 SPIRAX-SARCO ENGINEERING PLC (SPIRAX GROUP)
- 13.2.11 JOHN COCKERILL GROUP
- 13.2.12 ORCAN ENERGY AG
- 13.2.13 VICTORY ENERGY OPERATIONS, LLC
- 13.2.14 THERMODYNE ENGINEERING SYSTEMS
- 13.2.15 CLEAN ENERGY TECHNOLOGIES, INC. (CETY)
14 RESEARCH METHODOLOGY
- 14.1 RESEARCH DATA
- 14.2 SECONDARY DATA
- 14.2.1 KEY DATA FROM SECONDARY SOURCES
- 14.3 PRIMARY DATA
- 14.3.1 KEY DATA FROM PRIMARY SOURCES
- 14.3.2 KEY INDUSTRY INSIGHTS
- 14.3.3 BREAKDOWN OF INTERVIEWS WITH EXPERTS
- 14.4 MARKET SIZE ESTIMATION
- 14.5 GROWTH FORECAST
- 14.6 DATA TRIANGULATION
- 14.7 RESEARCH ASSUMPTIONS
- 14.8 RISK ASSESSMENT
- 14.9 FACTOR ANALYSIS
- 14.10 RESEARCH LIMITATIONS
15 APPENDIX
- 15.1 DISCUSSION GUIDE
- 15.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 15.3 CUSTOMIZATION OPTIONS
- 15.4 RELATED REPORTS
- 15.5 AUTHOR DETAILS
List of Tables
- TABLE 1 GLOBAL DATA CENTER COUNT BY REGION, 2026
- TABLE 2 GLOBAL ORGANIC RANKINE CYCLE (ORC) MANUFACTURERS: INSTALLED CAPACITY AND PLANTS
- TABLE 3 INTERCONNECTED MARKETS
- TABLE 4 CROSS-SECTOR OPPORTUNITIES
- TABLE 5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS: KEY MOVES AND STRATEGIC FOCUS
- TABLE 6 PORTER'S FIVE FORCES ANALYSIS
- TABLE 7 WORLD REAL GDP (ANNUAL PERCENTAGE CHANGE) OF DIFFERENT REGIONS, 2024-2026
- TABLE 8 WORLD REAL GDP (ANNUAL PERCENTAGE CHANGE) OF TOP COUNTRIES, 2024-2026
- TABLE 9 ROLES OF COMPANIES IN WASTE HEAT RECOVERY SYSTEM ECOSYSTEM
- TABLE 10 EXPORT DATA FOR HS CODE 841950, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 11 IMPORT DATA FOR HS CODE 841950, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 12 WASTE HEAT RECOVERY SYSTEMS: KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 13 US TARIFF TABLE -WASTE HEAT RECOVERY SYSTEM (HTS 8402 / 8404 / 8419.50)
- TABLE 14 END-USE INDUSTRY IMPACT
- TABLE 15 KEY PATENTS, 2025
- TABLE 16 TOP USE CASES AND MARKET POTENTIAL
- TABLE 17 BEST PRACTICES: COMPANIES IMPLEMENTING USE CASES
- TABLE 18 WASTE HEAT RECOVERY SYSTEMS MARKET: CASE STUDIES RELATED TO GEN AI IMPLEMENTATION
- TABLE 19 NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 20 EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 21 ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 22 SOUTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 23 MIDDLE EAST & AFRICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 24 GLOBAL INDUSTRY STANDARDS IN WASTE HEAT RECOVERY SYSTEMS MARKET
- TABLE 25 CERTIFICATIONS, LABELING, ECO-STANDARDS IN WASTE HEAT RECOVERY SYSTEMS MARKET
- TABLE 26 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP 3 END-USE INDUSTRIES
- TABLE 27 KEY BUYING CRITERIA FOR TOP 3 END-USE INDUSTRIES
- TABLE 28 UNMET NEEDS IN WASTE HEAT RECOVERY SYSTEMS MARKET BY END-USE INDUSTRIES
- TABLE 29 WASTE HEAT SOURCES AND RELATED RECOVERY OPPORTUNITIES AT LOW TEMPERATURES (<230°C/446°F)
- TABLE 30 WASTE HEAT SOURCES AND RELATED RECOVERY OPPORTUNITIES AT MEDIUM TEMPERATURES (230°C-650°C/446-1,202°F)
- TABLE 31 WASTE HEAT SOURCES AND RELATED RECOVERY OPPORTUNITIES AT HIGH TEMPERATURES (>650°C/1,202°F)
- TABLE 32 WASTE HEAT RECOVERY SYSTEM MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 33 WASTE HEAT RECOVERY SYSTEM MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 34 PREHEATING: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2021-2024 (USD MILLION)
- TABLE 35 PREHEATING: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2025-2031 (USD MILLION)
- TABLE 36 STEAM & ELECTRICITY GENERATION: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2021-2024 (USD MILLION)
- TABLE 37 STEAM & ELECTRICITY GENERATION: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2025-2031 (USD MILLION)
- TABLE 38 OTHER APPLICATIONS: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2021-2024 (USD MILLION)
- TABLE 39 OTHER APPLICATIONS: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2025-2031 (USD MILLION)
- TABLE 40 WASTE HEAT RECOVERY SYSTEM MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 41 WASTE HEAT RECOVERY SYSTEM MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 42 PETROLEUM REFINING: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2021-2024 (USD MILLION)
- TABLE 43 PETROLEUM REFINING: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2025-2031 (USD MILLION)
- TABLE 44 METAL PRODUCTION: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2021-2024 (USD MILLION)
- TABLE 45 METAL PRODUCTION: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2025-2031 (USD MILLION)
- TABLE 46 CEMENT: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2021-2024 (USD MILLION)
- TABLE 47 CEMENT: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2025-2031 (USD MILLION)
- TABLE 48 CHEMICAL: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2021-2024 (USD MILLION)
- TABLE 49 CHEMICAL: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2025-2031 (USD MILLION)
- TABLE 50 PAPER & PULP: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2021-2024 (USD MILLION)
- TABLE 51 PAPER & PULP: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2025-2031 (USD MILLION)
- TABLE 52 OTHER END-USE INDUSTRIES: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2021-2024 (USD MILLION)
- TABLE 53 OTHER END-USE INDUSTRIES: WASTE HEAT RECOVERY SYSTEM MARKET, BY REGION, 2025-2031 (USD MILLION)
- TABLE 54 WASTE HEAT RECOVERY SYSTEMS MARKET, BY REGION, 2021-2024 (USD MILLION)
- TABLE 55 WASTE HEAT RECOVERY SYSTEMS MARKET, BY REGION, 2025-2031 (USD MILLION)
- TABLE 56 ASIA PACIFIC: WASTE HEAT RECOVERY SYSTEMS MARKET, BY COUNTRY, 2021-2024 (USD MILLION)
- TABLE 57 ASIA PACIFIC: WASTE HEAT RECOVERY SYSTEMS MARKET, BY COUNTRY, 2025-2031 (USD MILLION)
- TABLE 58 ASIA PACIFIC: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 59 ASIA PACIFIC: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 60 ASIA PACIFIC: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 61 ASIA PACIFIC: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 62 CHINA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 63 CHINA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 64 CHINA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 65 CHINA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 66 INDIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 67 INDIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 68 INDIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 69 INDIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 70 JAPAN: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 71 JAPAN: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 72 JAPAN: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 73 JAPAN: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 74 SOUTH KOREA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 75 SOUTH KOREA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 76 SOUTH KOREA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 77 SOUTH KOREA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 78 INDONESIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 79 INDONESIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 80 INDONESIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 81 INDONESIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 82 REST OF ASIA PACIFIC: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 83 REST OF ASIA PACIFIC: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 84 REST OF ASIA PACIFIC: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 85 REST OF ASIA PACIFIC: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 86 EUROPE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY COUNTRY, 2021-2024 (USD MILLION)
- TABLE 87 EUROPE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY COUNTRY, 2025-2031 (USD MILLION)
- TABLE 88 EUROPE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 89 EUROPE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 90 EUROPE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 91 EUROPE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 92 GERMANY: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 93 GERMANY: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 94 GERMANY: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 95 GERMANY: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 96 FRANCE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 97 FRANCE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 98 FRANCE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 99 FRANCE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 100 UK: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 101 UK: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 102 UK: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 103 UK: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 104 ITALY: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 105 ITALY: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 106 ITALY: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 107 ITALY: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 108 SPAIN: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 109 SPAIN: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 110 SPAIN: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 111 SPAIN: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 112 BELGIUM: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 113 BELGIUM: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 114 BELGIUM: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 115 BELGIUM: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 116 SWEDEN: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 117 SWEDEN: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 118 SWEDEN: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 119 SWEDEN: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 120 RUSSIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 121 RUSSIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 122 RUSSIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 123 RUSSIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 124 POLAND: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 125 POLAND: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 126 POLAND: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 127 POLAND: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 128 REST OF EUROPE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 129 REST OF EUROPE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 130 REST OF EUROPE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 131 REST OF EUROPE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 132 NORTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY COUNTRY, 2021-2024 (USD MILLION)
- TABLE 133 NORTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY COUNTRY, 2025-2031 (USD MILLION)
- TABLE 134 NORTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 135 NORTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 136 NORTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 137 NORTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 138 US: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 139 US: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 140 US: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 141 US: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 142 CANADA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 143 CANADA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 144 CANADA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 145 CANADA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 146 MEXICO: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 147 MEXICO: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 148 MEXICO: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 149 MEXICO: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 150 MIDDLE EAST & AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY COUNTRY, 2021-2024 (USD MILLION)
- TABLE 151 MIDDLE EAST & AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY COUNTRY, 2025-2031 (USD MILLION)
- TABLE 152 MIDDLE EAST & AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 153 MIDDLE EAST & AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 154 MIDDLE EAST & AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 155 MIDDLE EAST & AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 156 GCC COUNTRIES: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 157 GCC COUNTRIES: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 158 GCC COUNTRIES: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 159 GCC COUNTRIES: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 160 SAUDI ARABIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 161 SAUDI ARABIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 162 SAUDI ARABIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 163 SAUDI ARABIA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 164 UAE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 165 UAE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 166 UAE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 167 UAE: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 168 REST OF GCC COUNTRIES: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 169 REST OF GCC COUNTRIES: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 170 REST OF GCC COUNTRIES: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 171 REST OF GCC COUNTRIES: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 172 SOUTH AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 173 SOUTH AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 174 SOUTH AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 175 SOUTH AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 176 REST OF MIDDLE EAST & AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 177 REST OF MIDDLE EAST & AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 178 REST OF MIDDLE EAST & AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 179 REST OF MIDDLE EAST & AFRICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 180 SOUTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY COUNTRY, 2021-2024 (USD MILLION)
- TABLE 181 SOUTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY COUNTRY, 2025-2031 (USD MILLION)
- TABLE 182 SOUTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 183 SOUTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 184 SOUTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 185 SOUTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 186 BRAZIL: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 187 BRAZIL: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 188 BRAZIL: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 189 BRAZIL: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 190 ARGENTINA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 191 ARGENTINA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 192 ARGENTINA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 193 ARGENTINA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 194 REST OF SOUTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 195 REST OF SOUTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY APPLICATION, 2025-2031 (USD MILLION)
- TABLE 196 REST OF SOUTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2021-2024 (USD MILLION)
- TABLE 197 REST OF SOUTH AMERICA: WASTE HEAT RECOVERY SYSTEMS MARKET, BY END-USE INDUSTRY, 2025-2031 (USD MILLION)
- TABLE 198 WASTE HEAT RECOVERY SYSTEMS MARKET: OVERVIEW OF STRATEGIES ADOPTED BY MARKET PLAYERS, JANUARY 2024-JULY 2026
- TABLE 199 WASTE HEAT RECOVERY SYSTEMS MARKET: DEGREE OF COMPETITION
- TABLE 200 WASTE HEAT RECOVERY SYSTEMS MARKET: REGION FOOTPRINT
- TABLE 201 WASTE HEAT RECOVERY SYSTEMS MARKET: APPLICATION FOOTPRINT
- TABLE 202 WASTE HEAT RECOVERY SYSTEMS MARKET: END-USE INDUSTRY FOOTPRINT
- TABLE 203 WASTE HEAT RECOVERY SYSTEMS MARKET: KEY STARTUPS/SMES
- TABLE 204 WASTE HEAT RECOVERY SYSTEMS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 205 WASTE HEAT RECOVERY SYSTEMS MARKET: PRODUCT LAUNCHES, JANUARY 2024- AUGUST 2026
- TABLE 206 WASTE HEAT RECOVERY SYSTEMS MARKET: DEALS, JANUARY 2024-AUGUST 2026
- TABLE 207 WASTE HEAT RECOVERY SYSTEMS MARKET: EXPANSIONS, JANUARY 2024-AUGUST 2026
- TABLE 208 SIEMENS ENERGY AG: COMPANY OVERVIEW
- TABLE 209 SIEMENS ENERGY AG: PRODUCTS OFFERED
- TABLE 210 SIEMENS ENERGY AG: EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 211 GE VERNOVA INC.: COMPANY OVERVIEW
- TABLE 212 GE VERNOVA INC.: PRODUCTS OFFERED
- TABLE 213 MITSUBISHI HEAVY INDUSTRIES, LTD.: COMPANY OVERVIEW
- TABLE 214 MITSUBISHI HEAVY INDUSTRIES, LTD.: PRODUCTS OFFERED
- TABLE 215 MITSUBISHI HEAVY INDUSTRIES, LTD.: PRODUCT LAUNCHES, JANUARY 2024-JULY 2026
- TABLE 216 MITSUBISHI HEAVY INDUSTRIES, LTD.: DEALS, JANUARY 2024- JULY 2026
- TABLE 217 ABB LTD: COMPANY OVERVIEW
- TABLE 218 ABB LTD: PRODUCTS OFFERED
- TABLE 219 ABB LTD: EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 220 SHANGHAI ELECTRIC GROUP CO., LTD.: COMPANY OVERVIEW
- TABLE 221 SHANGHAI ELECTRIC GROUP CO., LTD.: PRODUCTS OFFERED
- TABLE 222 SHANGHAI ELECTRIC GROUP CO., LTD.: DEALS, JANUARY 2024- JULY 2026
- TABLE 223 SHANGHAI ELECTRIC GROUP CO., LTD.: EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 224 KAWASAKI HEAVY INDUSTRIES, LTD.: COMPANY OVERVIEW
- TABLE 225 KAWASAKI HEAVY INDUSTRIES, LTD.: PRODUCTS OFFERED
- TABLE 226 KAWASAKI HEAVY INDUSTRIES, LTD.: PRODUCT LAUNCHES, JANUARY 2024-JULY 2026
- TABLE 227 KAWASAKI HEAVY INDUSTRIES, LTD.: DEALS, JANUARY 2024- JULY 2026
- TABLE 228 DOOSAN ENERBILITY CO., LTD.: COMPANY OVERVIEW
- TABLE 229 DOOSAN ENERBILITY CO., LTD.: PRODUCTS OFFERED
- TABLE 230 DOOSAN ENERBILITY CO., LTD.: DEALS, JANUARY 2024- JULY 2026
- TABLE 231 DOOSAN ENERBILITY CO., LTD.: EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 232 IHI CORPORATION: COMPANY OVERVIEW
- TABLE 233 IHI CORPORATION: PRODUCTS OFFERED
- TABLE 234 IHI CORPORATION: DEALS, JANUARY 2024- JULY 2026
- TABLE 235 WARTSILA CORPORATION: COMPANY OVERVIEW
- TABLE 236 WARTSILA CORPORATION: PRODUCTS OFFERED
- TABLE 237 WARTSILA CORPORATION: DEALS, JANUARY 2024- JULY 2026
- TABLE 238 WARTSILA CORPORATION: EXPANSIONS, JANUARY 2024-JULY 2026
- TABLE 239 THERMAX LIMITED: COMPANY OVERVIEW
- TABLE 240 THERMAX LIMITED: PRODUCTS OFFERED
- TABLE 241 THERMAX LIMITED: PRODUCT LAUNCHES, JANUARY 2024-JULY 2026
- TABLE 242 THERMAX LIMITED: DEALS, JANUARY 2024- JULY 2026
- TABLE 243 BHARAT HEAVY ELECTRICALS LIMITED (BHEL): COMPANY OVERVIEW
- TABLE 244 BABCOCK & WILCOX ENTERPRISES, INC.: COMPANY OVERVIEW
- TABLE 245 ORMAT TECHNOLOGIES, INC.: COMPANY OVERVIEW
- TABLE 246 ISGEC HEAVY ENGINEERING LTD.: COMPANY OVERVIEW
- TABLE 247 FORBES MARSHALL PVT. LTD.: COMPANY OVERVIEW
- TABLE 248 CAIN INDUSTRIES, INC.: COMPANY OVERVIEW
- TABLE 249 DONGFANG ELECTRIC CORPORATION LTD.: COMPANY OVERVIEW
- TABLE 250 HARBIN ELECTRIC COMPANY LIMITED: COMPANY OVERVIEW
- TABLE 251 XIZI CLEAN ENERGY EQUIPMENT MANUFACTURING CO., LTD.: COMPANY OVERVIEW
- TABLE 252 SPIRAX-SARCO ENGINEERING PLC (SPIRAX GROUP): COMPANY OVERVIEW
- TABLE 253 JOHN COCKERILL GROUP: COMPANY OVERVIEW
- TABLE 254 ORCAN ENERGY AG: COMPANY OVERVIEW
- TABLE 255 VICTORY ENERGY OPERATIONS, LLC: COMPANY OVERVIEW
- TABLE 256 THERMODYNE ENGINEERING SYSTEMS: COMPANY OVERVIEW
- TABLE 257 CLEAN ENERGY TECHNOLOGIES, INC. (CETY): COMPANY OVERVIEW
List of Figures
- FIGURE 1 WASTE HEAT RECOVERY SYSTEM MARKET SEGMENTATION & REGIONAL SCOPE
- FIGURE 2 KEY INSIGHTS AND MARKET HIGHLIGHTS
- FIGURE 3 GLOBAL WASTE HEAT RECOVERY SYSTEMS MARKET, 2021-2031
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN WASTE HEAT RECOVERY SYSTEM MARKET (2021-2025)
- FIGURE 5 DISRUPTIVE TRENDS IMPACTING GROWTH OF WASTE HEAT RECOVERY SYSTEM MARKET DURING FORECAST PERIOD
- FIGURE 6 HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS IN WASTE HEAT RECOVERY SYSTEMS MARKET, 2026-2031
- FIGURE 7 EUROPE TO BE LARGEST MARKET DURING FORECAST PERIOD
- FIGURE 8 HIGH DEMAND FOR WASTE HEAT RECOVERY SYSTEM TO CREATE LUCRATIVE OPPORTUNITIES FOR MARKET PLAYERS
- FIGURE 9 STEAM & ELECTRICITY GENERATION SEGMENT & PETROLEUM REFINING SEGMENT ACCOUNTED FOR LARGEST MARKET SHARES IN 2025
- FIGURE 10 CHINA TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 11 WASTE HEAT RECOVERY SYSTEMS MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 12 GLOBAL PRICE OF ENERGY INDEX, 2021-2026
- FIGURE 13 GLOBAL DATA CENTRES BY REGION, 2026
- FIGURE 14 WASTE HEAT RECOVERY SYSTEM MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 15 WASTE HEAT RECOVERY SYSTEM VALUE CHAIN
- FIGURE 16 WASTE HEAT RECOVERY SYSTEM ECOSYSTEM
- FIGURE 17 EXPORT DATA FOR HS CODE 841950, BY COUNTRY, 2021-2025 (USD THOUSAND)
- FIGURE 18 IMPORT DATA FOR HS CODE 841950, BY COUNTRY, 2021-2025 (USD THOUSAND)
- FIGURE 19 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- FIGURE 20 INVESTMENT AND FUNDING SCENARIO, 2021-2025
- FIGURE 21 LIST OF MAJOR PATENTS RELATED TO WASTE HEAT RECOVERY SYSTEM, 2016-2025
- FIGURE 22 JURISDICTION OF CHINA REGISTERED HIGHEST PERCENTAGE OF PATENTS, 2016-2025
- FIGURE 23 WASTE HEAT RECOVERY SYSTEMS MARKET: DECISION-MAKING FACTORS
- FIGURE 24 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP 3 END-USE INDUSTRIES
- FIGURE 25 KEY BUYING CRITERIA FOR TOP 3 END-USE INDUSTRIES
- FIGURE 26 ADOPTION BARRIERS & INTERNAL CHALLENGES
- FIGURE 27 STEAM & ELECTRICITY GENERATION SEGMENT TO ACCOUNT FOR LARGEST SHARE DURING FORECAST PERIOD
- FIGURE 28 PETROLEUM REFINING SEGMENT TO BE LARGEST TYPE SEGMENT DURING FORECAST PERIOD
- FIGURE 29 CHINA TO BE FASTEST-GROWING MARKET DURING FORECAST PERIOD
- FIGURE 30 EUROPE TO DOMINATE WASTE HEAT RECOVERY SYSTEMS MARKET IN 2026
- FIGURE 31 ASIA PACIFIC: WASTE HEAT RECOVERY SYSTEMS MARKET SNAPSHOT
- FIGURE 32 EUROPE: WASTE HEAT RECOVERY SYSTEMS MARKET SNAPSHOT
- FIGURE 33 WASTE HEAT RECOVERY SYSTEMS MARKET: REVENUE ANALYSIS OF KEY PLAYERS, 2021-2025 (USD BILLION)
- FIGURE 34 WASTE HEAT RECOVERY SYSTEMS MARKET SHARE ANALYSIS, 2025
- FIGURE 35 WASTE HEAT RECOVERY SYSTEMS MARKET: BRAND COMPARISON
- FIGURE 36 WASTE HEAT RECOVERY SYSTEMS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 37 WASTE HEAT RECOVERY SYSTEMS MARKET: COMPANY FOOTPRINT, 2026
- FIGURE 38 WASTE HEAT RECOVERY SYSTEM MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 39 COMPANY VALUATION (USD BILLION), 2026
- FIGURE 40 FINANCIAL METRICS: EV/EBITDA RATIO, 2026
- FIGURE 41 YEAR-TO-DATE PRICE AND FIVE-YEAR STOCK BETA, 2026
- FIGURE 42 SIEMENS ENERGY AG: COMPANY SNAPSHOT
- FIGURE 43 GE VERNOVA INC.: COMPANY SNAPSHOT
- FIGURE 44 MITSUBISHI HEAVY INDUSTRIES, LTD.: COMPANY SNAPSHOT
- FIGURE 45 ABB LTD: COMPANY SNAPSHOT
- FIGURE 46 SHANGHAI ELECTRIC GROUP CO., LTD.: COMPANY SNAPSHOT
- FIGURE 47 KAWASAKI HEAVY INDUSTRIES, LTD.: COMPANY SNAPSHOT
- FIGURE 48 DOOSAN ENERBILITY CO., LTD.: COMPANY SNAPSHOT
- FIGURE 49 IHI CORPORATION: COMPANY SNAPSHOT
- FIGURE 50 WARTSILA CORPORATION: COMPANY SNAPSHOT
- FIGURE 51 THERMAX LIMITED: COMPANY SNAPSHOT
- FIGURE 52 WASTE HEAT RECOVERY SYSTEMS MARKET: RESEARCH DESIGN
- FIGURE 53 MARKET SIZE ESTIMATION: BOTTOM-UP APPROACH
- FIGURE 54 MARKET SIZE ESTIMATION: TOP-DOWN APPROACH
- FIGURE 55 MARKET SIZE ESTIMATION: SUPPLY SIDE
- FIGURE 56 WASTE HEAT RECOVERY SYSTEM MARKET: DATA TRIANGULATION

