PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2066501

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2066501
Automotive Aluminum Parts High-Pressure Die Casting (HPDC) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the automotive aluminum parts High-Pressure Die Casting (HPDC) market size is expected to increase from USD 21.12 billion in 2025 to USD 22.24 billion in 2026 and reach USD 28.80 billion by 2031, progressing at a 5.31% CAGR.
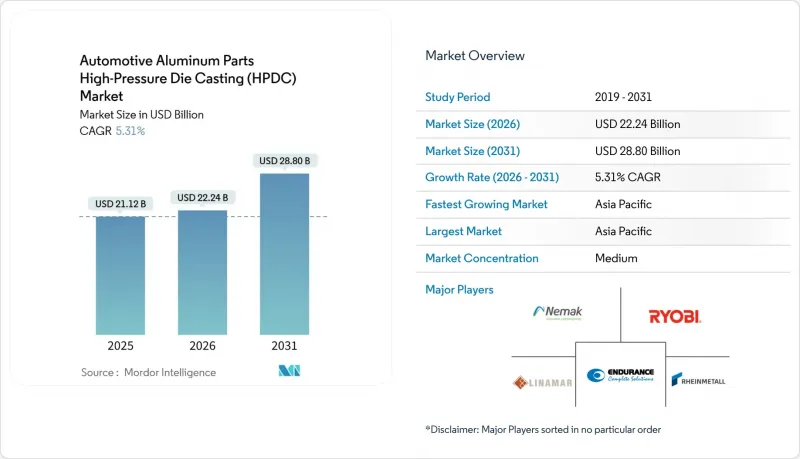
This report is Segmented by Application Type (Body-In-White Components, Chassis Parts, and More), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Manufacturing Process (Design Engineering, Die Casting, and More), End Use (OEMs, Aftermarket Suppliers), Casting Material, and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Aluminum Parts High-Pressure Die Casting (HPDC) Market Trends and Insights
OEM Lightweighting and Emission Mandates
Corporate Average Fuel Economy rules targeting 50.4 mpg in the United States by 2031 and the European Union's EUR 95 (~USD 109) per gram CO2/km fleet ceiling penalize excess emissions, forcing automakers to substitute steel for aluminum, which reduces mass per part by a significant amount . General Motors plans to lift average aluminum content, underscoring a long-term strategic shift. High-pressure die casting (HPDC) enables complex geometries, allowing battery trays and cross-members to emerge as single pieces that eliminate upwards of 60 welds. OEM purchasing executives accept aluminum's material premium because weight savings avoid carbon fines and enable smaller traction-battery packs. As regulations tighten globally, the Automotive aluminum parts HPDC market gains recurring pull-through from every new vehicle platform.
EV Battery-Housing and E-Drive Demand Surge
EV sales exceeded 20 million units in 2025 and are tracking toward significant growth by 2031, intensifying the need for thermally conductive aluminum enclosures that shield cells and dissipate heat . Tesla integrates 4680 cells directly into large structural castings, trimming vehicle mass while boosting torsional rigidity. Chinese leaders such as BYD replicate the concept, specifying 0.1 mm machining tolerances to secure cell-to-pack flatness. E-drive stator housings rely on silicon-rich A380 variants that deliver higher thermal conductivity, illustrating how alloy development and casting innovation advance in lockstep. Each of these developments widens the addressable market for HPDC Automotive aluminum parts.
Aluminum and Energy Price Volatility
LME cash prices fluctuated during 2025, compressing margins on six-month fixed-price supply contracts. Energy accounts for a significant share of primary aluminum costs, so the spike in European natural gas prices after geopolitical disruptions squeezed smelters, trimming regional supply. Die casters add more electricity per kilogram than steel stampers, exposing them to tariff shocks that erase notable EBIT margins. Hedging mitigates only limited exposure since forward curves extend merely 18 months, compelling many tier-ones to incorporate price-escalation clauses. Such volatility tempers near-term growth expectations for the Automotive aluminum parts HPDC market.
Other drivers and restraints analyzed in the detailed report include:
- Gigacasting Presses Enable Large Structural Castings
- Circular-Economy Push for Recycled Aluminum
- Advanced High-Strength-Steel Structural Alternatives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Body-in-white parts accounted for 45.18% of 2025 demand, the largest slice of the Automotive aluminum parts HPDC market. Gigacasting trims assembly lines from 171 weld-intensive steel parts to two monolithic structures, raising torsional rigidity and curtailing takt time. Over the forecast horizon, this segment will expand at a 6.12% CAGR, as Mercedes-Benz and Toyota join Tesla in announcing structural cast programs. Chassis modules capture a modest share, propelled by suspension arms and sub-frames that benefit from aluminum's stiffness-to-mass ratio.
Single-speed gearboxes in light trucks and multi-speed boxes in commercial EVs sustain transmission-housing demand even as internal-combustion engines decline. Smaller structural items-engine mounts, cross-members, and heat shields-capture incremental gains given aluminum's vibration-damping benefits in low-NVH luxury models. These dynamics collectively fortify the Automotive aluminum parts HPDC market over the mid-term.
Passenger cars accounted for 75.03% of 2025 shipments, forming the cornerstone of the Automotive aluminum parts HPDC market. High production volumes and rapid model-year changeovers keep tooling utilization high, encouraging further casting automation. Meanwhile, light commercial vehicles notch the fastest 7.62% CAGR as e-commerce hubs demand urban-delivery vans outfitted with substantial aluminum battery armor.
Medium-duty and heavy-duty trucks weigh ROI for aluminum against payload limits; fleet managers accept a higher up-front cost if it unlocks an extra pallet of freight. Regional divergence persists: European haulers pursue aluminum to satisfy carbon taxes, whereas some Asian fleets still favor low-cost steel. Nonetheless, electrification mandates will gradually tilt procurement toward lightweight materials, enhancing the long-range prospects of the Automotive aluminum parts HPDC market.
Geography Analysis
Asia-Pacific commanded 57.04% of 2025 turnover, reflecting deep vertical integration from bauxite mines to final vehicle assembly. Chinese automakers spearhead gigacasting adoption, while Indian firms draw on Production-Linked Incentives that encourage local die-casting investments. Japanese and Korean suppliers co-develop rheo-HPDC lines and export the technology across the region. Urbanization, last-mile delivery demand, and tightening Euro 6-equivalent emission rules combine to yield a 7.02% CAGR, reinforcing Asia-Pacific's leadership in the Automotive aluminum parts HPDC market.
North America will see a notable CAGR through 2031 as USMCA content rules reward regional sourcing. Nemak's Michigan expansion and Linamar's Tennessee line tap that policy tailwind, while Tesla's Texas gigafactory demonstrates domestic scale. Federal infrastructure funding channels additional power-grid capacity toward lightweight-component corridors, lowering electricity costs for energy-intensive casting shops. Together, these drivers spell durable growth for the Automotive aluminum parts HPDC market in the Americas.
Europe contributed significantly to 2025 revenue, cemented by premium brands that demand top-tier cast integrity. Circular-economy directives force recycled content, spurring foundries to adopt closed-loop scrap collection. Advanced high-strength steel remains a formidable rival in certain structural nodes, yet battery-electric platforms lean toward aluminum. Supply-chain re-localization also gains favor as OEMs cut exposure to geopolitical risk, channeling new investment within the bloc and supporting the Automotive aluminum parts HPDC industry outlook.
- Nemak, S.A.B. de C.V.
- Rheinmetall AG
- Linamar Corporation
- Endurance Technologies Limited
- Bocar Group
- Gibbs Die Casting Corporation
- Martinrea International Inc.
- Pace Industries, LLC
- Dynacast International LLC
- Ryobi Die Casting Inc.
- Rockman Industries Ltd.
- Guangdong Hongtu Technology (Holdings) Co., Ltd.
- Samkee Corp.
- Rane Holdings Limited
- LCN
- DL Motors Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 OEM Lightweighting and Emission Mandates
- 4.2.2 EV Battery-Housing and E-Drive Demand Surge
- 4.2.3 Gigacasting Presses Enable Large Structural Castings
- 4.2.4 Circular-Economy Push for Recycled Aluminum
- 4.2.5 Vacuum-Assisted HPDC and Deburring Automation Lift Yields
- 4.2.6 Rheo-HPDC Opens High-TC Wrought-Alloy Opportunities
- 4.3 Market Restraints
- 4.3.1 Aluminum and Energy Price Volatility
- 4.3.2 Advanced High-Strength-Steel Structural Alternatives
- 4.3.3 Crash-Repair Complexity of Giga-Cast Modules
- 4.3.4 Corrosion Risks in Recycled-Alloy Structural Parts
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Application Type
- 5.1.1 Body-in-White Components
- 5.1.2 Chassis Parts
- 5.1.3 Transmission Components
- 5.1.4 Other Structural Parts
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Light Commercial Vehicles
- 5.2.3 Medium and Heavy Commercial Vehicles
- 5.3 By Manufacturing Process
- 5.3.1 Design Engineering
- 5.3.2 Die Casting
- 5.3.3 Surface Treatment
- 5.3.4 Assembly
- 5.4 By End Use
- 5.4.1 OEMs
- 5.4.2 Aftermarket Suppliers
- 5.5 By Casting Material
- 5.5.1 Primary Aluminum Alloys
- 5.5.2 Recycled Aluminum Alloys
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 South Africa
- 5.6.5.4 Turkey
- 5.6.5.5 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Nemak, S.A.B. de C.V.
- 6.4.2 Rheinmetall AG
- 6.4.3 Linamar Corporation
- 6.4.4 Endurance Technologies Limited
- 6.4.5 Bocar Group
- 6.4.6 Gibbs Die Casting Corporation
- 6.4.7 Martinrea International Inc.
- 6.4.8 Pace Industries, LLC
- 6.4.9 Dynacast International LLC
- 6.4.10 Ryobi Die Casting Inc.
- 6.4.11 Rockman Industries Ltd.
- 6.4.12 Guangdong Hongtu Technology (Holdings) Co., Ltd.
- 6.4.13 Samkee Corp.
- 6.4.14 Rane Holdings Limited
- 6.4.15 LCN
- 6.4.16 DL Motors Co., Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

