PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2073585

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2073585
Online Dating Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the online dating services market size is expected to grow from USD 6.97 billion in 2025 to USD 7.79 billion in 2026 and is forecast to reach USD 13.57 billion by 2031 at 11.76% CAGR over 2026-2031.
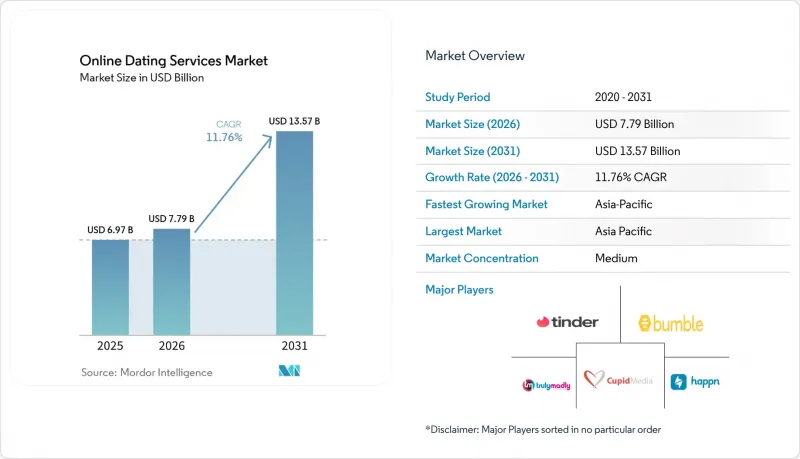
This report is Segmented by Type (Paying Online Dating, Non-Paying Online Dating), Revenue Model (Subscription, Advertising-Supported, Other Model), Platform (Web Portals, Applications), Age Group (Adult, Baby Boomer and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Online Dating Services Market Trends and Insights
Surge in Gen-Z and Millennial willingness to pay for premium matchmaking features
Premium adoption reflects a move from casual browsing toward intentional relationship building. Match Group reported a 17% rise in revenue per payer in 2024, with a 26% jump in the Americas, showing higher spending even as overall payers declined. Micro-transactions accelerate as users opt to pay for boosts or profile insights instead of fixed plans, creating tiered offers that meet different wallet sizes. Higher spending users also demonstrate longer retention, sustaining platform cash flows. This shift helps offset user-acquisition costs that continue to rise in saturated cities.
Growing acceptance of niche & identity-based platforms in North America & Europe
Niche applications attract users who value community alignment over large pools. Grindr's 25% Q1 2025 revenue jump and 14.5 million MAUs validate the viability of focused segments. Faith-based or lifestyle-specific services monetize via higher ARPU, stemming from deeper engagement and lower churn. Success forces major apps to add community filters and tailored algorithms to retain users.
Escalating privacy-regulation costs under GDPR & California CPRA
Grindr incurred a EUR 5.7 million fine (USD 6.2 million) in Norway for data-sharing infractions. Italy's data authority penalized Luka Inc. EUR 5 million (USD 5.4 million) for its AI companion service. Compliance now demands dedicated legal teams, data-mapping systems, and third-party audits, raising barriers for new entrants and squeezing margins for smaller players.
Other drivers and restraints analyzed in the detailed report include:
- AI-led personalization improving match success rates in Asia
- Integrations with social-commerce & live-streaming in China and SEA
- Rising user fatigue & app-deletion rates in saturated urban clusters
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Paying services controlled 69.45% of the online dating services market in 2025 and will compound at 12.61% through 2031. The online dating services market size for paying tiers increases as users equate fees with safety and algorithm quality. Free tiers act as funnels; once initial matches spark confidence, users migrate to paid plans for read-receipt visibility, advanced filters, and verification badges. Platforms balance upsell tactics with user satisfaction to avoid backlash from aggressive paywalls.
Non-paying services retain relevance in emerging economies where disposable incomes lag, yet conversion potential rises alongside smartphone penetration. Advertiser support partially funds free offerings, but privacy curbs on ad targeting pressure ARPU. Consequently, dual-tier or freemium models remain dominant, with iterative feature gating calibrated to optimize lifetime value without stalling onboarding velocity.
Subscriptions captured 54.35% share of the online dating services market size in 2025. However, micro-transactions growing at 14.58% CAGR signal a pivot toward a-la-carte spending. Virtual gifts, profile boosts, and timed visibility passes encourage spontaneous purchases during peak engagement moments. Users perceive fairness in paying only when they need an edge, mitigating subscription fatigue.
Asian platforms set precedents with detailed virtual economies. Grindr introduced weekly subscriptions to match budget-sensitive segments, illustrating granular price-point experimentation. Advertising remains a secondary pillar, but cookie deprecation and consent rules limit precision, giving direct-payment streams higher strategic value.
Complete Report Scope:
- By Type
- Paying Online Dating
- Non-Paying Online Dating
- By Revenue Model
- Subscription
- Advertising-Supported
- Other Model
- By Platform
- Web Portals
- Applications
- By Age Group
- Adult
- Baby Boomer
- Generation X
- Generation Z
- Millennials
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Nordics
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific commanded 34.85% of the online dating services market in 2025 and is projected to grow at a 13.12% CAGR. China's 240 million singles fuel video-first platforms where livestream dating merges with social-commerce, yielding diversified revenues beyond subscriptions. Tokyo's investment of USD 1.28 million in an AI-driven government app underscores institutional support. India generated USD 398 million in 2024 revenue with expectations of USD 783 million by 2025, boosted by tier-2 city adoption. Localized features such as parental dashboards meet cultural norms, widening appeal.
North America retains high ARPU and established brands despite slower expansion. Match Group raised revenue per payer by 26% in the Americas, demonstrating pricing headroom. The California Consumer Privacy Rights Act adds compliance layers that increase fixed costs, incentivizing scale economies. User fatigue prompts firms to organize real-world mixers and mental-health partnerships to sustain engagement.
Europe experiences balanced growth amid stringent GDPR oversight. A EUR 5.7 million fine on Grindr set a precedent that prompts preemptive investment in consent management tools. Northern Europe posts the highest per-capita usage, while Southern markets catch up as dating app stigma eases. Brexit complicates cross-border data flows for operators serving the UK and EU, forcing data-residency solutions that raise infrastructure expenses. Identity-based and relationship-focused apps gain traction in culturally conservative pockets, broadening the competitive field.
- Match Group, Inc.
- Bumble Inc.
- Grindr LLC
- The Meet Group, Inc.
- Spark Networks SE
- Coffee Meets Bagel, Inc.
- Happn SAS
- Hello Group Ltd.
- Zhenai Holding Ltd.
- TrulyMadly Matchmakers Pvt Ltd.
- ParshipMeet Holding GmbH
- Cupid Media Pty Ltd.
- Love Group Global Ltd.
- HER (Bloomer Inc.)
- Feeld Ltd.
- HAPPIER Pte Ltd.
- Once Dating Group
- Blued (BlueCity Holdings Ltd.)
- Shaadi.com (People Interactive Pvt Ltd.)
- Tawkify, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Gen-Z and Millennial Willingness to Pay for Premium Matchmaking Features
- 4.2.2 Growing Acceptance of Niche & Identity-Based Platforms (e.g., Faith-based, LGBTQ+) in North America & Europe
- 4.2.3 AI-Led Personalization Improving Match Success Rates in Asia
- 4.2.4 Integrations with Social-Commerce & Live-Streaming in China and SEA
- 4.2.5 5G-Enabled Video-First Dating Formats Driving User-Time-Spent
- 4.3 Market Restraints
- 4.3.1 Escalating Privacy-Regulation Costs under GDPR & California CPRA
- 4.3.2 Rising User Fatigue & App-Deletion Rates in Saturated Urban Clusters
- 4.3.3 Payment-Fraud & Charge-back Losses on Micro-Transactions
- 4.3.4 Cultural Push-back in MEA on Liberal Dating Norms
- 4.4 Value-Chain Analysis
- 4.5 Regulatory Outlook (Data-Protection & Age-Verification Mandates)
- 4.6 Technological Outlook (Generative-AI Matchmaking, AR/VR Dates)
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macro Economic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Type
- 5.1.1 Paying Online Dating
- 5.1.2 Non-Paying Online Dating
- 5.2 By Revenue Model
- 5.2.1 Subscription
- 5.2.2 Advertising-Supported
- 5.2.3 Other Model
- 5.3 By Platform
- 5.3.1 Web Portals
- 5.3.2 Applications
- 5.4 By Age Group
- 5.4.1 Adult
- 5.4.2 Baby Boomer
- 5.4.3 Generation X
- 5.4.4 Generation Z
- 5.4.5 Millennials
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Nordics
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Funding, Partnerships)
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.4.1 Match Group, Inc.
- 6.4.2 Bumble Inc.
- 6.4.3 Grindr LLC
- 6.4.4 The Meet Group, Inc.
- 6.4.5 Spark Networks SE
- 6.4.6 Coffee Meets Bagel, Inc.
- 6.4.7 Happn SAS
- 6.4.8 Hello Group Ltd.
- 6.4.9 Zhenai Holding Ltd.
- 6.4.10 TrulyMadly Matchmakers Pvt Ltd.
- 6.4.11 ParshipMeet Holding GmbH
- 6.4.12 Cupid Media Pty Ltd.
- 6.4.13 Love Group Global Ltd.
- 6.4.14 HER (Bloomer Inc.)
- 6.4.15 Feeld Ltd.
- 6.4.16 HAPPIER Pte Ltd.
- 6.4.17 Once Dating Group
- 6.4.18 Blued (BlueCity Holdings Ltd.)
- 6.4.19 Shaadi.com (People Interactive Pvt Ltd.)
- 6.4.20 Tawkify, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

