PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114000

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114000
Industrial Gas Turbine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, industrial gas turbine market size in 2026 is estimated at USD 10.35 billion, growing from 2025 value of USD 9.72 billion with 2031 projections showing USD 14.14 billion, growing at 6.45% CAGR over 2026-2031.
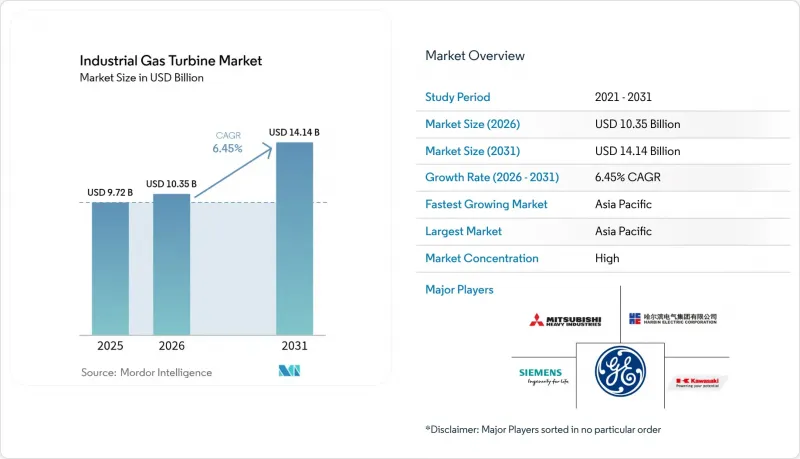
This report is Segmented by Capacity (1 To 40 MW, 41 To 120 MW, 121 To 300 MW, and Above 300 MW), Frame Type (Aero-Derivative and Heavy-Duty), Cycle (Simple Cycle and Combined Cycle), Application (Power Utilities, Oil and Gas, Industrial CHP, and Marine and Others), and Geography (North America, Europe, Asia Pacific, South America, and Middle East and Africa).
Global Industrial Gas Turbine Market Trends and Insights
Rising Power Demand in Emerging Economies
Nigeria's 1,350 MW plant, Vietnam's plan for 84 GW of LNG-based capacity by 2035, and Tanzania's first combined-cycle facility illustrate how developing nations leapfrog to cleaner gas technology to meet industrialization-driven consumption spikes. Export-credit agencies and multilateral lenders, such as the U.S. International Development Finance Corporation, underpin project bankability, accelerating turbine orders across sub-Saharan Africa. Given their fast-ramp capability and lower particulate emissions compared to coal, regional policymakers view gas turbines as pragmatic complements to renewables.
Coal-to-Gas Shift in Utility Generation Mix
Utilities replacing coal with high-efficiency combined-cycle plants report up to 70% CO2 reductions and capital cost savings of 30% versus greenfield builds by reusing existing infrastructure. Asian projects such as Guangdong Huizhou deploy 9HA-class turbines capable of 10% hydrogen blends today, with roadmaps to 100%, aligning national decarbonization policies with grid reliability. Cumulative coal-to-gas conversions have already averted 500 million t of CO2 since 2010, underscoring the transition's climate significance.
Renewables' LCOE Under-Cutting Gas
Solar PV costs have plummeted by 90% since 2010 to USD 0.044/kWh, and 81% of new renewables outperform fossil alternatives in price in 2023. Dispatchable value keeps combined-cycle plants competitive where grid services command a premium. Gas turbines, therefore, pivot from baseload to flexible peakers, demanding design upgrades for rapid cycling.
Other drivers and restraints analyzed in the detailed report include:
- Renewable-Balancing Flexibility Needs
- Data-Center CHP Build-Out Surge
- Natural-Gas Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Above-300 MW machines accounted for 50.10% of the industrial gas turbine market share in 2025, favored for their capital efficiency and readiness for carbon capture. A flagship 5,300 MW Thai complex using eight M701JAC units illustrates the scale benefits of these giants. In parallel, the 120-300 MW class, the fastest-growing segment at a 9.42% CAGR, caters to modular power schemes, microgrids, and distributed generation. Such projects align perfectly with climate-resilient grid strategies and staged investment models. Supply chain limitations constrain ultralarge frame production slots until 2031, driving customers toward the mid-range, where lead times are shorter and shipment logistics simpler.
OEMs continuously refine combustion systems for both classes, initially targeting 50% hydrogen blends and pathways to 100% by upgrading burners and control software. The mid-range units' industrial gas turbine market size is projected to expand significantly as governments incentivize the rapid deployment of low-carbon capacity.
Heavy-duty configurations secured 69.20% of 2025 revenue, a testament to their multidecade lifecycle in baseload service. Efficiency now exceeds 64% in combined-cycle mode with the latest HL platforms. Aero-derivative packages, which account for just 30.80% of revenue, are expected to expand at an 8.2% CAGR through 2031, driven by demand for 10-50 MW blocks that can cold-start in minutes. LM2500XPRESS units, for instance, shave construction schedules by 40% and accept 35% green hydrogen from day one. Heavy-duty vendors address this by modularizing auxiliary skids and shortening outage windows, thereby narrowing the total-cost-of-ownership gaps with the aero-fleet.
Complete Report Scope:
- By Capacity
- 1 to 40 MW
- 41 to 120 MW
- 121 to 300 MW
- Above 300 MW
- By Frame Type
- Aero-derivative
- Heavy-duty
- By Cycle
- Simple Cycle
- Combined Cycle
- By Application
- Power Utilities
- Oil and Gas
- Industrial CHP
- Marine and Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Australia
- Rest of Asia Pacific
- South America
- Argentina
- Brazil
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
The Asia-Pacific region accounted for 45.60% of global revenue in 2025, driven by coal-to-gas transitions, relentless urbanization, and state-backed investment. China's hydrogen-ready Zhoushan project and Vietnam's 84 GW LNG roadmap exemplify policy commitment to swift decarbonization without compromising energy security. India's upgrading of gas pipeline infrastructure and Australia's peaking-plant mandates further reinforce regional appetite. The Asia-Pacific's industrial gas turbine market is the world's largest and is projected to grow at a 6.75% CAGR in the region.
North America's mature fleet continues to expand through data center CHP and renewable projects. Duke Energy's booking of up to 11 American-made 7HA turbines speaks to robust domestic demand, heavy states. Europe's focus has shifted to hydrogen readiness and carbon-capture-enabled technologies, as seen in EnBW's Stuttgart-Munster installation. In the Middle East, Vision 2030 initiatives translate into multigigawatt tenders in Saudi Arabia and the UAE, where natural gas remains a strategic bridge fuel. Africa showcases several projects, such as Nigeria's 1,350 MW plant, which will supply 11% of the nation's demand. South America selectively adds high-efficiency combined-cycle stations, with Brazil emphasizing dispatchable capacity to firm its hydro-dominant grid.
- GE Vernova (General Electric)
- Siemens Energy
- Mitsubishi Power
- Ansaldo Energia
- Harbin Electric
- Bharat Heavy Electricals
- Kawasaki Heavy Industries
- Solar Turbines (Caterpillar)
- MAN Energy Solutions
- MTU Aero / Vericor
- Baker Hughes
- Rolls-Royce Power Systems
- Doosan Enerbility
- Shanghai Electric
- Capstone Green Energy
- OPRA Turbines
- Triveni Turbines
- Alstom (GE Gas Power heritage)
- Elliott Group
- Centrax Industries
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising power demand in emerging economies
- 4.2.2 Coal-to-gas shift in utility generation mix
- 4.2.3 Renewable-balancing flexibility needs
- 4.2.4 Data-center CHP build-out surge
- 4.2.5 Hydrogen-ready industrial retrofits
- 4.2.6 Mobile modular turbines for climate-resilient grids
- 4.3 Market Restraints
- 4.3.1 Renewables LCOE under-cutting gas
- 4.3.2 Natural-gas price volatility
- 4.3.3 Carbon-border tariffs on gas-based exports
- 4.3.4 Forging & super-alloy supply-chain bottlenecks
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook (Hydrogen, Ammonia, CCUS)
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Capacity
- 5.1.1 1 to 40 MW
- 5.1.2 41 to 120 MW
- 5.1.3 121 to 300 MW
- 5.1.4 Above 300 MW
- 5.2 By Frame Type
- 5.2.1 Aero-derivative
- 5.2.2 Heavy-duty
- 5.3 By Cycle
- 5.3.1 Simple Cycle
- 5.3.2 Combined Cycle
- 5.4 By Application
- 5.4.1 Power Utilities
- 5.4.2 Oil and Gas
- 5.4.3 Industrial CHP
- 5.4.4 Marine and Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Australia
- 5.5.3.7 Rest of Asia Pacific
- 5.5.4 South America
- 5.5.4.1 Argentina
- 5.5.4.2 Brazil
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 GE Vernova (General Electric)
- 6.4.2 Siemens Energy
- 6.4.3 Mitsubishi Power
- 6.4.4 Ansaldo Energia
- 6.4.5 Harbin Electric
- 6.4.6 Bharat Heavy Electricals
- 6.4.7 Kawasaki Heavy Industries
- 6.4.8 Solar Turbines (Caterpillar)
- 6.4.9 MAN Energy Solutions
- 6.4.10 MTU Aero / Vericor
- 6.4.11 Baker Hughes
- 6.4.12 Rolls-Royce Power Systems
- 6.4.13 Doosan Enerbility
- 6.4.14 Shanghai Electric
- 6.4.15 Capstone Green Energy
- 6.4.16 OPRA Turbines
- 6.4.17 Triveni Turbines
- 6.4.18 Alstom (GE Gas Power heritage)
- 6.4.19 Elliott Group
- 6.4.20 Centrax Industries
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

