PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114387

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114387
Digital Out Of Home (OOH) Advertising - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the digital out of home (OOH) advertising market size reached USD 20.22 billion in 2026 and is projected to advance at a 10.28% CAGR to USD 32.98 billion in 2031.
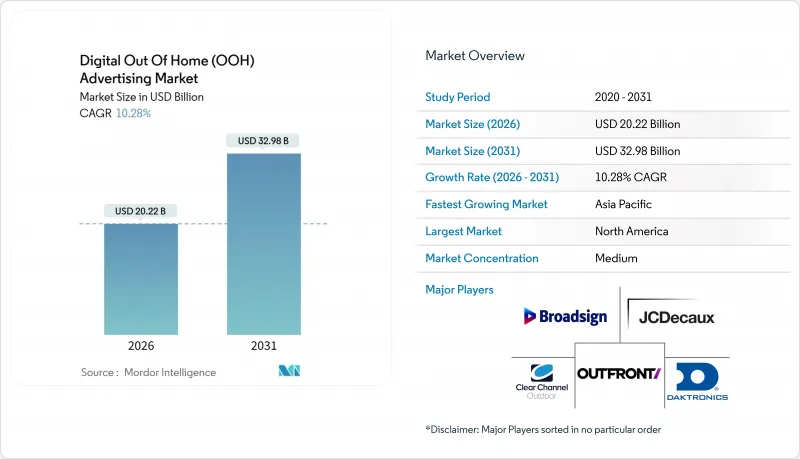
This report is Segmented by Format (Digital Billboards, Transit Displays, Street Furniture, and Place-Based and Venue Screens), Screen Technology (LED, LCD, Projection and Other), Location (Outdoor, and Indoor), End-User Vertical (Retail, Healthcare and Pharmaceuticals, Financial Services, Automotive, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Digital Out Of Home (OOH) Advertising Market Trends and Insights
Smart-City Investments Driving Programmatic DOOH Uptake in Asia-Pacific
Municipal authorities in Singapore, Hong Kong, and Vietnam are treating digital kiosks and bus shelters as dual-use assets that deliver civic information and generate advertising revenue. Singapore's GovTech integrated real-time transit data with 1,200 metro screens, allowing inventory to toggle between way-finding and paid messaging depending on passenger flow. Hong Kong's Smart City Blueprint 2.0 mandates programmatic ad-serving capability for new public installations, streamlining cross-border buys for regional brands. Hanoi's 2024 master plan earmarked USD 1.2 billion for 5,000 screens in transit hubs by 2028. Long-tenure concessions encourage operators to finance rapid digitization, compressing payback periods and attracting private equity.
5G-Enabled Real-Time Content Delivery Boosting Highway Screens in North America
Nationwide 5G now covers 87% of the U.S. population, enabling sub-100-millisecond latency that allows billboards to swap creative based on traffic or weather triggers. Mobile carriers have installed more than 150,000 5G cell sites, many along highway corridors, reducing backhaul costs for operators. Advertisers reward the flexibility with 15-20% higher CPMs compared with 4G-connected inventory. Edge-compute nodes preload multiple creatives, ensuring seamless playback even when demand-side platforms bid in real time.
Municipal Energy Caps Restricting Screen Brightness Hours Across EU Urban Cores
EU directives require cities to cut public-sector energy use by 1.9% annually, prompting rules that force screens to dim or shut off overnight. Paris mandates shutdown from 1 AM to 6 AM, reducing available inventory by 20% and stripping EUR 45 million (USD 51 million) in yearly revenue from operators. Amsterdam caps brightness at 300 nits in evenings, lowering visibility and pushing advertisers to pricier daytime slots. German municipalities have begun denying permits for new commercial screens, citing environmental concerns. These localized rules fracture the European network, undercutting the scale economies on which programmatic efficiency depends.
Other drivers and restraints analyzed in the detailed report include:
- Retail Media Networks, Roll-Out Fueling In-Store DOOH Adoption in Europe
- AI-Based Audience Measurement Elevating Advertiser ROI in Transit Hubs
- Fragmented Measurement Standards Hindering Cross-Network Programmatic Buys in the U.S.
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Street furniture revenue is expected to climb at an 11.20% CAGR through 2031, outpacing all other formats. Concession renewals in London, Paris, and Singapore require operators to install thousands of digital kiosks that provide public Wi-Fi and transit data alongside advertising. This model secures long-term rights while shifting capital costs to private partners, increasing economic resilience against advertising cyclicality. Digital billboards remain dominant in sheer revenue because of 38% share in 2025, but zoning limits hinder fresh deployments near residential areas. Transit displays grow steadily inside metro and airport environments where captive audiences welcome longer dwell-time creative. Venue screens inside gyms, cinemas, and campuses broaden advertiser reach but remain fragmented due to varied ownership structures. As municipalities lean on private funding, the dual public-service and advertising role of street furniture further cements its growth trajectory.
Operators increasingly package street furniture within broader mobility ecosystems, using anonymized sensor data to coordinate public alerts and commercial content. This infrastructure-as-a-service positioning insulates contracts from backlash against pure commercial clutter. In Asia-Pacific, street furniture also serves as a springboard for facial-recognition ticketing pilots, raising privacy debates but enhancing measurement sophistication. The cumulative effect is a format that balances civic utility with commercial upside, making it the centerpiece of many smart-city master plans.
LED held 61% of 2025 revenue thanks to high brightness and falling panel costs, but projection and other technologies are pacing at 10.67% CAGR. Transparent LED tiles allow retailers to overlay digital content on window displays, merging out-of-store reach with in-store engagement. Laser projection and holography create immersive activations in airports and flagship stores without the structural load of heavy panels. Energy-efficient e-paper pilots in Germany consume 99% less power, appealing in cities grappling with energy caps. LCD usage is shrinking outdoors because of glare and power draw, but it retains a niche for menu boards and lobbies where ambient light is controlled.
Advertisers favor novel projection formats for experiential campaigns that generate social-media buzz. PwC research shows these activations deliver more than triple the earned-media value of conventional digital spots. Operators, however, must weigh creative differentiation against maintenance complexity. Diverse hardware fleets demand specialized service teams, increasing overhead. Yet as regulatory pressure intensifies around energy and light pollution, lower-power alternatives could gain share faster than current forecasts suggest.
Complete Report Scope:
- By Format
- Digital Billboards
- Transit Displays
- Street Furniture
- Place-Based and Venue Screens
- By Screen Technology
- LED
- LCD
- Projection and Other
- By Location
- Outdoor
- Indoor
- By End-User Vertical
- Retail
- Healthcare and Pharmaceuticals
- Financial Services
- Automotive
- Telecom and Utilities
- Government and Public Sector
- Entertainment and Media
- Other End-User Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 34.50% of value in 2025. Mature programmatic infrastructure, high CPMs in tier-1 metros, and nearly ubiquitous 5G coverage enable dynamic roadside messaging that rivals mobile display in precision. Canadian growth centers on Toronto, Vancouver, and Montreal, where subway concessions fund transit operations. Mexico's progress is slower because measurement fragmentation deters global buyers, although mall deployments in Mexico City are gaining traction. Regulatory scrutiny of AI audience tracking and measurement standardization remains a headwind, potentially tempering short-term gains.
Asia-Pacific is projected to register an 11.40% CAGR, the highest worldwide. Smart-city blueprints in Singapore, Hong Kong, and Vietnam embed digital signage into public infrastructure, ensuring reliable public funding streams. China's tier-1 renovation projects are digitizing vast subway and bus networks, although escalating land-lease fees compress operator margins and stimulate consolidation. Japan's new programmatic marketplace in Tokyo and Osaka provides real-time bidding, attracting multinational advertisers seeking regional scale. India remains nascent but benefits from rapid urbanization and a broad migration from print to digital placements.
Europe's trajectory hinges on retail media network expansion and evolving regulatory frameworks. Grocers deploy extensive in-store screens tied to loyalty data that satisfy Digital Services Act requirements for advertising transparency. Energy-consumption limits force outdoor operators to dim screens at night, reducing available impressions and shifting spend to indoor environments. Despite these constraints, metro systems in London, Paris, and Berlin continue to digitize, supported by public-private revenue-sharing models. The Middle East and Africa region accelerates through sovereign megaprojects in United Arab Emirates and Saudi Arabia, where urban master plans allocate thousands of screens as part of tourism and transit hubs. South America remains smaller but is picking up pace in Brazil and Chile, with mall and metro projects seeking to counterbalance macroeconomic volatility.
- JCDecaux SA
- Clear Channel Outdoor Holdings, Inc.
- Outfront Media Inc.
- Lamar Advertising Company
- Stroer SE & Co. KGaA
- Talon Outdoor Limited
- oOh!media Limited
- QMS Media Limited
- Ocean Outdoor Limited
- Broadsign International, LLC
- Daktronics, Inc.
- SevenOne Media GmbH
- Asiaray Media Group Limited
- Pattison Outdoor Advertising LP
- Global Media & Entertainment Limited
- APG|SGA SA
- Exterion Media Group Limited
- AdShel Pty Ltd
- EyeMedia LLC
- E Ink Holdings Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Smart-City Investments Driving Programmatic DOOH Uptake in Asia-Pacific
- 4.2.2 5G-Enabled Real-Time Content Delivery Boosting Highway Screen Utilisation in North America
- 4.2.3 Retail Media Networks' Roll-Out Fueling In-Store DOOH Adoption in Europe
- 4.2.4 AI-Based Audience Measurement Elevating Advertiser ROI in Major Transit Hubs
- 4.2.5 Carbon-Neutral LED Displays Attracting Sustainability-Focused Brands
- 4.2.6 Government Mega-Projects Accelerating DOOH Spend in Middle-East Smart Cities
- 4.3 Market Restraints
- 4.3.1 Municipal Energy Caps Restricting Screen Brightness Hours Across EU Urban Cores
- 4.3.2 Fragmented Measurement Standards Hindering Cross-Network Programmatic Buys in the U.S.
- 4.3.3 Escalating Urban Land-Lease Fees Raising Billboard Deployment Costs in Tier-1 Chinese Cities
- 4.3.4 Ad-Fraud Risks Around Spoofed pDOOH Impressions Curtailing Global FMCG Budgets
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Industry Value-Chain Analysis
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Format
- 5.1.1 Digital Billboards
- 5.1.2 Transit Displays
- 5.1.3 Street Furniture
- 5.1.4 Place-Based and Venue Screens
- 5.2 By Screen Technology
- 5.2.1 LED
- 5.2.2 LCD
- 5.2.3 Projection and Other
- 5.3 By Location
- 5.3.1 Outdoor
- 5.3.2 Indoor
- 5.4 By End-User Vertical
- 5.4.1 Retail
- 5.4.2 Healthcare and Pharmaceuticals
- 5.4.3 Financial Services
- 5.4.4 Automotive
- 5.4.5 Telecom and Utilities
- 5.4.6 Government and Public Sector
- 5.4.7 Entertainment and Media
- 5.4.8 Other End-User Verticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Strategic Developments
- 6.2 Vendor Positioning Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 JCDecaux SA
- 6.3.2 Clear Channel Outdoor Holdings, Inc.
- 6.3.3 Outfront Media Inc.
- 6.3.4 Lamar Advertising Company
- 6.3.5 Stroer SE & Co. KGaA
- 6.3.6 Talon Outdoor Limited
- 6.3.7 oOh!media Limited
- 6.3.8 QMS Media Limited
- 6.3.9 Ocean Outdoor Limited
- 6.3.10 Broadsign International, LLC
- 6.3.11 Daktronics, Inc.
- 6.3.12 SevenOne Media GmbH
- 6.3.13 Asiaray Media Group Limited
- 6.3.14 Pattison Outdoor Advertising LP
- 6.3.15 Global Media & Entertainment Limited
- 6.3.16 APG|SGA SA
- 6.3.17 Exterion Media Group Limited
- 6.3.18 AdShel Pty Ltd
- 6.3.19 EyeMedia LLC
- 6.3.20 E Ink Holdings Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

