PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115084

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115084
Ship Port Infrastructure - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, ship port infrastructure market size in 2026 is estimated at USD 221.61 billion, growing from 2025 value of USD 211.68 billion with 2031 projections showing USD 278.62 billion, growing at 4.69% CAGR over 2026-2031.
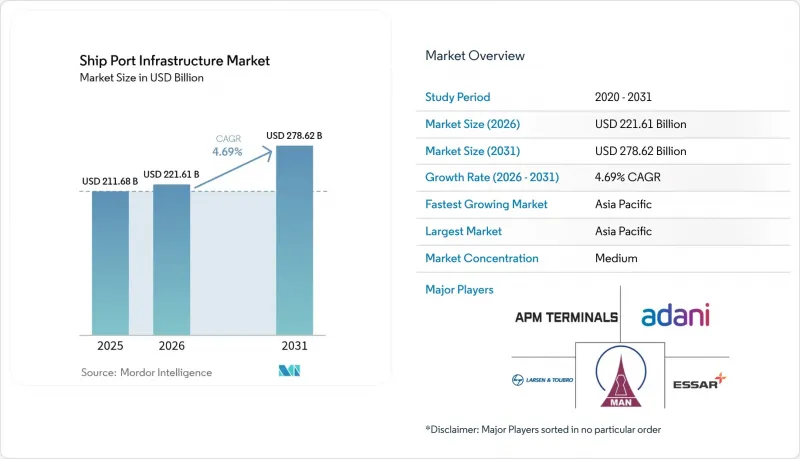
This report is Segmented by Port Type (Seaport, Inland Port, and More), Application (Cargo and Passenger), Ownership Model (Public and Private), Technology Adoption Level (Conventional, Semi-Automated, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Ship Port Infrastructure Market Trends and Insights
Expansionary Public-Sector Port Modernization Budgets
Government spending is reshaping capacity and technology priorities across the ship port infrastructure market. The United States allocated USD 580 million to 31 projects in 2024, while California ring-fenced USD 2.3 billion for port improvements that bundle berth expansion with digital yard-management platforms. Similar momentum is visible in the European Union's Connecting Europe Facility, which co-finances shore-power deployment and intermodal upgrades. Blended-finance structures enable quicker execution, as shown by DP World's USD 1.2 billion London Gateway phase-II build that combines public guarantees with private equity.Ports securing multi-source funding can synchronise civil works expansion with automation roll-outs, compressing payback periods by lifting throughput per hectare. Yet capacity gains hinge on hinterland connectivity; berth productivity fails to translate into end-to-end velocity without rail-and-road alignment.
Rapid Container-Terminal Automation & Private-5G Roll-Outs
Automation is accelerating as terminals confront labour shortages and volatility in collective bargaining. Singapore's Tuas Port operates more than 200 driverless vehicles under a private 5G network that supports millisecond equipment hand-offs, cutting unproductive moves by 20%. China leads with 52 automated berths online and 27 under construction, validating systems' economies of scale. Early adopters nevertheless gain a structural cost edge when industrial action halts manual peers, making automation the decisive differentiator for volume-sensitive carriers.
Multi-Billion-Dollar Upfront Capital Requirement & Long Pay-Back
Full automation and berth deepening stretch balance sheets across the ship port infrastructure market. Projects exceed, and lenders demand covenants tied to throughput guarantees, creating hurdles for midsize operators. Technology obsolescence risk further complicates underwriting; equipment cycles shrink as software-defined cranes replace mechanical upgrades every five years. Consequently, smaller concessions may pivot to phased semi-automation as an interim hedge.
Other drivers and restraints analyzed in the detailed report include:
- Mandatory IMO Decarbonisation Timelines Accelerating Green-Retrofit Capex
- Near-Shoring Shifts Cargo Flows to Secondary Seaports
- Labour-Union Resistance to Full Automation at Legacy Hubs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Seaports continue to dominate the ship port infrastructure market size, accounting for an 86.62% share in 2025, as only coastal facilities can berth ultra-large vessels. This dominance anchors the ship port infrastructure market size at the high end of the capital allocation spectrum, driving dredging, breakwater reinforcement, and automation outlays that dwarf those of inland and offshore installations. Volume visibility attracts third-party logistics providers and fintech platforms, creating network effects that reinforce seaport hegemony.
Seaport investments center on tandem-lift quay cranes, AI-enabled stack management, and on-dock rail integration, which can reduce truck idling by 30%. Inland ports, which will grow at a CAGR of 4.82% by 2031, leverage rail economics; the Port of Nevada's 224-acre site processes remote customs clearance and rail transloading, which remove 600 daily truck trips from congested interstate corridors. Growth potential is spurred by e-commerce fulfillment centers migrating inland, signaling that the ship port infrastructure market will witness a nuanced balance between coastal scalability and interior agility.
Cargo handling represented 90.55% of the total ship port infrastructure market share in 2025, anchoring the market. Terminal operators funnel capital toward automated stacking cranes, optical gate systems, and blockchain-linked documentation that eliminate manual reconciliation delays. Container dwell time has become the principal metric through which investors benchmark asset productivity.
Passenger activities grow at a CAGR of 4.81% through 2031, cruise and ferry terminals are rebounding as vaccination passports and pent-up travel demand lift bookings. Ports in the Mediterranean and Caribbean are refurbishing embarkation lounges and installing LNG bunkering to serve new dual-fuel cruise ships. Higher spend per docked passenger offsets seasonal volatility, diversifies income streams, and raises asset valuations within the broader ship port infrastructure industry.
Complete Report Scope:
- By Port Type
- Seaport
- Inland Port
- Offshore/Other
- By Application
- Cargo
- Passenger
- By Ownership Model
- Public
- Private
- By Technology Adoption Level
- Conventional
- Semi-Automated
- Fully-Automated
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of Asia Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Turkey
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia Pacific led the ship port infrastructure market share with a 38.42% regional share in 2025 and remains the fastest-growing territory at a 4.72% CAGR. China's 52 automated berths and a national strategy that treats terminals as smart-manufacturing nodes gave Shanghai the first 50 million TEU throughput record in history. South Korea's Busan added an automated phase that lifted yard density by 20%, illustrating how technology leapfrogging corrects land constraints. Although geopolitical frictions pose downside risk, regional governments continue to pour capex into digital-rail corridors that funnel hinterland exports to coastal hubs.
Europe maintains efficiency leadership in sustainability. Rotterdam's 6.8 benefit-to-cost ratio adaptation plan channels EUR 2 billion into flood-barriers, ammonia bunkering, and green hydrogen pipelines. Hamburg's Altenwerder terminal operates climate-neutral equipment and has become a test-bed for electricity-as-a-service models that shift battery ownership to utilities, reducing operator capex. Regulatory frameworks such as FuelEU Maritime reward early movers by extending green-corridor incentives to shipping lines that call at low-carbon ports, enriching the strategic profile of the ship port infrastructure market.
North America lags on automation but benefits from near-shoring and federal grants. The USD 580 million Port Infrastructure Development Program funnels funds toward berth rehabilitation and electrified rubber-tyred gantry cranes at Los Angeles and Long Beach. Labour uncertainty remains the region's Achilles heel; the 2024 strike pushed carriers to divert 9% of Transpacific volumes to Mexican and Canadian gateways.
- PSA International
- Hutchison Ports
- APM Terminals
- DP World
- China COSCO Shipping Ports
- China Merchants Port Holdings
- Terminal Investment Ltd (MSC)
- Adani Ports & SEZ
- AD Ports Group
- Ports America
- SSA Marine
- ICTSI
- Yilport Holding
- Eurogate Group
- Gulftainer
- Man Infraconstruction
- Essar Ports
- Gujarat Maritime Board
- ZPMC
- Larsen & Toubro
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansionary public-sector port modernization budgets
- 4.2.2 Rapid container-terminal automation & private-5G roll-outs
- 4.2.3 Mandatory IMO/ICS decarbonisation timelines accelerating green-retrofit capex
- 4.2.4 Near-shoring shifting cargo flows to secondary seaports
- 4.2.5 Resilience investments against climate-linked chokepoint disruptions
- 4.2.6 Rapid build-out of specialized bulk terminals
- 4.3 Market Restraints
- 4.3.1 Multi-billion-dollar upfront capital requirement & long pay-back
- 4.3.2 Labour-union resistance to full automation at legacy hubs
- 4.3.3 Growing cyber-security vulnerabilities in OT/IT convergence
- 4.3.4 Escalating annual dredging costs as stricter environmental regulations
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Port Type
- 5.1.1 Seaport
- 5.1.2 Inland Port
- 5.1.3 Offshore/Other
- 5.2 By Application
- 5.2.1 Cargo
- 5.2.2 Passenger
- 5.3 By Ownership Model
- 5.3.1 Public
- 5.3.2 Private
- 5.4 By Technology Adoption Level
- 5.4.1 Conventional
- 5.4.2 Semi-Automated
- 5.4.3 Fully-Automated
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Netherlands
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Turkey
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 PSA International
- 6.4.2 Hutchison Ports
- 6.4.3 APM Terminals
- 6.4.4 DP World
- 6.4.5 China COSCO Shipping Ports
- 6.4.6 China Merchants Port Holdings
- 6.4.7 Terminal Investment Ltd (MSC)
- 6.4.8 Adani Ports & SEZ
- 6.4.9 AD Ports Group
- 6.4.10 Ports America
- 6.4.11 SSA Marine
- 6.4.12 ICTSI
- 6.4.13 Yilport Holding
- 6.4.14 Eurogate Group
- 6.4.15 Gulftainer
- 6.4.16 Man Infraconstruction
- 6.4.17 Essar Ports
- 6.4.18 Gujarat Maritime Board
- 6.4.19 ZPMC
- 6.4.20 Larsen & Toubro
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

