PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115830

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115830
Europe ADAS - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Europe ADAS market size was valued at USD 35.54 billion in 2025 and estimated to grow from USD 39.05 billion in 2026 to reach USD 62.61 billion by 2031, at a CAGR of 9.89% during the forecast period (2026-2031).
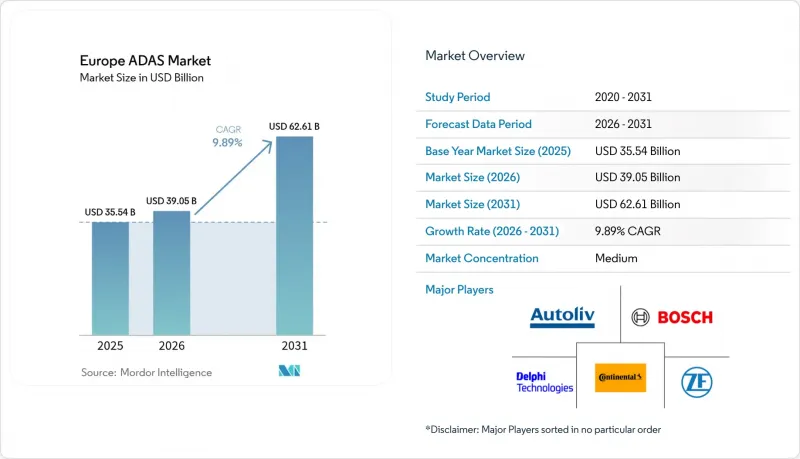
This report is Segmented by System Type (Parking Assist Systems and More), Sensor Type (Radar, Lidar, Camera, Ultrasonic, and Infra-Red), Vehicle Type (Two-Wheelers, Passenger Cars, and More), Level of Autonomy (Level 1, Level 2, Level 3, Level 4, and Level 5), Sales Channel (OEM-Fitted and Aftermarket Retrofit), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe ADAS Market Trends and Insights
EU General Safety Regulation 2024 Mandate
The regulation requires automatic emergency braking, lane departure warning, and driver drowsiness detection across every new vehicle category sold in the bloc. Entry-level passenger cars, motorcycles, and agricultural machinery must meet identical baseline safety specifications, forcing OEMs to accelerate procurement schedules that have already filled Tier 1 order books through 2026. Non-compliant models lose type approval, creating a hard stop on regional market access and giving early certified suppliers guaranteed volume visibility .
EURO NCAP 2030 Vision Roadmap Alignment
Euro NCAP's staged roadmap sets performance thresholds higher than legislative minima, requiring OEMs to demonstrate cyclist, pedestrian, and motorcyclist recognition in complex mixed-traffic conditions. These protocols reward systems that fuse radar, camera, and LiDAR inputs to handle adverse weather, nighttime, and construction zones. Ratings directly influence fleet procurement and insurance pricing, pushing manufacturers toward continuous sensor and software upgrades that favor suppliers with iterative validation capacity.
High Incremental Cost For Entry-Level Vehicles
City-car platforms now face an added cost due to the integration of ADAS hardware and electronics. This development forces OEMs to either absorb the margin pressure or potentially alienate budget-conscious buyers in Eastern Europe and southern markets. Meanwhile, smaller manufacturers, without the advantage of global scale, find it challenging to distribute engineering overheads. As a result, they face an extended affordability gap, awaiting a significant drop in semiconductor prices.
Other drivers and restraints analyzed in the detailed report include:
- Mass-Market Level 2 Feature Bundling Surge
- 77 GHz Radar Cost Decline & Platform Standardization
- Sensor Performance Loss In Snow/Fog Conditions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Automatic emergency braking held 22.74% of the European ADAS market share in 2025, a position cemented when the 2024 General Safety Regulation made the feature mandatory across new registrations. The Europe ADAS market size for night-vision solutions is forecast to grow exponentially by 2031, translating into a 10.04% CAGR as thermal cameras mitigate fog and darkness and help brands differentiate in premium tiers. Forward-collision warning, lane-departure warning, and adaptive cruise control continue to ship in volume bundles, reinforcing pathway migration from reactive to predictive functions that anticipate driver intent.
OEM roadmaps increasingly fuse parking, blind-spot, and drowsiness modules into unified domain controllers that consolidate ECUs and cut wiring complexity. GDPR-compliant drowsiness monitoring expands slowly due to privacy safeguards, yet remains critical for Euro NCAP scoring. Adaptive lighting systems add matrix-LED capabilities that optimize beam patterns without blinding oncoming traffic, positioning illumination control as a safety and energy efficiency play. These converging trends confirm the European ADAS market as a hardware-software ecosystem in which modular safety building blocks become firmware features upgradeable over a vehicle's lifetime.
Radar sensors retained 37.10% of the European ADAS market share in 2025, benefiting from USD 32 mid-range module pricing, robust all-weather performance, and regulatory familiarity. The Europe ADAS market size for LiDAR is projected to grow significantly by 2031, riding a 10.06% CAGR once unit pricing falls toward USD 500 and Euro NCAP stresses vulnerable road-user protection. Cameras remain indispensable for lane-line and traffic-sign recognition, yet face snow occlusion issues that elevate the value proposition of thermal and radar fusion.
Continental's 77 GHz MIMO radar arrays deliver finer resolution while conserving package space, protecting the radar's core highway role. Simultaneously, Valeo's solid-state LiDAR price cuts push the sensor into high-volume C-segment crossovers, a milestone that rebalances sensory hierarchies. Integrated perception stacks merge radar velocity, camera semantics, and LiDAR depth into single ECUs, lowering latency and creating redundancy demanded for Level 3 approvals. This integration accelerates supplier consolidation inside the European ADAS market, with OEMs favoring turnkey sensor suites that minimize validation loops.
Complete Report Scope:
- By System Type
- Parking Assist Systems
- Adaptive Front-Lighting
- Night Vision Systems
- Blind-Spot Detection
- Automatic Emergency Braking
- Forward Collision Warning
- Driver Drowsiness Alert
- Traffic Sign Recognition
- Lane Departure Warning
- Adaptive Cruise Control
- By Sensor Type
- Radar
- LiDAR
- Camera
- Ultrasonic
- Infra-red
- By Vehicle Type
- Two-Wheelers
- Passenger Cars
- Medium & Heavy Commercial Vehicles
- By Level of Autonomy
- Level 1
- Level 2
- Level 3
- Level 4
- Level 5
- By Sales Channel
- OEM-Fitted
- Aftermarket Retrofit
- By Geography
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
List of Companies Covered in this Report:
- Robert Bosch GmbH
- Continental AG
- ZF Friedrichshafen AG
- Valeo SA
- Aptiv PLC
- Autoliv Inc.
- Denso Corporation
- Hella KGaA Hueck & Co.
- Mobileye (NXP/Intel)
- Infineon Technologies AG
- Magna International Inc.
- NXP Semiconductors NV
- STMicroelectronics N.V.
- Panasonic Corp.
- Renesas Electronics Corp.
- Hyundai Mobis Co. Ltd.
- Veoneer AB
- Texas Instruments Inc.
- Innoviz Technologies Ltd.
- Ibeo Automotive Systems GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU General Safety Regulation 2024 Mandate
- 4.2.2 EURO NCAP 2030 Vision Roadmap Alignment
- 4.2.3 Mass-Market Level 2 Feature Bundling Surge
- 4.2.4 77 GHZ Radar Cost Decline & Platform Standardization
- 4.2.5 OTA-Based Adas Feature Monetization Models
- 4.2.6 Digital-Twin Homologation Frameworks
- 4.3 Market Restraints
- 4.3.1 High Incremental Cost For Entry-Level Vehicles
- 4.3.2 Sensor Performance Loss In Snow/Fog Conditions
- 4.3.3 GDPR Compliance Cost For Driver-Monitoring Cameras
- 4.3.4 Gallium Export Controls Hitting Lidar Supply
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By System Type
- 5.1.1 Parking Assist Systems
- 5.1.2 Adaptive Front-Lighting
- 5.1.3 Night Vision Systems
- 5.1.4 Blind-Spot Detection
- 5.1.5 Automatic Emergency Braking
- 5.1.6 Forward Collision Warning
- 5.1.7 Driver Drowsiness Alert
- 5.1.8 Traffic Sign Recognition
- 5.1.9 Lane Departure Warning
- 5.1.10 Adaptive Cruise Control
- 5.2 By Sensor Type
- 5.2.1 Radar
- 5.2.2 LiDAR
- 5.2.3 Camera
- 5.2.4 Ultrasonic
- 5.2.5 Infra-red
- 5.3 By Vehicle Type
- 5.3.1 Two-Wheelers
- 5.3.2 Passenger Cars
- 5.3.3 Medium & Heavy Commercial Vehicles
- 5.4 By Level of Autonomy
- 5.4.1 Level 1
- 5.4.2 Level 2
- 5.4.3 Level 3
- 5.4.4 Level 4
- 5.4.5 Level 5
- 5.5 By Sales Channel
- 5.5.1 OEM-Fitted
- 5.5.2 Aftermarket Retrofit
- 5.6 By Geography
- 5.6.1 Germany
- 5.6.2 United Kingdom
- 5.6.3 France
- 5.6.4 Italy
- 5.6.5 Spain
- 5.6.6 Russia
- 5.6.7 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Robert Bosch GmbH
- 6.4.2 Continental AG
- 6.4.3 ZF Friedrichshafen AG
- 6.4.4 Valeo SA
- 6.4.5 Aptiv PLC
- 6.4.6 Autoliv Inc.
- 6.4.7 Denso Corporation
- 6.4.8 Hella KGaA Hueck & Co.
- 6.4.9 Mobileye (NXP/Intel)
- 6.4.10 Infineon Technologies AG
- 6.4.11 Magna International Inc.
- 6.4.12 NXP Semiconductors NV
- 6.4.13 STMicroelectronics N.V.
- 6.4.14 Panasonic Corp.
- 6.4.15 Renesas Electronics Corp.
- 6.4.16 Hyundai Mobis Co. Ltd.
- 6.4.17 Veoneer AB
- 6.4.18 Texas Instruments Inc.
- 6.4.19 Innoviz Technologies Ltd.
- 6.4.20 Ibeo Automotive Systems GmbH
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

