PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116596

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116596
India Automotive Advanced Driver Assistance Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the indian automotive advanced driver assistance systems market size was valued at USD 1.15 billion in 2025 and estimated to grow from USD 1.36 billion in 2026 to reach USD 3.12 billion by 2031, at a CAGR of 18.12% during the forecast period (2026-2031).
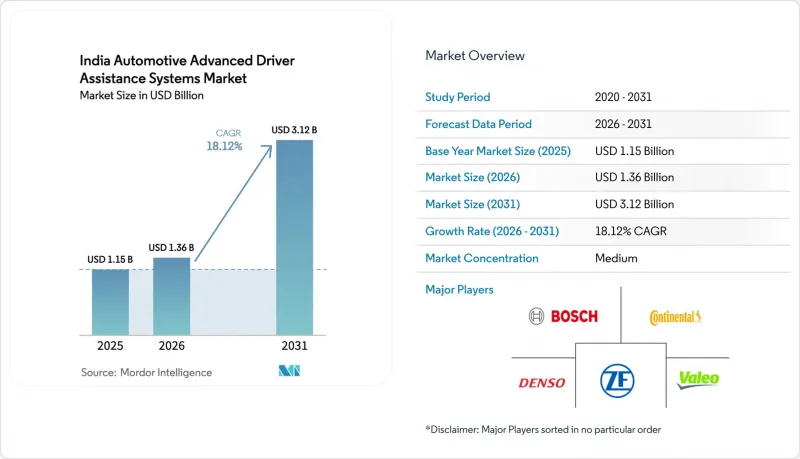
This report is Segmented by System Type (Parking Assist Systems, Adaptive Front-Lighting, and More), Sensor Technology (Radar, Lidar, Camera, Ultrasonic, and More), Vehicle Type (Two-Wheelers, Passenger Cars, and More), Level of Autonomy (L1, L2, L3, and More), and Sales Channel (OEM-Fitted and Aftermarket Retrofit). The Market Forecasts are Provided in Terms of Value (USD).
India Automotive Advanced Driver Assistance Systems Market Trends and Insights
Bharat-NCAP Safety Mandate Accelerates OEM Fitment
The new Bharat NCAP protocol converts ADAS from a premium differentiator into a legal requirement across passenger and commercial platforms, forcing automakers to embed collision warning and automatic braking as standard equipment. Honda has already placed several ADAS-equipped vehicles on Indian roads, signaling industry readiness to meet stricter star-rating thresholds. Because safety scores now figure prominently in consumer purchase decisions, OEMs re-prioritize R&D budgets toward active-safety content rather than passive hardware. Parallel proposals from the Ministry of Road Transport and Highways to broaden ADAS obligations to buses and heavy trucks extend the addressable opportunity beyond personal mobility. Early compliance also mitigates regulatory uncertainty, allowing suppliers to lock in multi-year production volumes.
Usage-Based-Insurance Discounts Tied to ADAS Adoption
Telematics-enabled "Pay As You Drive" and "Pay How You Drive" policies now offer motorists premium reductions that can reach 15-25%, providing a direct financial return on ADAS-equipped vehicles. Leading insurers such as Tata AIG, Bharti AXA, and ICICI Lombard embed real-time driving-behavior scores into underwriting, which lowers claim frequency and severity while motivating safer habits. OEMs leverage these savings in showroom messaging to justify the ADAS price uplift, particularly for first-time buyers focused on monthly outlay. Fleet operators gain an additional margin lever because lower accident ratios translate into fewer unplanned repairs and reduced downtime for delivery vehicles. Data-sharing agreements between insurers and automakers also build anonymized crash databases that refine future ADAS algorithms, creating a virtuous circle that further accelerates feature penetration.
High Incremental Vehicle Price (INR 70-90k)
Adding ADAS hardware inflates ex-showroom prices by INR 70,000-90,000 (~USD 789-1,015) or roughly 7-9% on a typical car, enough to push EMI-focused buyers toward lower trims. Consumers in value-driven A- and B-segment categories remain skeptical that insurance savings will offset the upfront outlay. Fleet operators display similar caution unless telematics proves direct accident-cost reductions. OEMs bundle ADAS only on top grades or offer limited-function packs to maintain showroom traffic, slowing penetration outside metro clusters. Over time, scale economies and stronger used-car residuals are expected to neutralize the sticker-shock barrier.
Other drivers and restraints analyzed in the detailed report include:
- PLI Incentives for Local ADAS Component Manufacturing
- Falling Radar and Camera Costs Reach Sub-USD 20/Vehicle
- Shortage of Certified ADAS-Calibration Workshops
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Adaptive Cruise Control still held the largest slice of the Indian automotive ADAS market share at 28.62% in 2025, favored by motorists traveling the Delhi-Mumbai and Hyderabad-Bangalore expressways. The Indian automotive ADAS market size attributable to collision-warning suites is expanding faster than comfort-oriented modules, underscoring a policy tilt toward active intervention. Secondary functions-Driver Drowsiness Alerts, Parking Assist, and Night Vision-ride on the same sensor stack, enabling OEMs to upsell via software toggles. Over-the-air updates keep feature roadmaps fluid, allowing manufacturers to monetize after-sales upgrades once regulatory approvals are secured.
Automatic Emergency Braking is on course for a 20.10% CAGR to 2031 as regulators and insurers converge on forward-collision mitigation metrics. Camera-centric lane departure warnings perform best on newly resurfaced corridors but struggle in patchy suburban stretches, prompting dual-sensor approaches that fuse short-range radar for lateral coverage. Traffic Sign Recognition, validated at 98% accuracy on Indian signage in a recent ICTACT Journal study, gains traction in speed-camera-dense zones where compliance avoids fines . The heightened emphasis on crash avoidance favors suppliers with proprietary datasets of local traffic idiosyncrasies, reinforcing first-mover advantages.
Camera modules benefited from smartphone-scale production, grabbing 42.70% of the Indian automotive ADAS market size in 2025. Radar's all-weather capability secures its place in sensor fusion stacks indispensable for monsoon-season reliability. LiDAR shipments, once hampered by four-figure unit pricing, now pursue a 20.55% CAGR to 2031 as solid-state architectures drop below USD 500. The Indian automotive ADAS market finds value in LiDAR's dense point clouds that resolve lane edges and vulnerable road users even in low-light or debris-laden conditions. Honda's joint project with IIT Delhi and IIT Bombay pairs LiDAR with cameras and radar to map mixed-traffic layers involving rickshaws, cyclists, and jaywalkers. Ultrasonic sensors remain essential for close-range parking assistance where centimeter-level resolution trumps long-range reach.
Evolving ECU designs integrate dedicated AI accelerators, enabling in-vehicle sensor fusion. This filter redundant signals before cloud upload, conserving bandwidth. Suppliers differentiate through power-optimized ASICs that meet India's high-temperature thresholds without active cooling, a key spend driver in compact engine bays.
Complete Report Scope:
- By System Type
- Parking Assist Systems
- Adaptive Front-Lighting
- Night Vision Systems
- Blind-Spot Detection
- Automatic Emergency Braking
- Forward Collision Warning
- Driver Drowsiness Alert
- Traffic Sign Recognition
- Lane Departure Warning
- Adaptive Cruise Control
- By Sensor Technology
- Radar
- LiDAR
- Camera
- Ultrasonic
- Infra-red
- By Vehicle Type
- Two-Wheelers
- Passenger Cars
- Medium and Heavy Commercial Vehicles
- By Level of Autonomy
- L1
- L2
- L3
- L4
- L5
- By Sales Channel
- OEM-Fitted
- Aftermarket Retrofit
List of Companies Covered in this Report:
- Robert Bosch GmbH
- Continental AG
- DENSO Corporation
- ZF Friedrichshafen AG
- Aptiv PLC
- Magna International Inc.
- Hella GmbH & Co. KGaA (FORVIA Hella)
- HL Mando Corporation
- Valeo SA
- Autoliv Inc.
- Mobileye (Intel Corporation)
- KPIT Technologies
- LeddarTech
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Bharat-NCAP Safety Mandate Accelerates OEM Fitment
- 4.2.2 Usage-Based-Insurance Discounts Tied to ADAS Adoption
- 4.2.3 PLI Incentives for Local ADAS Component Manufacturing
- 4.2.4 Falling Radar and Camera Costs Reach Sub-USD 20/Vehicle
- 4.2.5 Level 2+ ADAS Trickles to Mid-Segment Cars
- 4.2.6 Radar-Based Rider-Assistance for 2-Wheelers Emerges
- 4.3 Market Restraints
- 4.3.1 High Incremental Vehicle Price (INR 70-90k)
- 4.3.2 Shortage of Certified ADAS-Calibration Workshops
- 4.3.3 Poor Road Markings and Infrastructure Noise Sensors
- 4.3.4 AIS-189 Cybersecurity Compliance Adds ECU Cost
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By System Type
- 5.1.1 Parking Assist Systems
- 5.1.2 Adaptive Front-Lighting
- 5.1.3 Night Vision Systems
- 5.1.4 Blind-Spot Detection
- 5.1.5 Automatic Emergency Braking
- 5.1.6 Forward Collision Warning
- 5.1.7 Driver Drowsiness Alert
- 5.1.8 Traffic Sign Recognition
- 5.1.9 Lane Departure Warning
- 5.1.10 Adaptive Cruise Control
- 5.2 By Sensor Technology
- 5.2.1 Radar
- 5.2.2 LiDAR
- 5.2.3 Camera
- 5.2.4 Ultrasonic
- 5.2.5 Infra-red
- 5.3 By Vehicle Type
- 5.3.1 Two-Wheelers
- 5.3.2 Passenger Cars
- 5.3.3 Medium and Heavy Commercial Vehicles
- 5.4 By Level of Autonomy
- 5.4.1 L1
- 5.4.2 L2
- 5.4.3 L3
- 5.4.4 L4
- 5.4.5 L5
- 5.5 By Sales Channel
- 5.5.1 OEM-Fitted
- 5.5.2 Aftermarket Retrofit
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Robert Bosch GmbH
- 6.4.2 Continental AG
- 6.4.3 DENSO Corporation
- 6.4.4 ZF Friedrichshafen AG
- 6.4.5 Aptiv PLC
- 6.4.6 Magna International Inc.
- 6.4.7 Hella GmbH & Co. KGaA (FORVIA Hella)
- 6.4.8 HL Mando Corporation
- 6.4.9 Valeo SA
- 6.4.10 Autoliv Inc.
- 6.4.11 Mobileye (Intel Corporation)
- 6.4.12 KPIT Technologies
- 6.4.13 LeddarTech
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

