PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116352

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116352
United Kingdom Warehousing And Distribution Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the United Kingdom warehousing and distribution logistics market size was valued at USD 12.02 billion in 2025 and estimated to grow from USD 12.28 billion in 2026 to reach USD 13.65 billion by 2031, at a CAGR of 2.14% during the forecast period (2026-2031).
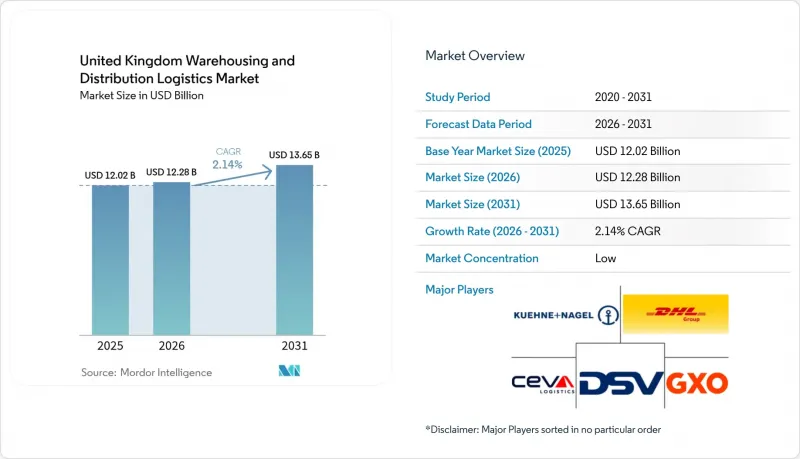
This report is Segmented by Warehouse Type (General Warehousing and Storage, Refrigerated Warehousing and Storage), Ownership (Private Warehouses, Public Warehouses), End-User Industry (E-Commerce & Retail, Food & Beverage, Pharma & Healthcare, and More), and Geography (England, Scotland, Wales, Northern Ireland). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Warehousing And Distribution Logistics Market Trends and Insights
E-commerce Fulfillment Space Surge
Escalating online retail penetration has shifted network planning toward facilities located within 50 miles of the largest urban catchments. Operators prioritize multi-story hubs and micro-fulfillment annexes that compress last-mile delivery times while supporting returns processing. Amazon's multi-year program of green-field and brown-field developments exemplifies the scale of investment, and large grocery chains now dedicate dedicated space to online picking alongside store replenishment. Extended Producer Responsibility rules for packaging, effective in 2025, add data compliance layers but simultaneously drive operational streamlining. Resulting capacity constraints in the Golden Triangle underpin premium rent growth and sustain double-digit pre-leasing rates across the United Kingdom warehousing and distribution logistics market.
Cold-Chain Growth for Grocery and Pharma
Demand for temperature-controlled facilities now outpaces ambient capacity expansion as grocery home-delivery volumes converge with pharmaceutical buffer-stock strategies. Dual-use specifications capable of +4 °C chilled to -20 °C frozen enable operators to flex between sectors and smooth asset utilization. Strategic corridors linking London, Birmingham, and the eastern ports attract multi-tenant build-to-suit projects, while nationwide distribution requires satellite cross-dock nodes closer to consumers. Adoption of natural refrigerants aligns buildings with future sustainability regulation and generates operating-cost benefits once electricity-intensive systems are powered by on-site solar arrays. This specialist capability therefore commands a rental premium of 20-25% but continues to secure long-term commitments from brand-name occupiers, enhancing revenue visibility across the United Kingdom warehousing & distribution logistics market.
Urban Land Scarcity and Rent Inflation
Vacancy across prime logistics sub-markets remains below 2%, propelling rents upward by 8% annually as occupiers compete for scarce plots inside the M25 and along the M1 corridor. Developers increasingly pursue multi-story designs or repurpose obsolete big-box retail to unlock urban footprints. However, higher land outlays translate into elevated breakeven rent thresholds that smaller retailers struggle to absorb, driving polarization toward scale players. Local authorities attempt to balance employment opportunities against community concerns but retain stringent design codes to mitigate traffic and visual impact, slowing start-to-completion cycles within the United Kingdom warehousing and distribution logistics market.
Other drivers and restraints analyzed in the detailed report include:
- Automation and Robotics Efficiency Gains
- Government Freeport and Industrial-Park Incentives
- Warehouse-Labor Shortages and Wage Spikes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Refrigerated Warehousing & Storage generated a 5.22% CAGR to 2031, comfortably ahead of the 2.14% overall growth registered by the United Kingdom warehousing & distribution logistics market size. Although General Warehousing & Storage retained 57.35% share in 2025, vacancy for high-spec cold units is virtually nonexistent, reflecting structural shifts in grocery home delivery and pharmaceutical integrity regulations. Capital intensity is higher refrigerated builds cost 40-60% more than ambient equivalents but operators pass through expenses via multi-year indexed contracts that insulate returns.
Energy-efficient chillers, IoT temperature monitoring, and modular racking improve space utilization and compliance, enabling providers to blend chilled and frozen zones on demand. Meanwhile, general warehousing leans on automation to defend margins, integrating shuttle systems and high-density pallets that reduce per-unit handling costs. Dual-certified facilities capable of toggling between cold and ambient regimes further blur segment boundaries, optimizing uptake across seasonal peaks within the United Kingdom warehousing & distribution logistics market.
Complete Report Scope:
- By Warehouse Type (Value)
- General Warehousing and Storage
- Refrigerated Warehousing and Storage
- By Ownership (Value)
- Private Warehouses
- Public Warehouses
- By End-User Industry (Value)
- E-commerce and Retail
- Food and Beverage
- Pharma and Healthcare
- Automotive
- Manufacturing and Engineering Goods
- Others
- By Region
- England
- Scotland
- Wales
- Northern Ireland
List of Companies Covered in this Report:
- DHL Supply Chain
- Kuehne + Nagel
- GXO Logistics
- CEVA Logistics
- DSV
- Rhenus Logistics
- Yusen Logistics
- XPO Logistics
- Segro Logistics
- UPS Supply Chain Solutions
- FedEx Logistics
- Expeditors
- Constellation Cold Logistics
- Magnavale
- Fowler Welch
- DFDS Logistics
- Palletforce
- Fullers Logistics
- Apex Logistics
- CDL Logistics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-commerce fulfilment space surge
- 4.2.2 Cold-chain growth for grocery and pharma
- 4.2.3 Automation and robotics efficiency gains
- 4.2.4 Government Freeport and industrial-park incentives
- 4.2.5 Re-/near-shoring of inventory post-Brexit
- 4.2.6 ESG-driven brown-field redevelopment
- 4.3 Market Restraints
- 4.3.1 Urban land scarcity and rent inflation
- 4.3.2 Warehouse-labour shortages and wage spikes
- 4.3.3 Grid-capacity limits for EV/automation
- 4.3.4 Planning-permission delays (NIMBY)
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Pricing Analysis-Warehouse Rents
- 4.8 Porter's Five Forces
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
- 4.9 Impact of COVID-19 and Geo-Political Events
5 Market Size & Growth Forecasts (Value)
- 5.1 By Warehouse Type (Value)
- 5.1.1 General Warehousing and Storage
- 5.1.2 Refrigerated Warehousing and Storage
- 5.2 By Ownership (Value)
- 5.2.1 Private Warehouses
- 5.2.2 Public Warehouses
- 5.3 By End-User Industry (Value)
- 5.3.1 E-commerce and Retail
- 5.3.2 Food and Beverage
- 5.3.3 Pharma and Healthcare
- 5.3.4 Automotive
- 5.3.5 Manufacturing and Engineering Goods
- 5.3.6 Others
- 5.4 By Region
- 5.4.1 England
- 5.4.2 Scotland
- 5.4.3 Wales
- 5.4.4 Northern Ireland
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 DHL Supply Chain
- 6.4.2 Kuehne + Nagel
- 6.4.3 GXO Logistics
- 6.4.4 CEVA Logistics
- 6.4.5 DSV
- 6.4.6 Rhenus Logistics
- 6.4.7 Yusen Logistics
- 6.4.8 XPO Logistics
- 6.4.9 Segro Logistics
- 6.4.10 UPS Supply Chain Solutions
- 6.4.11 FedEx Logistics
- 6.4.12 Expeditors
- 6.4.13 Constellation Cold Logistics
- 6.4.14 Magnavale
- 6.4.15 Fowler Welch
- 6.4.16 DFDS Logistics
- 6.4.17 Palletforce
- 6.4.18 Fullers Logistics
- 6.4.19 Apex Logistics
- 6.4.20 CDL Logistics
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

