PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116746

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116746
Expression Vectors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, expression vectors market size in 2026 is estimated at USD 442.19 million, growing from 2025 value of USD 420.41 million with 2031 projections showing USD 569.27 million, growing at 5.18% CAGR over 2026-2031.
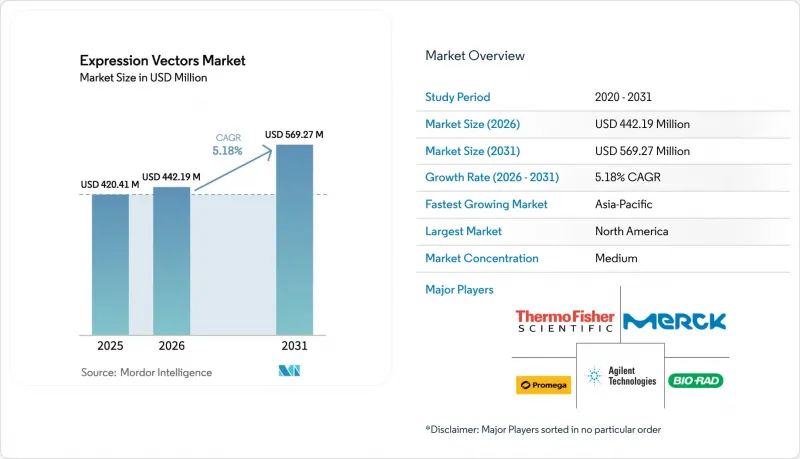
This report is Segmented by Host Type (Bacterial, Mammalian, Insect, Yeast, Others), Application (Therapeutic, Research, Enzyme Manufacturing), End-User (Pharmaceutical and Biotechnology Companies, CDMOs/CROs/CMOs, Academic & Research Institutes, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Expression Vectors Market Trends and Insights
Surge in Demand for Advanced Biologics & Cell-/Gene-Therapies
Gene-therapy approvals climbed from 8 in 2023 to 15 in 2024, each requiring customized, high-purity vectors. Clinical programs now specify vector designs compatible with perfusion bioreactors and single-use systems, tightening supplier selection. Autologous CAR-T pipelines intensify batch-specific vector demand, prompting companies such as Bluebird Bio and Oxford BioMedica to restructure in-house production schedules. CDMOs with redundant suites absorb overflow, but their capacity utilization peaks during regulatory surges. Developers perceive secure vector supply as a strategic differentiator and often lock multi-year contracts, reinforcing long-term revenue visibility across the Expression vectors market.
Growing Adoption of Mammalian & Insect Hosts for Complex Proteins
Biopharma firms pivot toward baculovirus expression vector systems (BEVS) for membrane proteins and glycoproteins that need authentic post-translational modifications . Regulatory guidance now evaluates glycosylation consistency alongside sequence identity, favoring eukaryotic hosts. Although mammalian cell production costs remain higher, demand for distinctive safety and efficacy profiles justifies premiums, particularly for first-in-class therapies. Suppliers respond by widening transfection-media portfolios and offering ready-to-transfect kits optimized for Chinese hamster ovary and Spodoptera frugiperda cells. The trend reallocates R&D spending from bacterial optimization toward scalable eukaryotic platforms, broadening revenue channels across the Expression vectors market.
High Cost & Complexity of GMP-Grade Vector Production
Clinical-grade plasmid DNA costs range between USD 50-200 per gram, four to ten times research-grade pricing. Capital expenses for ISO-classified cleanrooms, quality-management systems, and sterility testing inflate operating budgets. Small biotech firms often delay trials due to procurement bottlenecks, while academic centers rarely absorb full compliance costs. Although CDMOs mitigate scale constraints, tighter capacity during peak demand inflates spot prices and lengthens lead times. These dynamics dampen adoption rates in emerging markets and moderate overall expansion of the Expression vectors market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Contract Vector Manufacturing Capacity
- AI-Driven Codon Optimization & De-Novo Vector Design
- Stringent Viral-Vector Safety Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bacterial systems captured 51.72% of the Expression vectors market share in 2025, supported by cost-efficient fermentation and well-understood genetic toolkits. In contrast, Insect vectors record a robust 5.97% CAGR to 2031 as BEVS technology resolves folding and glycosylation constraints.
The Expression vectors market continues to migrate toward eukaryotic hosts, with mammalian platforms commanding premium pricing due to regulatory emphasis on protein quality. Yeast systems maintain relevance for certain enzymes, while plant and algal vectors explore non-pharma niches. As therapeutic pipelines tilt toward multi-subunit biologics, host-selection frameworks prioritize fidelity over cost, accelerating demand for sophisticated insect and mammalian solutions.
Complete Report Scope:
- By Host Type
- Bacterial Expression Vectors
- Mammalian Expression Vectors
- Insect Expression Vectors
- Yeast Expression Vectors
- Others
- By Application
- Therapeutic Applications
- Research Applications
- Enzyme Manufacturing
- By End-User
- Pharmaceutical and Biotechnology Companies
- CDMOs / CROs / CMOs
- Academic & Research Institutes
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America's 42.05% share reflects entrenched venture investment, streamlined FDA pathways, and integrated supply chains connecting discovery through commercialization. Canada's CAD 2.2 billion Advanced Biomanufacturing initiative furthers domestic vector capacity, and Mexico's near-shoring trend adds process-development demand.
Asia-Pacific is the fast-growing region at 6.15% CAGR. China authorised its first home-grown CAR-T therapy in 2024, spurring domestic CDMOs to boost vector output. Singapore's tax-incentive clusters attract global majors, and South Korea's K-Bio Belt builds dedicated biomanufacturing corridors. Japan reduces review timelines by 30%, enhancing deployment speeds for regenerative products.
Europe maintains a consolidated but innovative market, with Germany's EUR 500 million BioRegion program enhancing infrastructure. The United Kingdom speeds approvals post-Brexit, while France's Genopole adds vector suites. Southern European nations grow gradually, yet shared EMA guidelines permit seamless product movement, reinforcing pan-regional demand within the Expression vectors market.
- Thermo Fisher Scientific
- Merck
- Takara Bio
- Promega
- Agilent Technologies
- Bio-Rad Laboratories
- QIAGEN
- New England Biolabs
- Genscript
- OriGene Technologies
- System Biosciences
- Lonza Group
- Aldevron
- Cobra Biologics
- Sirion-Biotech
- Bluebird bio
- Catalent
- Addgene
- Oxford BioMedica
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in demand for advanced biologics & cell-/gene-therapies
- 4.2.2 Growing adoption of mammalian & insect hosts for complex proteins
- 4.2.3 Expansion of contract vector manufacturing capacity
- 4.2.4 AI-driven codon optimisation & de-novo vector design
- 4.2.5 Open-source vector repositories accelerating translation
- 4.2.6 mRNA-vaccine spill-over boosting plasmid-vector demand
- 4.3 Market Restraints
- 4.3.1 High cost & complexity of GMP-grade vector production
- 4.3.2 Stringent viral-vector safety regulations
- 4.3.3 Patent thickets around promoters/regulatory elements
- 4.3.4 Supply-chain fragility for critical raw materials
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Host Type
- 5.1.1 Bacterial Expression Vectors
- 5.1.2 Mammalian Expression Vectors
- 5.1.3 Insect Expression Vectors
- 5.1.4 Yeast Expression Vectors
- 5.1.5 Others
- 5.2 By Application
- 5.2.1 Therapeutic Applications
- 5.2.2 Research Applications
- 5.2.3 Enzyme Manufacturing
- 5.3 By End-User
- 5.3.1 Pharmaceutical and Biotechnology Companies
- 5.3.2 CDMOs / CROs / CMOs
- 5.3.3 Academic & Research Institutes
- 5.3.4 Others
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Thermo Fisher Scientific
- 6.3.2 Merck KGaA (Sigma-Aldrich)
- 6.3.3 Takara Bio
- 6.3.4 Promega Corporation
- 6.3.5 Agilent Technologies
- 6.3.6 Bio-Rad Laboratories
- 6.3.7 QIAGEN
- 6.3.8 New England Biolabs
- 6.3.9 GenScript
- 6.3.10 OriGene Technologies
- 6.3.11 System Biosciences
- 6.3.12 Lonza Group
- 6.3.13 Aldevron
- 6.3.14 Cobra Biologics
- 6.3.15 Sirion-Biotech
- 6.3.16 Bluebird bio
- 6.3.17 Catalent
- 6.3.18 Addgene
- 6.3.19 Oxford BioMedica
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

