PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118044

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118044
Cardiac Imaging Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the cardiac imaging software market size is expected to grow from USD 0.63 billion in 2025 to USD 0.69 billion in 2026 and is forecast to reach USD 1.06 billion by 2031 at 8.97% CAGR over 2026-2031.
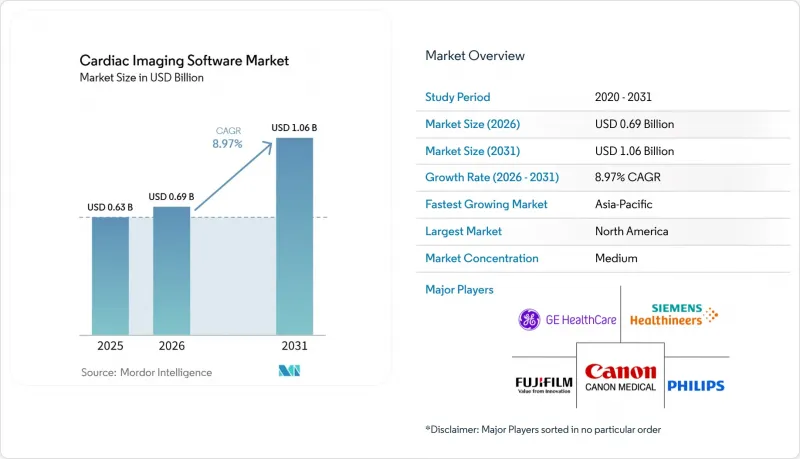
This report is Segmented by Modality (CT, CMR, Echo, Others), Application (CAD, Structural Heart, Others), End User (Hospitals, Ascs, Others), Deployment (On-Premises, Cloud/SaaS, Others), System Type (CVIS, PACS, AI Platforms), Component (Software, Services, HW Software), and Geography (North America, Europe, Asia-Pacific, MEA, South America). Forecasts in Value (USD).
Global Cardiac Imaging Software Market Trends and Insights
Rising Cardiovascular Disease Imaging Workloads
Cardiovascular disease continues to create sustained demand for timely imaging and clinical interpretation across care settings. This demand places greater pressure on providers to complete routine analysis and reporting without expanding specialist teams at the same pace. The cardiac imaging software market benefits when organizations use automation to handle measurements, workflow prioritization, and report preparation. CT and MR studies require substantial image review and post-processing, which supports demand for advanced visualization and quantification software. The cardiac imaging software market also benefits when providers replace fragmented tools with platforms that support several imaging pathways. Hospitals that delayed software upgrades may prioritize implementation as reading workloads and procedural imaging needs rise.
AI-Assisted Interpretation and Measurement Automation
AI-assisted tools are changing how cardiac imaging teams complete repetitive analysis tasks and organize clinical work. The FDA cleared 92 AI and machine learning-related cardiology submissions in 2025, compared with 62 in 2024. Plaque analysis, calcium scoring, and CT-derived fractional flow reserve were among the leading product categories in the 2025 clearance group. The 2026 CPT updates added Category I codes for CT-derived fractional flow reserve and CT perfusion, which widened the reimbursable measurement categories. Philips received FDA clearance for SmartHeart in 2026, and the software automates cardiac MR scan planning in under 30 seconds. These developments favor subscription models that allow customers to receive cleared updates over time rather than rely on fixed software versions.
High Integration And Implementation Costs
Full CVIS replacement programs can require 18 to 36 months for configuration, interfaces, and clinical validation before go-live. This duration can extend beyond an annual finance planning cycle and delay procurement decisions in the cardiac imaging software market. Community hospitals may find that enterprise platforms are difficult to justify against smaller study volumes. Migration from legacy systems also requires careful handling of echo loops, catheterization studies, and structured reports. Data migration risks can raise the scope and cost of implementation beyond the initial software purchase. Vendors that simplify interface development and conversion work can better address this barrier.
Other drivers and restraints analyzed in the detailed report include:
- Cloud-Based Multi-Site Cardiology Operations
- Expansion of Ambulatory And Distributed Cardiac Care
- Cybersecurity, Privacy, And Data-Sovereignty Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Echocardiography held 32.18% of revenue in 2025, giving it the largest position in the modality analysis. Its wide use across hospitals, ambulatory surgical centers, and outpatient clinics supports steady demand for cardiac imaging software. Leading echo platforms increasingly include AI-guided acquisition, automated left ventricular ejection fraction measurement, and strain quantification. These functions can improve the consistency of routine workflows and structured reports. Cardiac CT and cardiac MR are expanding the need for post-processing and quantitative analysis, while nuclear workflow tools face a more limited role in some indications. EchoNext received FDA clearance in 2025 to identify patients who may need echocardiography for structural heart disease from standard 12-lead ECG information.
Combined and multimodality imaging platforms are forecast to grow at a 15.27% CAGR through 2031. Structural heart disease, cardiomyopathy, and congenital conditions can require CT, MR, and echocardiography findings to be considered together. A unified reading environment can reduce the need to move between separate applications during review. It can also support multidisciplinary discussion by bringing anatomical, tissue, and functional data into a common workflow. Broader platform coverage can make enterprise contracts more valuable than a single-modality purchase.. Integration with AI post-processing will remain important as providers seek consistent data exchange and reporting.
Coronary artery disease applications accounted for 33.35% of revenue in 2025. This application includes CCTA post-processing, CT-derived fractional flow reserve, plaque quantification, and calcium scoring. CMS increased hospital reimbursement for CCTA to USD 357 in 2025 and established USD 950 reimbursement for AI plaque analysis. These changes improved the economic case for cardiac software that provides measurable clinical outputs. HeartFlow received FDA clearance for its next-generation Plaque Analysis algorithm in September 2025, and Cigna began coverage for the service in October 2025. This development supports a shift from one-time reporting toward ongoing risk assessment in the cardiac imaging software market.
Structural heart disease is forecast to grow at a 17.12% CAGR through 2031. Transcatheter aortic valve implantation, mitral valve repair, and left atrial appendage closure require detailed anatomical planning and intra-procedural imaging support. Philips received FDA clearance for EchoNavigator R5.0 with DeviceGuide in 2026 for AI-powered guidance during mitral valve repair. The approval extends software use into the catheterization laboratory as a procedural support tool. Heart failure, arrhythmia, valvular disease, congenital disease, pulmonary hypertension, and cardiomyopathy also require specialized workflows. Preventive screening is widening as software identifies cardiovascular findings in CT studies completed for other clinical reasons
Complete Report Scope:
- By Modality
- Cardiac Computed Tomography
- Coronary CT Angiography
- Coronary Artery Calcium Scoring
- CT-Derived Fractional Flow Reserve
- Plaque Quantification and Characterization
- Others
- Cardiac Magnetic Resonance Imaging
- Ventricular Function Analysis
- T1 and T2 Mapping
- Tissue Characterization
- Flow and Perfusion Analysis
- Others
- Echocardiography
- Transthoracic Echocardiography
- Transesophageal Echocardiography
- Three-Dimensional Echocardiography
- Strain and Deformation Imaging
- AI-Guided Image Acquisition
- Others
- Nuclear Cardiology
- SPECT
- PET
- Myocardial Perfusion Analysis
- Others
- X-Ray and Fluoroscopy
- Cath Lab Imaging
- Angiography and Fluoroscopy
- Others
- Combined and Multimodality Imaging
- Cardiac Computed Tomography
- By Application
- Coronary Artery Disease
- Structural Heart Disease
- Heart Failure
- Arrhythmia and Electrophysiology
- Valvular Heart Disease
- Congenital Heart Disease
- Pulmonary Hypertension
- Cardiomyopathy
- Preventive and Opportunistic Cardiac Screening
- Image-Guided Treatment Planning
- Procedure Monitoring and Post-Treatment Assessment
- Others
- By End User
- Hospitals
- Academic Medical Centers
- Community Hospitals
- Integrated Delivery Networks
- Diagnostic Imaging Centers
- Cardiovascular Clinics
- Ambulatory Surgical Centers
- Research and Pharmaceutical Organizations
- Others
- Hospitals
- By Deployment
- On-Premises
- Cloud-Based and Software as a Service
- Web-Based
- Hybrid and Edge Deployment
- Others
- By System Type
- Cardiovascular Information Systems
- Cardiology Picture Archiving and Communication Systems
- Integrated Cardiovascular Information System and Cardiology PACS Platforms
- Advanced Visualization and Post-Processing Platforms
- Artificial Intelligence Analysis Platforms
- Structured Reporting and Workflow Platforms
- Others
- By Component
- Software
- Services
- Implementation and Integration Services
- Training and Support Services
- Managed and Professional Services
- Hardware-Enabled Software Solutions
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 42.17% of global revenue in 2025, which gave the region the largest position in the cardiac imaging software market. CMS reimbursement pathways for software-derived measurements and broad CVIS use at integrated delivery networks support demand. In 2025, CMS set CCTA hospital reimbursement at USD 357, CT-derived fractional flow reserve reimbursement at USD 1,017, and AI coronary plaque analysis reimbursement at USD 950. The United States leads regional spending, while Canada is progressing through CVIS consolidation at provincial health systems. Mexico's private hospital sector provides another adoption route outside public reimbursement programs.
Europe has substantial demand, but adoption varies by country and by the ability of vendors to meet GDPR and MDR requirements. Germany, the United Kingdom, France, Italy, and Spain anchor regional demand through university hospitals and digital imaging programs. Goethe University Frankfurt is developing the LIDIA-Hessen project to automate cardiac MR workflows from acquisition to structured reporting. Spain and Italy are pursuing PACS and CVIS upgrades through digital health programs. Scandinavian systems can support cloud CVIS adoption because centralized governance can simplify implementation decisions. South America remains at an earlier stage, with Brazil and Argentina building digital imaging capability in private hospital and diagnostic networks.
Asia-Pacific is forecast to grow at a 13.34% CAGR through 2031, the fastest regional rate in the cardiac imaging software market. Aging populations, cardiovascular disease prevalence, and public investment in health AI support this expansion. Japan, China, South Korea, and India are the central growth areas. ElPixel partnered with Clairvo Technologies in June 2025 to commercialize the CoronaryDoc cardiac CT analysis platform in Japan. The Middle East and Africa are developing from a smaller base, with GCC health infrastructure investment and private hospital demand in South Africa supporting PACS and CVIS deployment.
- Agfa-Gevaert
- Artrya Limited
- Canon
- Circle Cardiovascular Imaging Inc.
- Cleerly, Inc.
- DESKi
- DiA Imaging Analysis Ltd.
- Digisonics, Inc.
- Esaote S.p.A.
- FUJIFILM
- GE HealthCare Technologies Inc.
- HeartFlow, Inc.
- HeartLung Corporation
- INFINITT Healthcare Co., Ltd.
- Intelerad Medical Systems
- Koninklijke Philips
- Medis Medical Imaging Systems
- Merative
- NeoSoft LLC
- Pie Medical Imaging
- Ram Soft
- ScImage, Inc.
- Sectra
- Shimadzu
- Siemens Healthineers
- Tempus AI, Inc.
- TomTec Imaging Systems GmbH
- Ventripoint Diagnostics Ltd.
- Viz.ai
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Cardiovascular Disease Imaging Workloads
- 4.2.2 AI-Assisted Interpretation and Measurement Automation
- 4.2.3 Cloud-Based Multi-Site Cardiology Operations
- 4.2.4 Expansion of Ambulatory and Distributed Cardiac Care
- 4.2.5 Opportunistic Cardiac Findings From Existing CT Scans
- 4.2.6 Reimbursement Expansion for Software-Derived Cardiac Measurements
- 4.3 Market Restraints
- 4.3.1 High Integration and Implementation Costs
- 4.3.2 Cybersecurity, Privacy and Data-Sovereignty Requirements
- 4.3.3 Shortage of Cardiology Informatics Specialists
- 4.3.4 Evidence, Validation and Reimbursement Uncertainty for AI Software
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Modality
- 5.1.1 Cardiac Computed Tomography
- 5.1.1.1 Coronary CT Angiography
- 5.1.1.2 Coronary Artery Calcium Scoring
- 5.1.1.3 CT-Derived Fractional Flow Reserve
- 5.1.1.4 Plaque Quantification and Characterization
- 5.1.1.5 Others
- 5.1.2 Cardiac Magnetic Resonance Imaging
- 5.1.2.1 Ventricular Function Analysis
- 5.1.2.2 T1 and T2 Mapping
- 5.1.2.3 Tissue Characterization
- 5.1.2.4 Flow and Perfusion Analysis
- 5.1.2.5 Others
- 5.1.3 Echocardiography
- 5.1.3.1 Transthoracic Echocardiography
- 5.1.3.2 Transesophageal Echocardiography
- 5.1.3.3 Three-Dimensional Echocardiography
- 5.1.3.4 Strain and Deformation Imaging
- 5.1.3.5 AI-Guided Image Acquisition
- 5.1.3.6 Others
- 5.1.4 Nuclear Cardiology
- 5.1.4.1 SPECT
- 5.1.4.2 PET
- 5.1.4.3 Myocardial Perfusion Analysis
- 5.1.4.4 Others
- 5.1.5 X-Ray and Fluoroscopy
- 5.1.5.1 Cath Lab Imaging
- 5.1.5.2 Angiography and Fluoroscopy
- 5.1.5.3 Others
- 5.1.6 Combined and Multimodality Imaging
- 5.1.1 Cardiac Computed Tomography
- 5.2 By Application
- 5.2.1 Coronary Artery Disease
- 5.2.2 Structural Heart Disease
- 5.2.3 Heart Failure
- 5.2.4 Arrhythmia and Electrophysiology
- 5.2.5 Valvular Heart Disease
- 5.2.6 Congenital Heart Disease
- 5.2.7 Pulmonary Hypertension
- 5.2.8 Cardiomyopathy
- 5.2.9 Preventive and Opportunistic Cardiac Screening
- 5.2.10 Image-Guided Treatment Planning
- 5.2.11 Procedure Monitoring and Post-Treatment Assessment
- 5.2.12 Others
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.1.1 Academic Medical Centers
- 5.3.1.2 Community Hospitals
- 5.3.1.3 Integrated Delivery Networks
- 5.3.2 Diagnostic Imaging Centers
- 5.3.3 Cardiovascular Clinics
- 5.3.4 Ambulatory Surgical Centers
- 5.3.5 Research and Pharmaceutical Organizations
- 5.3.6 Others
- 5.3.1 Hospitals
- 5.4 By Deployment
- 5.4.1 On-Premises
- 5.4.2 Cloud-Based and Software as a Service
- 5.4.3 Web-Based
- 5.4.4 Hybrid and Edge Deployment
- 5.4.5 Others
- 5.5 By System Type
- 5.5.1 Cardiovascular Information Systems
- 5.5.2 Cardiology Picture Archiving and Communication Systems
- 5.5.3 Integrated Cardiovascular Information System and Cardiology PACS Platforms
- 5.5.4 Advanced Visualization and Post-Processing Platforms
- 5.5.5 Artificial Intelligence Analysis Platforms
- 5.5.6 Structured Reporting and Workflow Platforms
- 5.5.7 Others
- 5.6 By Component
- 5.6.1 Software
- 5.6.2 Services
- 5.6.2.1 Implementation and Integration Services
- 5.6.2.2 Training and Support Services
- 5.6.2.3 Managed and Professional Services
- 5.6.3 Hardware-Enabled Software Solutions
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 Australia
- 5.7.3.5 South Korea
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East and Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East and Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Agfa-Gevaert NV
- 6.3.2 Artrya Limited
- 6.3.3 Canon Medical Systems Corporation
- 6.3.4 Circle Cardiovascular Imaging Inc.
- 6.3.5 Cleerly, Inc.
- 6.3.6 DESKi
- 6.3.7 DiA Imaging Analysis Ltd.
- 6.3.8 Digisonics, Inc.
- 6.3.9 Esaote S.p.A.
- 6.3.10 FUJIFILM Holdings Corporation
- 6.3.11 GE HealthCare Technologies Inc.
- 6.3.12 HeartFlow, Inc.
- 6.3.13 HeartLung Corporation
- 6.3.14 INFINITT Healthcare Co., Ltd.
- 6.3.15 Intelerad Medical Systems Incorporated
- 6.3.16 Koninklijke Philips N.V.
- 6.3.17 Medis Medical Imaging Systems B.V.
- 6.3.18 Merative
- 6.3.19 NeoSoft LLC
- 6.3.20 Pie Medical Imaging B.V.
- 6.3.21 RamSoft, Inc.
- 6.3.22 ScImage, Inc.
- 6.3.23 Sectra AB
- 6.3.24 Shimadzu Corporation
- 6.3.25 Siemens Healthineers AG
- 6.3.26 Tempus AI, Inc.
- 6.3.27 TomTec Imaging Systems GmbH
- 6.3.28 Ventripoint Diagnostics Ltd.
- 6.3.29 Viz.ai
7 Market Opportunities & Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

