PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121439

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121439
Medical Imaging Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the medical imaging software market size is projected to expand from USD 8.74 billion in 2025 and USD 9.45 billion in 2026 to USD 13.90 billion by 2031, registering a CAGR of 8.02% between 2026 to 2031.
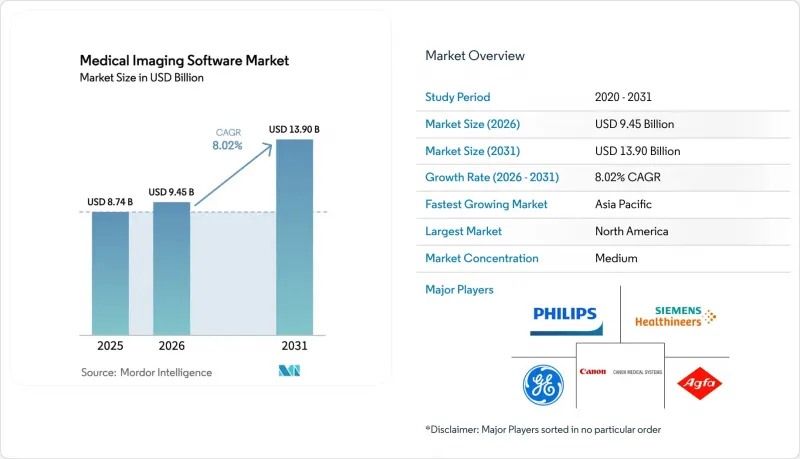
This report is Segmented by Imaging Type (2D, 3D, and 4D), Modality (CT, MRI, X-Ray, Ultrasound, and More), Application (Orthopedic, Oncology, Cardiology, Neurology, and More), Deployment Model (On-Premise, Cloud-Based, and Hybrid), End User (Hospitals, Diagnostic Imaging Centers, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Medical Imaging Software Market Trends and Insights
Growing Adoption of AI-Powered Diagnostic Tools
Regulators have moved from cautious gatekeepers to active enablers: the FDA cleared 171 AI-enabled devices in 2024, nearly doubling 2023 activity, and over half of them target radiology. Predicate-based 510(k) filings reduced review cycles from 18 months to under six, allowing vendors to achieve quicker revenue realization. Qure.ai's qER suite demonstrates its commercial impact, flagging intracranial bleeds within 90 seconds and enabling rural emergency teams to bypass local radiologist queues. Hospitals are incorporating such algorithms into PACS worklists, so that critical studies surface first, turning AI usage into a per-scan fee generator rather than a fixed license sale. Consolidation is intensifying, as Tempus has absorbed Arterys to fuse genomics with imaging biomarkers and capture precision-oncology budgets. As payers issue separate CPT codes for AI-assisted reads, the revenue flywheel tightens further around algorithm performance and breadth.
Increasing Chronic Disease Burden Requiring Advanced Imaging
An aging world pushes imaging volumes beyond radiologist capacity. Adults aged 65 and above will comprise 21.6% of the U.S. population by 2040 and will consume over three times the number of imaging studies as younger cohorts. The United Kingdom saw CT and MRI usage increase by 12% annually from 2019 to 2024, driven by expanded cancer screening mandates. Software now automates repetitive quantification tasks, such as those used by Siemens Healthineers' syngo.Via Frontier slashed cardiac chamber segmentation from 20 minutes to 90 seconds, freeing physicians for interpretive tasks. Oncology underscores the throughput imperative, immunotherapy regimens require serial scans, multiplying image load per patient and enlarging the addressable software pool. By automating measurements, vendors translate demographic pressure into sustained demand, thereby reinforcing the market's trajectory for medical imaging software.
High Software Licensing and Maintenance Costs
Enterprise PACS licenses range from USD 300,000 to USD 1.5 million, with annual support fees near 20% of the purchase price, straining mid-sized centers operating on single-digit margins. Cloud subscriptions only equalize outlays after seven years of steady volume growth, according to HFMA modeling. Migration away from an incumbent PACS can cost another USD 200,000-500,000 in interface rebuilds and staff retraining, locking buyers into long depreciation cycles. Price-sensitive Asian markets respond by adopting open-source stacks like Orthanc, which erase license fees but demand in-house expertise, a trade favored by large public hospitals but beyond reach for smaller private clinics. The resulting sticker shock slows refresh decisions and clips near-term medical imaging software market expansion.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Shift Toward 3D and 4D Visualization Workflows
- Expansion of Cloud-Enabled Enterprise Imaging Platforms
- Shortage of Trained Imaging-Informatics Professionals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
3D visualization commanded 52.84% of 2025 revenue, underpinning pre-operative planning across orthopedic, neuro, and maxillofacial specialties, while 4D workflows are set to grow at a 9.11% CAGR by capturing temporal cardiac and fetal motion. This evolution scales dataset weights ten-fold, testing on-premise storage but slotting neatly into cloud archives that tier cold data to low-cost object storage after 90 days. Clinical evidence strengthens the shift: respiratory-gated 4D CT narrows tumor treatment margins and reduces collateral tissue damage. Although 2D remains vital for high-throughput screenings, most vendors now ship universal viewers that read 2D, 3D, and 4D files through a single interface, limiting willingness to pay for stand-alone 2D licenses. Overall, robust upgrade incentives keep the medical imaging software market accelerating inside visualization suites.
The toolkit transition increases bandwidth requirements and pushes hospitals toward edge caching or direct-to-cloud ingestion, modernizing network fabrics as part of platform overhauls. FDA guidance now requires separate clearances when 4D functions introduce fresh clinical claims, slowing startup roadmaps but creating defensible moats for incumbents with regulatory capital. As subscription pricing spreads, providers match costs with volumes, making 4D modules less risky to trial. That flexibility feeds long-run adoption and reinforces the medical imaging software industry's shift to real-time imaging.
Computed tomography software held 31.85% of 2025 spend thanks to CT's ubiquity in trauma and emergency pathways, yet PET and SPECT platforms are advancing at an 8.43% CAGR through 2031. Oncology departments want quantitative biomarkers to monitor immunotherapy and adjust dosing without repeat biopsies. SubtlePET, now part of Bracco Imaging, halves patient radiation by enabling low-dose protocols while preserving diagnostic utility, letting centers scan more patients from the same radiotracer batch. MRI developments focus on synthetic reconstruction that trims exam times by more than half, sustaining upgrade waves among high-volume outpatient centers.
Ultrasound and X-ray modules remain commodity offerings unless layered with triage AI that flags life-threatening findings within minutes. Sectra's modality-agnostic viewer bundles CT, MRI, and ultrasound into one license, curbing IT complexity and supporting cross-disciplinary collaboration. Modalities once walled off by proprietary workstations are collapsing into holistic platforms, redefining competitive battlegrounds across the medical imaging software market.
Complete Report Scope:
- By Imaging Type
- 2D Imaging
- 3D Imaging
- 4D Imaging
- By Modality
- Computed Tomography
- Magnetic Resonance Imaging
- X-Ray
- Ultrasound
- PET and SPECT
- Other Modalities
- By Application
- Orthopedic
- Oncology
- Cardiology
- Neurology
- Dental
- Obstetrics and Gynecology
- Mammography
- Urology and Nephrology
- By Deployment Model
- On-Premise
- Cloud-Based
- Hybrid
- By End User
- Hospitals
- Diagnostic Imaging Centers
- Ambulatory Surgical Centers
- Research and Academic Institutes
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America preserved 35.62% revenue share in 2025, powered by Medicare CPT codes that reimburse AI-assisted reads and elevate software to a billable line item. FDA clearance velocity converts regulatory friction into adoption fuel, and integrated delivery networks invest in proprietary platforms to lock in cost savings. Canada's provinces enforce HL7 FHIR interfaces, steering buyers toward vendors with mature interoperability toolkits, while Mexico's public hospitals direct limited budgets to modality hardware first.
Asia-Pacific is the pace car, growing at an 8.67% CAGR. China's Healthy China 2030 project earmarked CNY 50 billion (USD 7 billion) in 2024 for AI-ready imaging networks, giving domestic suppliers like United Imaging a protected runway. India's Ayushman Bharat Digital Mission connects 150,000 facilities to a national exchange, and new telemedicine rules permit cross-state radiology reads, catalyzing a unified teleradiology market. Japan's super-aged demographic makes real-time triage AI indispensable as emergency departments strain under stroke caseloads. South Korea issued the region's first reimbursement code for AI lung-nodule detection, signalling payer willingness to recognize software value.
Europe grapples with GDPR and the forthcoming AI Act. Vendors must evidence demographic fairness and avoid cross-border data transfers, so federated learning is baseline architecture rather than an innovation. The U.K.'s NHS saw CT and MRI volumes climb 12% annually through 2024, stretching consultant capacity. Germany demands disclosure of training-dataset demographics, delaying market entry for opaque models. France standardized 200 public hospitals on Sectra's enterprise PACS, proving that national-scale rollouts can proceed once procurement hurdles clear.
South America contends with currency volatility such as Brazil and Argentina lean on open-source PACS to dodge exchange swings, limiting near-term commercial opportunity. Middle Eastern programs, notably Saudi Arabia's Vision 2030, allocate USD 2.5 billion to health IT, positioning cloud PACS as the backbone of tertiary expansion. In Africa, South African private networks and Nigerian teaching hospitals pioneer teleradiology links that bridge urban-rural care gaps but remain early-stage contributors to overall medical imaging software market revenue.
- GE HealthCare Technologies, Inc.
- Siemens Healthineers AG
- Koninklijke Philips N.V.
- Canon Medical Systems Corporation
- Agfa-Gevaert N.V.
- Fujifilm Holdings Corporation
- Carestream Health, Inc.
- Sectra AB
- Novarad Corporation
- MIM Software Inc.
- Cerner Health Services, Inc.
- Change Healthcare LLC
- IBM Corporation (Watson Health was a division)
- Arterys, Inc.
- Circle Cardiovascular Imaging Inc.
- INFINITT Healthcare Co., Ltd.
- Visage Imaging GmbH
- Mach7 Technologies Ltd.
- TeraRecon, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Adoption of AI-Powered Diagnostic Tools
- 4.2.2 Increasing Chronic Disease Burden Requiring Advanced Imaging
- 4.2.3 Rapid Shift Toward 3D and 4D Visualization Workflows
- 4.2.4 Expansion of Cloud-Enabled Enterprise Imaging Platforms
- 4.2.5 Emergence of Federated Learning to Unlock Multi-Institutional Datasets
- 4.2.6 Increasing Use of Synthetic Data for Regulatory-Grade Validation
- 4.3 Market Restraints
- 4.3.1 High Software Licensing and Maintenance Costs
- 4.3.2 Shortage of Trained Imaging-Informatics Professionals
- 4.3.3 Cyber-Security Threats Targeting PACS and VNA Ecosystems
- 4.3.4 Algorithmic Bias Concerns Hindering AI Approvals
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Imaging Type
- 5.1.1 2D Imaging
- 5.1.2 3D Imaging
- 5.1.3 4D Imaging
- 5.2 By Modality
- 5.2.1 Computed Tomography
- 5.2.2 Magnetic Resonance Imaging
- 5.2.3 X-Ray
- 5.2.4 Ultrasound
- 5.2.5 PET and SPECT
- 5.2.6 Other Modalities
- 5.3 By Application
- 5.3.1 Orthopedic
- 5.3.2 Oncology
- 5.3.3 Cardiology
- 5.3.4 Neurology
- 5.3.5 Dental
- 5.3.6 Obstetrics and Gynecology
- 5.3.7 Mammography
- 5.3.8 Urology and Nephrology
- 5.4 By Deployment Model
- 5.4.1 On-Premise
- 5.4.2 Cloud-Based
- 5.4.3 Hybrid
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Diagnostic Imaging Centers
- 5.5.3 Ambulatory Surgical Centers
- 5.5.4 Research and Academic Institutes
- 5.5.5 Other End Users
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia and New Zealand
- 5.6.4.6 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 GE HealthCare Technologies, Inc.
- 6.4.2 Siemens Healthineers AG
- 6.4.3 Koninklijke Philips N.V.
- 6.4.4 Canon Medical Systems Corporation
- 6.4.5 Agfa-Gevaert N.V.
- 6.4.6 Fujifilm Holdings Corporation
- 6.4.7 Carestream Health, Inc.
- 6.4.8 Sectra AB
- 6.4.9 Novarad Corporation
- 6.4.10 MIM Software Inc.
- 6.4.11 Cerner Health Services, Inc.
- 6.4.12 Change Healthcare LLC
- 6.4.13 IBM Corporation (Watson Health was a division)
- 6.4.14 Arterys, Inc.
- 6.4.15 Circle Cardiovascular Imaging Inc.
- 6.4.16 INFINITT Healthcare Co., Ltd.
- 6.4.17 Visage Imaging GmbH
- 6.4.18 Mach7 Technologies Ltd.
- 6.4.19 TeraRecon, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

