PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119274

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119274
Prenatal Diagnostic Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the prenatal diagnostic software market size is expected to grow from USD 241.06 million in 2025 to USD 276.65 million in 2026 and is forecast to reach USD 511.5 million by 2031 at 13.08% CAGR over 2026-2031.
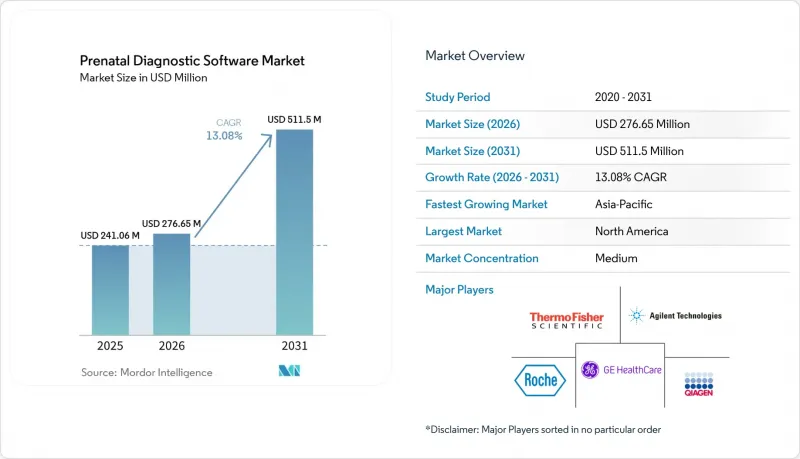
This report is Segmented by Product Type (Genetic Analysis and More), Technology (NGS Bioinformatics and More), Application (Chromosomal Abnormality Screening and More), Deployment (Cloud, and More), Workflow (Sample Accessioning, and More), End User (Hospitals and Health Systems and More), and Geography (North America and More).
Global Prenatal Diagnostic Software Market Trends and Insights
Broader Adoption of Non-Invasive Prenatal Testing
The prenatal diagnostic software market benefits when non-invasive prenatal testing becomes a routine option rather than a specialist test. Guideline support and payer decisions have raised uptake in several developed health systems, increasing the number of test results that laboratories must process. Japan reported that women aged 35 years and older accounted for 30.4% of births in 2023, compared with 14% in 2003. This demographic shift increases demand for screening and creates a larger base of eligible patients. Per-sample software licensing can give laboratories recurring revenue as volumes rise. As testing reaches more average-risk pregnancies, the ability to manage high volumes efficiently becomes more important than serving only specialist high-risk cases.
Expansion of AI-Assisted Prenatal Ultrasound Interpretation
AI-assisted ultrasound is addressing variation in how fetal images are captured and interpreted across care settings. A studyof AI methods for fetal ultrasound reported a pooled sensitivity of 0.84 and a specificity of 0.87 for intrauterine growth restriction detection. FetalCLIP was trained on 210,035 paired fetal ultrasound images and outperformed the tested baselines for gestational age estimation, congenital heart defect detection, and fetal structure segmentation. These tools can support less specialized obstetric settings where experienced maternal-fetal medicine staff are limited. The prenatal diagnostic software market can therefore reach clinics and community settings that previously relied on referrals for complex interpretation. Regulatory clearances and clinical validation remain central to adoption because providers need evidence that the tool can be safely incorporated into care.
Regulatory Classification and Clinical-Validation Complexity
Regulatory requirements can slow the introduction of prenatal software, especially for smaller developers. Under EU IVDR Regulation 2017/746, much prenatal testing software falls within Class C or D requirements that require notified body assessment. Legacy prenatal IVD manufacturers face final compliance deadlines of December 31, 2027 for Class III devices and December 31, 2028 for Class IIb devices. Quality management, laboratory accreditation, clinical validation, and post-market monitoring add further cost and time. BrightHeart received FDA approval for a predetermined change control plan in May 2025, which allows certain future model updates without separate submissions. These obligations favor well-funded suppliers and can limit the number of smaller vendors able to compete across regions.
Other drivers and restraints analyzed in the detailed report include:
- Integration of Prenatal Diagnostics With EHR and Laboratory Workflows
- Rising Demand for Early Detection of Chromosomal and Genetic Disorders
- Privacy, Cybersecurity, and Cross-Border Genomic-Data Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Integrated prenatal diagnostic platforms held 28.4% of the prenatal diagnostic software market share in 2025. Health systems use these platforms to bring sequencing intake, variant calling, risk scoring, and clinical reporting into a single environment. Integrated systems can make recurring enterprise licensing more predictable for suppliers. They also create switching costs once validated pipelines and audit trails become part of laboratory operations. Clinical reporting and decision support are increasingly delivered as modules within broader platforms. Workflow and care coordination functions follow the same pattern. This reduces the role of standalone point solutions in larger laboratory accounts. The prenatal diagnostic software market is consequently rewarding suppliers that can support the whole testing and reporting process.
Prenatal ultrasound analysis software is the fastest-growing product type, with a forecast CAGR of 13.8% through 2031. AI tools are moving from specialist research settings into routine obstetric practice as evidence and regulatory approvals accumulate. FetalCLIP illustrates this direction through a model built on paired fetal ultrasound images for several imaging tasks. Laboratory information management software remains necessary for sample tracking, quality control, and audit records. Prenatal-specific modules can include cfDNA quality checks and chain-of-custody functions. Genetic analysis software has a different role because it converts raw sequencing data into clinically useful variant calls. Basic chromosomal pipelines face more standardization, while single-gene workflows can retain higher value because of their greater analytical complexity.
NGS bioinformatics held 24.9% of revenue in 2025, making it the largest technology category. It provides the computational foundation for cfDNA-based non-invasive prenatal testing at scale. The growing range of sequenced panels is increasing both workload and clinical complexity. Single-gene disorders, copy-number variants, and multi-omics features require more advanced analysis than standard aneuploidy testing. The prenatal diagnostic software market relies on these pipelines to turn sequencing output into validated clinical information. Laboratories also need traceable versions and quality controls for their workflows. This makes the technology important to both routine volume testing and expanded clinical panels. Its role remains central as diagnostic scope broadens.
AI and machine learning are the fastest-growing technology categories, with a forecast CAGR of 13.6% through 2031. Its main uses include computer vision for structural anomaly detection and risk models that combine genomic, biometric, and maternal information. Research on AI-supported ultrasound has shown strong performance for growth restriction detection in controlled study settings. Rule-based clinical decision support still provides the guideline structure that regulators and payers expect. Computer vision can complement those systems in tasks that depend on image pattern recognition. Microarray and cytogenetic analysis software remains relevant for confirmatory testing and structural rearrangements. Multi-omics analytics is still developing, although it may become important for platforms that combine genomic, transcriptomic, and epigenomic data.
Complete Report Scope:
- Market Size and Growth Forecasts, Value
- Segmentation by Product Type
- Prenatal Genetic Analysis Software
- Prenatal Ultrasound Analysis Software
- Laboratory Information Management Software
- Clinical Reporting and Decision Support Software
- Workflow and Care Coordination Software
- Integrated Prenatal Diagnostic Platforms
- Segmentation by Technology
- NGS Bioinformatics
- cfDNA Analysis
- Microarray and Cytogenetic Analysis
- AI and Machine Learning
- Computer Vision Ultrasound Analytics
- Rule-Based Clinical Decision Support
- Multi-Omics Analytics
- Segmentation by Application
- Chromosomal Abnormality Screening
- Genetic Disorder Screening
- Fetal Structural Anomaly Detection
- Maternal-Fetal Risk Assessment
- Pregnancy Monitoring and Dating
- Workflow and Clinical Management
- Carrier Screening
- Segmentation by Deployment
- Cloud-Based
- On-Premises
- Hybrid
- Edge/Offline-Enabled
- Segmentation by Workflow
- Sample Accessioning
- Laboratory Analysis
- Bioinformatics Interpretation
- Risk Assessment and Decision Support
- Reporting and Genetic Counselling
- Segmentation by End User
- Hospitals and Health Systems
- Diagnostic Laboratories
- Maternal-Fetal Medicine Centers
- Obstetrics and Gynecology Clinics
- Fertility and Reproductive Medicine Centers
- Academic and Research Institutions
- Public Health Programs
- Segmentation by Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 40.11% of global revenue in 2025, representing the largest regional prenatal diagnostic software market share. High NIPT use, CLIA-certified reference laboratories, and a flow of prenatal AI clearances support regional demand. Large laboratory networks also generate datasets used to develop and validate AI models. BrightHeart's predetermined change control plan approval in May 2025 gives an example of a U.S. pathway for defined post-clearance model updates.
Europe is the second-largest regional segment and is changing as IVDR obligations reshape supplier requirements. Class C and D prenatal IVD software requires a notified body assessment under the EU framework. Germany, France, and the United Kingdom have demand from national screening programs, private laboratories, and public hospitals. Italy and Spain move more slowly because procurement is divided across regional health authorities.
Asia-Pacific is the fastest-growing region, with a forecast CAGR of 14.1% through 2031. China is a key source of momentum through domestic approvals for prenatal AI devices and cost-competitive sequencing infrastructure. Kaili Medical received China's first approval for an AI prenatal ultrasound device in March 2025. Hangzhou SciDiagnostics received a Class III registration for AI chromosome karyotype analysis software in May 2026, with analysis time reported to fall from 34.42 minutes to 11.19 minutes. In Japan, women aged 35 years and older accounted for 30.4% of live births in 2023, while invasive amniocentesis fell from 16,454 cases in 2014 to 5,620 in 2023. India, South Korea, and Australia have support from private healthcare expansion, regulated IVD demand, and private insurance coverage.
List of Companies Covered in this Report:
- Illumina
- Natera, Inc.
- Roche
- Thermo Fisher Scientific
- LabCorp
- Quest Diagnostics
- PerkinElmer
- Agilent Technologies
- BGI Genomics Co., Ltd.
- Eurofins
- Yourgene Health
- CENTOGENE N.V.
- Myriad Genetics
- The Cooper Companies
- GE HealthCare Technologies Inc.
- Koninklijke Philips
- Bio-Rad Laboratories
- Hologic
- Revvity, Inc.
- QIAGEN
- Sonio SAS
- Ultrasound AI
- Delft Imaging
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Broader Adoption of Non-Invasive Prenatal Testing
- 4.2.2 Integration of Prenatal Diagnostics With EHR and Laboratory Workflows
- 4.2.3 Expansion of AI-Assisted Prenatal Ultrasound Interpretation
- 4.2.4 Rising Demand for Early Detection of Chromosomal and Genetic Disorders
- 4.2.5 Increasing Need for Remote and Decentralized Maternal-Fetal Screening
- 4.2.6 Fetal-Fraction Optimization and Repeat-Test Reduction
- 4.3 Market Restraints
- 4.3.1 Regulatory Classification and Clinical-Validation Complexity
- 4.3.2 Privacy, Cybersecurity and Cross-Border Genomic-Data Requirements
- 4.3.3 Reimbursement Variation and Unequal Access to Advanced Screening
- 4.3.4 Clinical Interpretation Risks From False-Positive and Incidental Findings
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.7.6 Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 Market Size and Growth Forecasts, Value
- 5.2 Segmentation by Product Type
- 5.2.1 Prenatal Genetic Analysis Software
- 5.2.2 Prenatal Ultrasound Analysis Software
- 5.2.3 Laboratory Information Management Software
- 5.2.4 Clinical Reporting and Decision Support Software
- 5.2.5 Workflow and Care Coordination Software
- 5.2.6 Integrated Prenatal Diagnostic Platforms
- 5.3 Segmentation by Technology
- 5.3.1 NGS Bioinformatics
- 5.3.2 cfDNA Analysis
- 5.3.3 Microarray and Cytogenetic Analysis
- 5.3.4 AI and Machine Learning
- 5.3.5 Computer Vision Ultrasound Analytics
- 5.3.6 Rule-Based Clinical Decision Support
- 5.3.7 Multi-Omics Analytics
- 5.4 Segmentation by Application
- 5.4.1 Chromosomal Abnormality Screening
- 5.4.2 Genetic Disorder Screening
- 5.4.3 Fetal Structural Anomaly Detection
- 5.4.4 Maternal-Fetal Risk Assessment
- 5.4.5 Pregnancy Monitoring and Dating
- 5.4.6 Workflow and Clinical Management
- 5.4.7 Carrier Screening
- 5.5 Segmentation by Deployment
- 5.5.1 Cloud-Based
- 5.5.2 On-Premises
- 5.5.3 Hybrid
- 5.5.4 Edge/Offline-Enabled
- 5.6 Segmentation by Workflow
- 5.6.1 Sample Accessioning
- 5.6.2 Laboratory Analysis
- 5.6.3 Bioinformatics Interpretation
- 5.6.4 Risk Assessment and Decision Support
- 5.6.5 Reporting and Genetic Counselling
- 5.7 Segmentation by End User
- 5.7.1 Hospitals and Health Systems
- 5.7.2 Diagnostic Laboratories
- 5.7.3 Maternal-Fetal Medicine Centers
- 5.7.4 Obstetrics and Gynecology Clinics
- 5.7.5 Fertility and Reproductive Medicine Centers
- 5.7.6 Academic and Research Institutions
- 5.7.7 Public Health Programs
- 5.8 Segmentation by Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Mexico
- 5.8.2 Europe
- 5.8.2.1 Germany
- 5.8.2.2 United Kingdom
- 5.8.2.3 France
- 5.8.2.4 Italy
- 5.8.2.5 Spain
- 5.8.2.6 Rest of Europe
- 5.8.3 Asia-Pacific
- 5.8.3.1 China
- 5.8.3.2 Japan
- 5.8.3.3 India
- 5.8.3.4 South Korea
- 5.8.3.5 Australia
- 5.8.3.6 Rest of Asia-Pacific
- 5.8.4 Middle East and Africa
- 5.8.4.1 GCC
- 5.8.4.2 South Africa
- 5.8.4.3 Rest of Middle East and Africa
- 5.8.5 South America
- 5.8.5.1 Brazil
- 5.8.5.2 Argentina
- 5.8.5.3 Rest of South America
- 5.8.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Illumina, Inc.
- 6.3.2 Natera, Inc.
- 6.3.3 F. Hoffmann-La Roche Ltd
- 6.3.4 Thermo Fisher Scientific Inc.
- 6.3.5 Laboratory Corporation of America Holdings
- 6.3.6 Quest Diagnostics Incorporated
- 6.3.7 PerkinElmer Inc.
- 6.3.8 Agilent Technologies, Inc.
- 6.3.9 BGI Genomics Co., Ltd.
- 6.3.10 Eurofins Scientific SE
- 6.3.11 Yourgene Health
- 6.3.12 CENTOGENE N.V.
- 6.3.13 Myriad Genetics, Inc.
- 6.3.14 CooperSurgical, Inc.
- 6.3.15 GE HealthCare Technologies Inc.
- 6.3.16 Koninklijke Philips N.V.
- 6.3.17 Bio-Rad Laboratories, Inc.
- 6.3.18 Hologic, Inc.
- 6.3.19 Revvity, Inc.
- 6.3.20 QIAGEN N.V.
- 6.3.21 Sonio SAS
- 6.3.22 Ultrasound AI
- 6.3.23 Delft Imaging
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

