PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119296

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119296
Tea and Coffee Bags - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the tea and coffee bags market size is expected to grow from USD 7.74 billion in 2025 to USD 8.11 billion in 2026 and is forecast to reach USD 10.61 billion by 2031 at 5.52% CAGR over 2026-2031.
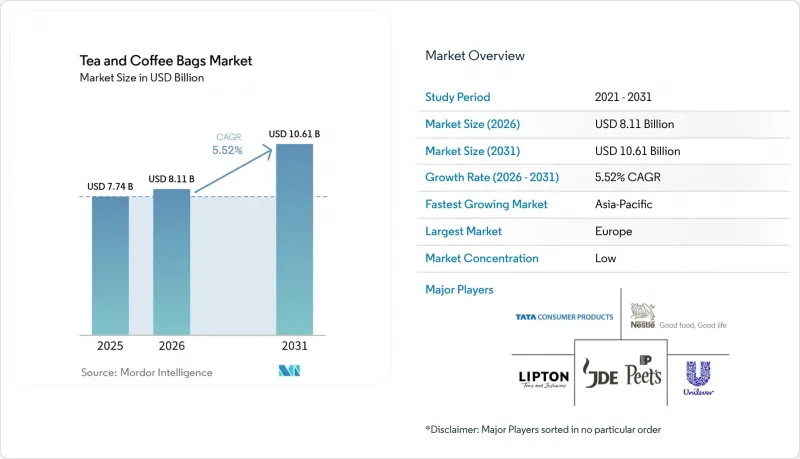
This report is Segmented by Product Type (Tea Bags, Coffee Bags), Flavor (Plain, Flavored), Material Type (Paper, Cotton, Nylon Mesh, Silk, Others), Distribution Channel (Supermarkets/Hypermarkets, Convenience Stores, Online Retail Stores, Other Channels), and Geography (North America, Europe, Asia-Pacific, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Tea and Coffee Bags Market Trends and Insights
Rising demand for convenient single-serve beverages
Convenience is an important purchase consideration for hot beverage consumers, and bag formats offer quick preparation without additional brewing equipment. In the United States, the tea bags and loose tea segment reached USD 1.8 billion in the 52 weeks ending April 2026, increasing 1.5% despite softer volumes in some parts of the category. Single-serve tea and coffee formats fit commuting, travel, office, and short-break occasions because they offer consistent preparation and simple cleanup. The tea and coffee bags market also benefits when consumers use online replenishment and subscription services, which reduce the need to make repeated store visits. These services can support repeat purchases because they make routine household supply easier to maintain. On-the-go consumption reinforces this pattern by creating occasions where loose leaf, whole bean, and equipment-based preparation are less practical.
Increasing premium tea and specialty coffee consumption
Specialty coffee consumption exceeded traditional coffee consumption among American adults for the first time in 2025. The National Coffee Association reported that 46% of American adults drank specialty coffee on the previous day, compared with 42% who drank traditional coffee. Premium single-origin coffee bags and whole-leaf tea sachets give consumers an accessible way to seek a cafe-style experience at home. Tata Consumer Products reported 43% revenue growth in its India coffee business in FY2026 and identified premiumization as a major contributor, while its United Kingdom portfolio emphasized premium mix across Tetley and Teapigs. The tea and coffee bags industry is also gaining demand from hospitality and fine-dining buyers that want premium formats without a complex preparation process. Specialty and artisanal formats provide room for brands to differentiate through origin, blend quality, flavor, and presentation rather than competing only on price.
Higher cost of premium tea and coffee bags
Premium tea and coffee bags often use higher-cost materials such as biodegradable films, specialty papers, cotton, and compostable laminates, increasing production costs. Advanced sealing technologies and customized printing further raise manufacturing expenses. These higher input costs are typically reflected in the final price of premium bagged products. Price-sensitive consumers may therefore prefer conventional tea and coffee bags with lower packaging costs. Smaller brands can also face difficulty adopting premium formats due to limited economies of scale. Consequently, the higher cost of premium tea and coffee bags can restrict their wider adoption, particularly in mass-market segments.
Other drivers and restraints analyzed in the detailed report include:
- Product Innovation in Biodegradable and Compostable Bags
- Growth of office and workplace beverage consumption
- Competition from loose-leaf tea and whole-bean coffee
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The tea bags segment accounted for 68.24% of the market share in 2025, making it the largest product type category. Its dominant position is supported by the widespread consumption of tea across households, workplaces, hospitality establishments, and foodservice outlets. Tea bags remain highly preferred because they offer convenience, portion control, consistent brewing, and easy disposal compared with loose-leaf tea. Strong consumer familiarity with black tea, green tea, herbal tea, and specialty tea bag formats continues to reinforce demand across both developed and emerging markets. Retail availability through supermarkets, convenience stores, online platforms, and institutional channels has further strengthened the segment's market leadership.
The coffee bags segment is projected to grow at a CAGR of 6.29% through 2031, making it the fastest-growing product type in the tea and coffee bags market. Growth is being driven by rising demand for specialty coffee, premium at-home brewing experiences, and convenient single-serve coffee preparation methods. Coffee bags provide a simple brewing solution that combines the portability of instant coffee with a flavor profile closer to freshly brewed ground coffee. Increasing urbanization, busy lifestyles, and higher coffee consumption among younger consumers are accelerating adoption across multiple regions.
The plain flavor segment accounted for 61.76% of the tea and coffee bags market share in 2025, making it the largest flavor category. Its leading position is supported by strong consumer preference for traditional tea and coffee varieties that deliver familiar taste profiles and consistent quality. Plain tea and coffee bags are widely consumed across households, offices, hospitality establishments, and institutional settings due to their versatility and broad acceptance. The segment benefits from the high consumption of classic black tea, green tea, and standard coffee blends across major markets worldwide. Consumers often choose plain variants for everyday consumption because they are suitable for multiple brewing occasions and can be customized with milk, sugar, or other additives.
The flavored segment is projected to grow at a CAGR of 6.83% through 2031, making it the fastest-growing flavor category in the tea and coffee bags market. Growth is being driven by increasing consumer interest in premium, indulgent, and wellness-oriented beverage experiences. Flavored tea and coffee bags, including fruit-infused, herbal, floral, spiced, vanilla, caramel, and other specialty varieties, are attracting younger consumers and urban populations seeking greater product variety. Manufacturers are expanding their flavored portfolios with innovative combinations, seasonal editions, and functional ingredients that offer benefits such as relaxation, digestion support, or energy enhancement.
Complete Report Scope:
- By Product Type
- Tea Bags
- Coffee Bags
- By Flavor
- Plain
- Flavored
- By Material Type
- Paper
- Cotton
- Nylon Mesh
- Silk
- Others
- By Distribution Channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Online Retail Stores
- Other Distribution Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Indonesia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East and Africa
- North America
Geography Analysis
Europe accounted for 34.12% of the tea and coffee bags market share in 2025, making it the largest regional market. The region's leadership is supported by a strong tea-drinking culture in countries such as the United Kingdom, Germany, France, and Poland, along with widespread coffee consumption across Western and Northern Europe. Consumers in Europe show a high preference for convenient single-serve beverage formats, including tea bags and premium coffee bags, which has strengthened retail demand. The presence of well-established beverage brands, extensive supermarket and specialty retail networks, and high household penetration of packaged beverages further supports market growth. Sustainability trends have also accelerated the adoption of biodegradable, compostable, and plastic-free tea and coffee bag materials across the region.
Asia-Pacific is projected to expand at a CAGR of 6.77% through 2031, making it the fastest-growing regional market in the tea and coffee bags industry. Rapid urbanization, rising disposable incomes, and changing lifestyles are increasing demand for convenient packaged beverage products across China, India, Japan, South Korea, and Southeast Asian countries. The region is experiencing strong growth in both traditional tea consumption and modern coffee culture, particularly among younger consumers and urban professionals. Expanding retail infrastructure, e-commerce penetration, and cafe-inspired at-home beverage consumption are further accelerating market demand.
North America represents a mature market characterized by high coffee consumption, growing demand for specialty beverages, and strong adoption of premium and sustainable packaging formats. South America is witnessing steady growth supported by expanding urban populations, increasing packaged beverage consumption, and the region's strong coffee production base. The Middle East and Africa market is developing gradually, driven by rising retail penetration, growing cafe culture, and increasing consumer preference for convenient beverage preparation formats.
- Tata Consumer Products Limited
- Nestle S.A.
- JDE Peet's N.V.
- Unilever PLC
- Lipton Teas and Infusions B.V.
- Associated British Foods plc
- Teekanne GmbH & Co. KG
- The Hain Celestial Group, Inc.
- Bigelow Tea Company
- Dilmah Ceylon Tea Company PLC
- ITO EN, Ltd.
- Wissotzky Tea Ltd.
- Typhoo Tea Limited
- Bettys & Taylors Group Limited
- Whittard Trading Ltd.
- Harney & Sons Fine Teas
- The Republic of Tea, Inc.
- Numi, Inc.
- Massimo Zanetti Beverage Group S.p.A.
- M. M. Ispahani Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for convenient single-serve beverages
- 4.2.2 Growth in on-the-go consumption habits
- 4.2.3 Increasing premium tea and specialty coffee consumption
- 4.2.4 Growth of office and workplace beverage consumption
- 4.2.5 Product innovation in biodegradable and compostable bags
- 4.2.6 Increasing demand for specialty and artisanal beverage formats
- 4.3 Market Restraints
- 4.3.1 Higher cost of premium tea and coffee bags
- 4.3.2 Competition from loose-leaf tea and whole-bean coffee
- 4.3.3 Volatility in tea and coffee raw material prices
- 4.3.4 Stringent packaging and sustainability regulations
- 4.4 Consumer Behavior Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE & GROWTH FORECASTS (VALUE )
- 5.1 By Product Type
- 5.1.1 Tea Bags
- 5.1.2 Coffee Bags
- 5.2 By Flavor
- 5.2.1 Plain
- 5.2.2 Flavored
- 5.3 By Material Type
- 5.3.1 Paper
- 5.3.2 Cotton
- 5.3.3 Nylon Mesh
- 5.3.4 Silk
- 5.3.5 Others
- 5.4 By Distribution Channel
- 5.4.1 Supermarkets/Hypermarkets
- 5.4.2 Convenience Stores
- 5.4.3 Online Retail Stores
- 5.4.4 Other Distribution Channels
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.1.4 Rest of North America
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 Italy
- 5.5.2.4 France
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 Indonesia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 United Arab Emirates
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Ranking Analysis
- 6.4 Company Profiles (Includes Company Highlights, Strategic Information, Core Segments, Financials, Products & Services, Recent Developments)
- 6.4.1 Tata Consumer Products Limited
- 6.4.2 Nestle S.A.
- 6.4.3 JDE Peet's N.V.
- 6.4.4 Unilever PLC
- 6.4.5 Lipton Teas and Infusions B.V.
- 6.4.6 Associated British Foods plc
- 6.4.7 Teekanne GmbH & Co. KG
- 6.4.8 The Hain Celestial Group, Inc.
- 6.4.9 Bigelow Tea Company
- 6.4.10 Dilmah Ceylon Tea Company PLC
- 6.4.11 ITO EN, Ltd.
- 6.4.12 Wissotzky Tea Ltd.
- 6.4.13 Typhoo Tea Limited
- 6.4.14 Bettys & Taylors Group Limited
- 6.4.15 Whittard Trading Ltd.
- 6.4.16 Harney & Sons Fine Teas
- 6.4.17 The Republic of Tea, Inc.
- 6.4.18 Numi, Inc.
- 6.4.19 Massimo Zanetti Beverage Group S.p.A.
- 6.4.20 M. M. Ispahani Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

